
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Chubb's North America Commercial P&C premiums fell 2.3% as it walked away from underpriced large-account and E&S property business.
• Travelers' Business Insurance renewal premium change was 4.8%, with core Middle Market rate increases of 6.1% still holding.
• Both insurers' headline combined ratio improvements came mainly from lighter catastrophe losses and reserve releases, not from better core underlying margins.
Underwriting discipline, meaning the willingness to turn away business priced below its expected cost, is the clearest test now facing Chubb Limited (NYSE:CB) and The Travelers Companies, Inc. (NYSE:TRV), two S&P 500 property and casualty insurers. With parts of the commercial property market softening, both reported strong profits for the three months to June 30, 2026, while accepting slower premium growth. That trade-off matters more than the headline earnings, because it shows whether margins are being protected before a softer pricing phase takes hold.
Two Different Insurers
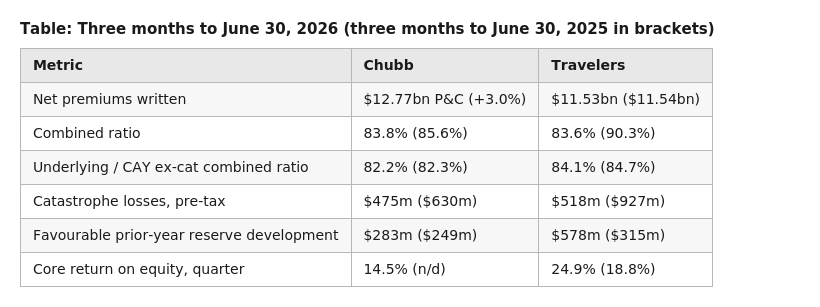
Chubb, headquartered in Zurich, is a global underwriter of commercial, specialty and personal insurance with a growing life business in Asia. In its second-quarter release of July 21, 2026, property and casualty net premiums written were $12.77 billion, up 3.0%, while life premiums rose 7.5% to $1.94 billion.
Travelers is more concentrated on the US. Its results of July 17, 2026, split $11.53 billion of net written premiums into Business Insurance ($5.98 billion), Bond & Specialty Insurance ($1.24 billion) and Personal Insurance ($4.31 billion). Total premiums were flat, partly because the prior-year quarter included $273 million from Canadian operations sold in the first quarter of 2026.
Chubb (NYSE:CB) Pays a Growth Penalty
Chubb's growth figures show discipline in action. North America Commercial P&C premiums fell 2.3%, with major accounts and excess and surplus wholesale property down 9.0%, while middle market and small commercial grew 8.9%. Excluding large-account and E&S property, total P&C premiums rose 6.3%.
Chairman and chief executive Evan Greenberg was explicit: overly soft Underwriting conditions persist in certain areas of property insurance globally, particularly large account and E&S related. He added that the company will not underwrite knowingly at a loss, and said the growth penalty in property will dissipate going forward.
Overseas General, Chubb's international commercial and consumer arm, grew 10.2%, or 4.8% in constant dollars. North America Personal lines, which serve high-net-worth households, grew 6.0%. That breadth lets Chubb shrink where prices are weakest and still expand elsewhere.
Travelers (NYSE:TRV) Still Finds Rate
Travelers' commercial book is still achieving price increases. Business Insurance renewal premium change, which captures both rate and changes in insured exposure, was 4.8%. Chief executive Alan Schnitzer highlighted stable renewal premium change of 6.1% in core Middle Market and 9.4% in the small commercial Select business. Retention was 86% and new business rose 8% to $805 million.
Bond & Specialty premiums grew 14% at a combined ratio of 82.8%. Personal Insurance premiums fell 8%, yet the segment was the most profitable, with a combined ratio of 79.5% and an underlying ratio of 77.3%.
Reading the Ratios
The combined ratio adds losses and expenses as a percentage of earned premium; below 100% is an underwriting profit. Chubb's current accident year ratio excluding catastrophes and Travelers' underlying ratio both remove catastrophe losses and prior-year reserve changes, giving a better view of core pricing adequacy.
The comparison is revealing. Both headline ratios improved, but most of the improvement came from lighter catastrophe losses and larger reserve releases, not from better core margins. Underlying ratios were broadly stable, which is what disciplined underwriting in a softening market should look like: margins held rather than expanded.
Earnings Growth in Context
Chubb's P&C Underwriting income rose 18.8% to $1.94 billion and core Operating Income per share rose 18.2% to $7.26. Net income, however, slipped to $2.85 billion from $2.97 billion, a reminder that reported profit includes Investment gains and losses outside underwriting control.
Travelers' core income rose 44% to $2.16 billion, or $10.04 per diluted share against $6.51. Yet its underlying underwriting gain, which excludes catastrophes and reserve movements, rose just 3% to $1.678 billion. Most of the jump in Earnings therefore came from a quieter catastrophe quarter and reserve releases, not from a step change in pricing.
How Discipline Reaches Shareholders
Walking away from underpriced property reduces premium Volume but protects future loss ratios and reduces the risk of reserve deficiencies later. Both companies are also earning more on their float, the premiums held before claims are paid. Chubb reported record adjusted net investment income of $1.88 billion, up 11.4%. Travelers' after-tax net investment income rose 14% to $883 million.
Capital returns were substantial. Chubb repurchased $979 million of shares and paid $395 million in dividends in the quarter, while its Book Value per share rose 12.3% year on year. Travelers returned $1.577 billion, including $1.311 billion of buybacks, and declared a quarterly Dividend of $1.25 per share; its book value per share rose 21% to $158.81.
What Could Weaken the Case
Greenberg warned that soft market conditions are spreading to certain areas of casualty while financial lines also remain soft. If softness spreads further, disciplined insurers could face longer periods of flat or falling premiums.
Reserve releases are not a recurring source of earnings. Should casualty loss costs prove higher than assumed in earlier accident years, favourable development could narrow or reverse. The second quarter also precedes the peak of the Atlantic hurricane season, so catastrophe losses remain a risk for the third quarter.
Discipline Signals to Track
For Chubb, the key indicators are premium growth excluding large-account and E&S property, commentary on casualty pricing and whether the property growth penalty eases as Greenberg expects. For Travelers, watch renewal premium change in Middle Market and Select, retention, the direction of Personal Insurance premiums and growth in Bond & Specialty.


 Nov 20, 2026





 Please wait processing your request...