
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
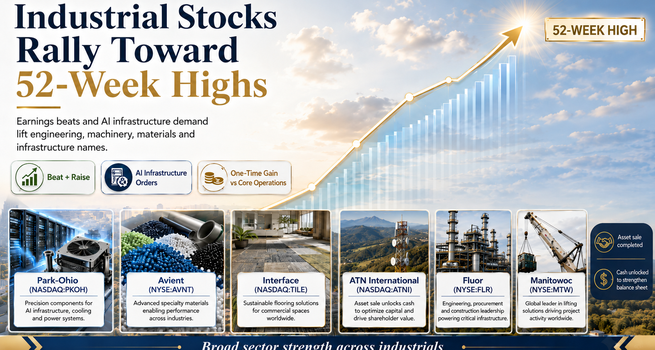
- A broad cluster of industrial stocks is trading near 52-week highs after this week's Earnings .
- Fluor beat estimates but narrowed guidance post-divestiture; Park-Ohio raised guidance on AI Data Center Demand .
- Manitowoc posted the group's largest earnings beat, despite a prior Strong Sell analyst rating.
- Avient and Interface both raised guidance on Margin expansion aided by Tariff refunds.
- ATN International's beat was driven largely by a one-time asset sale gain.
Why Industrial Stocks Are Clustering Near Yearly Highs
A wide set of industrial and industrial-linked names are trading near their 52-week highs this week, as second-quarter earnings results land across engineering and construction, industrial machinery, specialty materials, telecommunications infrastructure and commercial flooring. The breadth of the move spans several distinct end markets, which points to sector-wide positioning rather than isolated, single-stock catalysts.
Independent sector data supports that reading. Industrials is projected among a small group of S&P 500 sectors expected to post double-digit earnings growth in calendar year 2026, and several of this week's biggest movers cited demand tied to artificial intelligence infrastructure construction, including data centers and associated power and cooling systems, as a contributor to order growth. That theme runs through Fluor's energy and infrastructure Backlog and Park-Ohio's engineered products segment alike, suggesting the AI Capital Expenditure cycle is beginning to show up directly in industrial order books rather than remaining confined to technology sector spending alone.
Three patterns explain most of this week's movement: earnings beats accompanied by raised full-year guidance, a strong quarter paired with narrowed guidance due to a portfolio change, and a case where the earnings beat was driven substantially by a one-time gain rather than core operating performance.
A Strong Quarter Paired With Narrowed Guidance
Fluor Corporation (NYSE:FLR) reported second-quarter Revenue of 4.3 billion dollars, up 9 percent year-over-year, with adjusted EPS of 0.91 dollars against a 0.73 dollar consensus, a beat of nearly 25 percent. New awards during the quarter reached 6.1 billion dollars, compared with 1.8 billion dollars in the prior-year period, pushing ending backlog to 26.9 billion dollars, 85 percent of which is reimbursable. The company also returned 300 million dollars to shareholders through repurchases during the quarter, part of a 1.4 billion dollar target for 2026.
Despite the strong quarter, management narrowed full-year 2026 adjusted EBITDA guidance to a range of 500 to 525 million dollars, down from a prior range of 525 to 560 million dollars, a reduction the company attributed to the removal of a previously estimated second-half contribution from its now-divested Mexico joint venture. The narrower guidance illustrates that a strong quarterly beat does not always translate into an unambiguous upward revision to full-year expectations, particularly when portfolio changes affect the comparison.
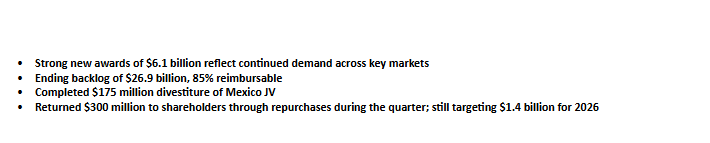
Source: Fluor Corporation, Q2 2026 earnings release, August 7, 2026.
Chief executive Jim Breuer pointed to "the confidence clients have in Fluor to advance their most important investments" as behind the quarter's award activity.
Earnings Beats Paired With Raised Guidance
The following group of movers reported second-quarter results that beat consensus on both revenue and adjusted earnings, then followed those results with upward revisions to full-year guidance. A beat plus a raise is generally read by the market as evidence that outperformance reflects underlying demand strength rather than a one-off timing effect.
Park-Ohio Holdings ( Nasdaq :PKOH) reported record second-quarter consolidated revenue of 440 million dollars against a 425.6 million dollar consensus estimate, up 10 percent year-over-year, with adjusted EPS of 0.93 dollars against an 0.81 dollar consensus estimate, a beat of nearly 15 percent. Growth was broad-based across the company's Supply Technologies, Engineered Products and Assembly Components segments, with all three showing year-over-year sales growth driven in part by demand across aerospace and defense, AI data center, electrical steel and semiconductor end markets. Engineered Products segment backlog reached 252 million dollars, up 23 percent from year-end 2025.
Chairman and CEO Matthew Crawford credited the momentum heading into the guidance raise, noting the company felt "well-positioned to raise the bar for our performance in 2026."
The company raised its full-year 2026 outlook, with net sales guidance increased to a range of 1.70 to 1.73 billion dollars from a prior 1.675 to 1.71 billion dollar range, and adjusted EPS guidance raised to 3.10 to 3.30 dollars from a prior 2.90 to 3.20 dollar range.
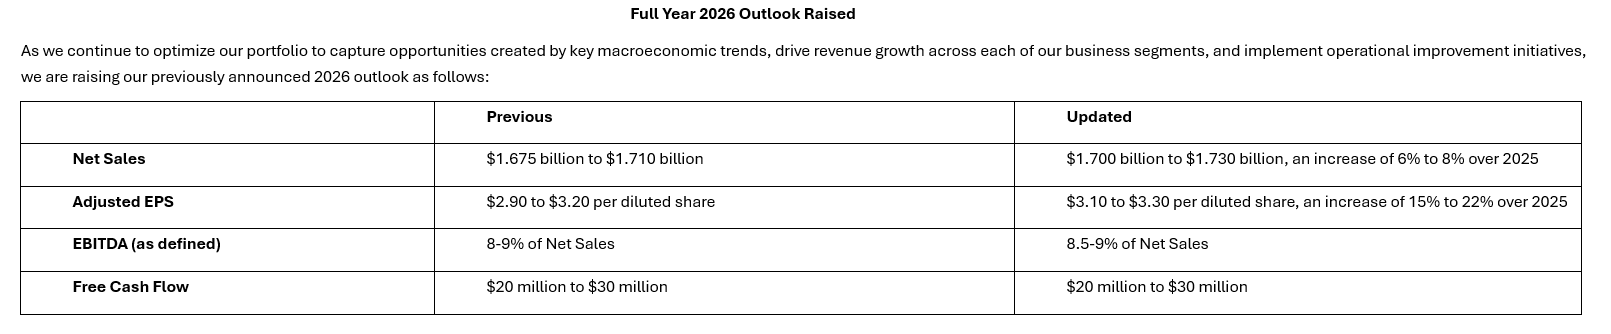 Source: Park-Ohio Holdings Corp., Q2 2026 earnings release, August 5, 2026.
Manitowoc (NYSE:MTW) reported second-quarter net sales of 594.9 million dollars against a 564 million dollar consensus estimate, up 10.3 percent year-over-year, with adjusted diluted EPS of 0.46 dollars against an 0.11 dollar consensus estimate, a beat of more than 300 percent. Orders rose 56.1 percent year-over-year to 708.7 million dollars, pushing backlog to 1.05 billion dollars at quarter end, and adjusted EBITDA rose 85.9 percent year-over-year to 48.9 million dollars, with 330 basis points of margin expansion.
CEO Aaron Ravenscroft described customer sentiment as remaining positive during the quarter, "as strong quoting activity translated into higher order intake."
Management raised full-year 2026 guidance, with net sales now expected in a range of 2.3 to 2.4 billion dollars, up from a prior 2.25 to 2.35 billion dollar range, and adjusted diluted EPS guidance raised to a range of 0.80 to 1.20 dollars from a prior 0.45 to 0.90 dollar range. The scale of the post-earnings move stands out against the stock's prior analyst positioning, discussed further below.
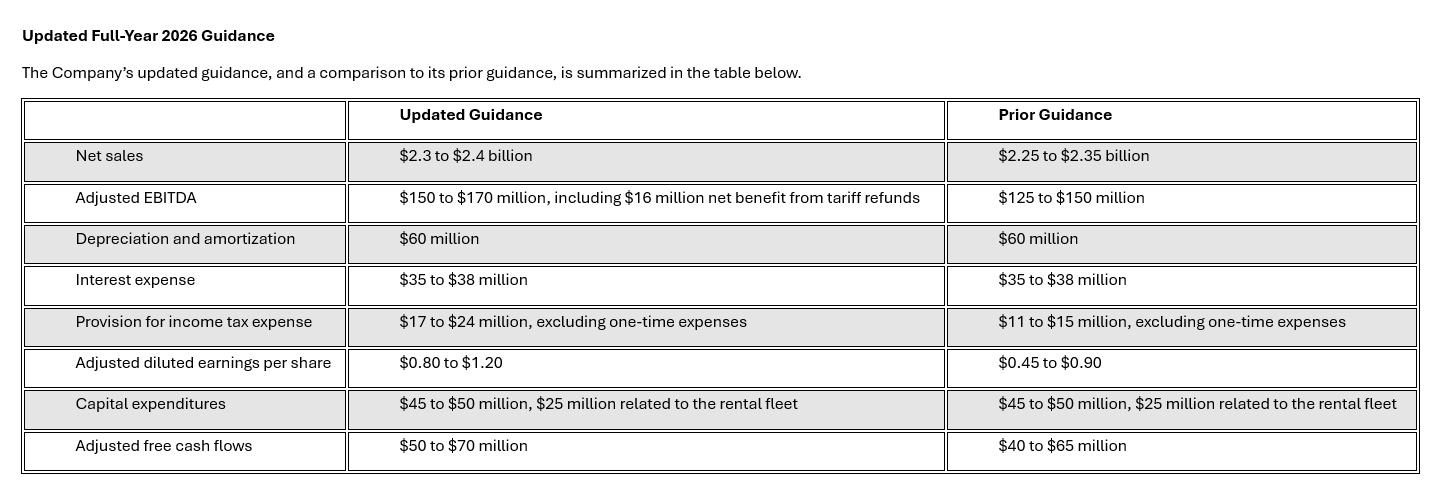 Source: The Manitowoc Company, Q2 2026 earnings release, August 7, 2026.]
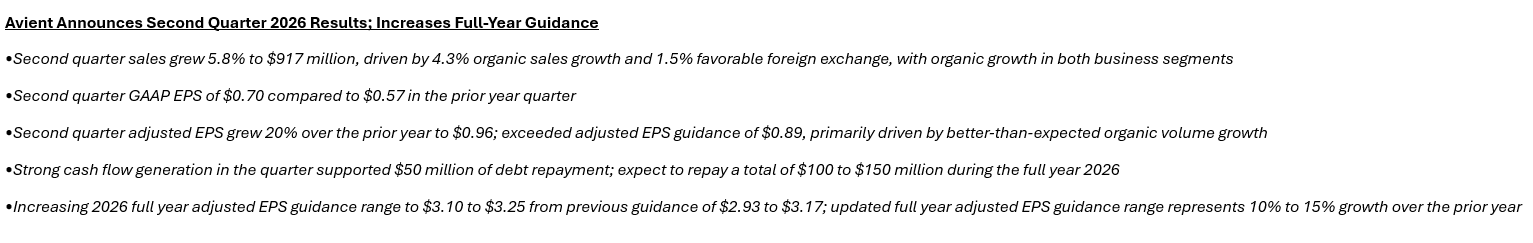
Avient Corporation (NYSE:AVNT) reported second-quarter sales of 917 million dollars against an 898.5 million dollar consensus estimate, up 5.8 percent year-over-year, with adjusted EPS of 0.96 dollars against an 0.89 dollar consensus estimate, a beat of nearly 8 percent. Adjusted EBITDA margin expanded 110 basis points to a record 18.3 percent, with CEO Ashish Khandpur crediting the gain to strategy execution across both Business segments. Management raised full-year 2026 guidance, with adjusted EBITDA now expected in a range of 575 to 603 million dollars and adjusted EPS guidance raised to a range of 3.10 to 3.25 dollars from a prior 2.93 to 3.17 dollar range, representing 10 to 15 percent adjusted EPS growth for the year. The company continued deleveraging with 50 million dollars of Debt repayment during the quarter, part of a planned 100 to 150 million dollars for the full year.
 Source: Avient Corporation, Q2 2026 earnings release, August 6, 2026.
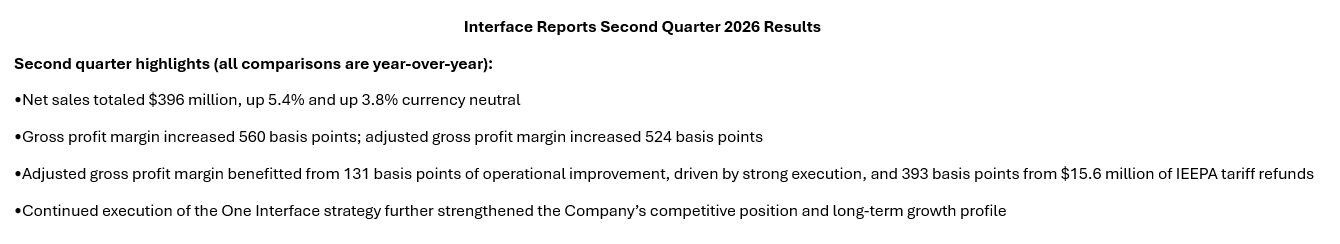
Interface (NASDAQ:TILE) reported second-quarter net sales of 395.7 million dollars against a 391.2 million dollar consensus estimate, up 5.4 percent year-over-year, with adjusted diluted EPS of 0.88 dollars against a 0.63 dollar consensus estimate, a beat of nearly 40 percent. Adjusted Gross Profit Margin rose 524 basis points, with 393 basis points of that improvement attributed to 15.6 million dollars of tariff refunds and the remainder to operational execution.
CEO Laurel Hurd said growth was "broad-based across all regions and product categories," with billings led by the company's Healthcare segment, up 19 percent year-over-year, alongside 5 percent growth in both Education and Corporate Office billings. The company raised full-year 2026 net sales guidance to a range of 1.455 to 1.485 billion dollars from a prior 1.450 to 1.480 billion dollar range, while management noted the updated guidance already includes the second-quarter tariff refund and does not assume additional refunds going forward.
 Source: Interface, Inc., Q2 2026 earnings release, August 7, 2026.
A Beat Driven Largely by a One-Time Gain
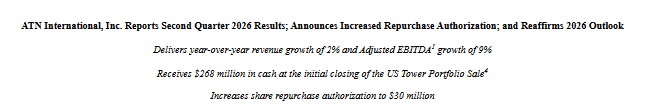
ATN International (NASDAQ:ATNI) reported second-quarter revenue of 184.5 million dollars, in line with a 184.5 million dollar consensus estimate and up 2 percent year-over-year, with Net Income attributable to shareholders of 167.3 million dollars, or 10.71 dollars per diluted share, against a consensus estimate of just 0.12 dollars, a headline beat of more than 8,800 percent. The scale of the headline result reflects a 229.9 million dollar gain recorded on the initial closing of the company's US tower portfolio sale, for which it received approximately 267.7 million dollars in cash during the quarter, rather than a comparable improvement in core operating performance.
CEO Naji Khoury said the tower transaction multiple "far exceeded our current trading multiple," framing the sale as a way to unlock value from infrastructure Assets .
Adjusted EBITDA, which excludes the transaction gain, rose 9 percent year-over-year to 49.7 million dollars, with adjusted EBITDA margin expanding to 27.0 percent from 25.3 percent. The company reaffirmed full-year 2026 adjusted EBITDA guidance in a range of 183 to 193 million dollars, increased its share repurchase authorization to 30 million dollars, and reduced its net debt ratio to 0.91 times from 2.36 times at year-end 2025.
 Source: ATN International, Inc., Q2 2026 earnings release, August 5, 2026.
Risk Considerations
The breadth of this week's move across industrial names carries both structural support and structural risk. A sector-wide earnings beat rate this strong, combined with an AI-driven capital expenditure cycle that appears to be broadening beyond technology companies into their industrial suppliers, suggests underlying demand has genuine support. At the same time, not every rally carries equal conviction from professional analysts. Manitowoc's post-earnings surge follows a prior Strong Sell consensus rating and a 10.33 dollar average analyst price target, a level well below where the stock now trades, indicating that Sell-Side coverage has not yet caught up with the scale of the quarter's order momentum, or alternatively that some analysts remain skeptical the improvement will persist. Investors should also distinguish between earnings quality across the group. ATN International's headline EPS beat was driven substantially by a one-time asset sale rather than recurring operations, a distinction that matters for assessing whether the current share price reflects sustainable earnings power.
Tariff refunds also played a role in margin expansion at Interface this quarter, a benefit that management explicitly noted is not assumed to recur in future guidance. Fluor's narrowed adjusted EBITDA guidance, despite a strong quarterly beat, is a reminder that portfolio changes, in this case a divestiture, can offset underlying operational strength in headline guidance figures even as the market rewards the quarter's execution.

 Nov 20, 2026
 Please wait processing your request...