
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Carpenter Technology Corp (CRS) operates in the specialty alloys space, an area that connects closely to aerospace, defence, and demanding industrial end markets.
• Investor attention often centres on how high-performance materials demand interacts with broader industrial metals cycles.
• Commodity input costs, including nickel, cobalt, and other alloying elements, remain a theme investors may monitor.
• The company sits at the intersection of critical minerals discussion and advanced manufacturing supply chains.
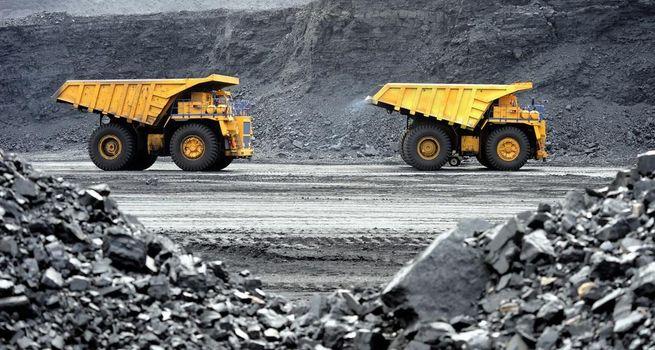
Specialty metals rarely dominate financial headlines the way copper or gold can, yet they underpin some of the most technically demanding products in modern industry. Carpenter Technology Corp (NYSE:CRS) is one of the names that surfaces when investors discuss high-performance alloys, and its position has been drawing renewed market attention. The company produces materials engineered for extreme conditions, and that focus places it in a distinct corner of the industrial metals and mining landscape.
Company Overview
Carpenter Technology Corp is a producer of specialty alloys and engineered materials. Its output is generally associated with applications that demand exceptional strength, corrosion resistance, temperature tolerance, or fatigue performance. These characteristics make its materials relevant to aerospace components, medical applications, energy equipment, and various precision industrial uses.
Unlike a broad commodity miner, Carpenter Technology sits further along the value chain, where metallurgical expertise and processing capability matter as much as raw tonnage. This positioning tends to insulate specialty producers somewhat from the rawest swings in base-metal pricing, though it does not remove commodity exposure entirely. The company’s identity as (CRS) is closely tied to advanced materials rather than simple metal extraction, and that distinction shapes how the market interprets its prospects.
Why the Stock Is in Focus
Several intersecting themes help explain why Carpenter Technology Corp (CRS) has been drawing attention. Aerospace demand narratives, industrial reshoring discussion, and the broader conversation around critical minerals all touch the specialty metals space. When markets debate supply-chain resilience for advanced manufacturing, companies producing high-performance alloys naturally enter the conversation.
There is also a cyclical dimension. Specialty metals producers can benefit when demanding end markets are expanding, and sentiment can shift quickly when those cycles are questioned. Investors are watching how order flow, capacity utilisation, and pricing dynamics evolve.
Industrial Metals and Mining Sector Backdrop
The wider industrial metals and mining sector provides important context. Copper demand tied to electrification, steel cycles linked to construction and infrastructure spending, and aluminium markets responding to global economic conditions all shape the mood across the space. Specialty producers like Carpenter Technology are not immune to these currents, even though their materials serve narrower, higher-value uses.
Critical minerals discussion is particularly relevant. Nickel, cobalt, titanium, and various rare alloying elements feature in both battery-materials debates and advanced-alloy production. As governments and manufacturers emphasise supply-chain security, the sourcing and processing of these inputs gain strategic weight. This backdrop can influence sentiment toward specialty metals names, sometimes independently of near-term financial results. Global economic conditions, interest-rate expectations, and industrial activity indicators all feed into how the sector is perceived at any given moment.
Financial and Operational Themes Investors May Monitor
When assessing Carpenter Technology Corp (CRS), market participants often focus on a set of recurring themes rather than any single figure. These include:
• End-market diversification: How balanced exposure is across aerospace, medical, energy, and industrial applications.
• Order visibility: The degree to which demand appears supported by longer-term commitments.
• Input cost management: How alloying-element costs are managed and passed through.
• Capacity utilisation: Whether facilities are operating at levels that support efficient production.
• Balance-sheet risk: Debt levels, liquidity, and financial flexibility through cycles.
Each of these is qualitative here by design.
Commodity Exposure and Market-Position Angle
Carpenter Technology’s commodity exposure is nuanced. It does not depend on a single metal price the way a pure miner might. Instead, its inputs span a basket of alloying elements, and its output value derives substantially from engineering and processing. This can moderate commodity-price sensitivity, though nickel, cobalt, and similar elements still matter to margins.
The market-position angle is where the specialty story becomes distinctive. Producers with metallurgical depth and qualified positions in demanding supply chains can hold defensible roles, since customers in aerospace and medical fields often require rigorous certification. That qualification process can create barriers that shape competitive dynamics. At the same time, it ties the company to the health of those specific end markets. For investors weighing (CRS), the balance between value-added positioning and end-market concentration is a central consideration.
Potential Catalysts
Potential catalysts that could influence sentiment around Carpenter Technology include shifts in aerospace build rates, evolving defence and energy demand, and developments in critical minerals policy. Broader infrastructure spending and industrial activity trends may also feed through indirectly. Any of these could act as a catalyst in either direction, and their eventual impact remains uncertain.
Operational milestones, such as capacity developments or product qualifications, are additional areas the market may watch.
Key Risks and Uncertainties
A balanced view requires attention to risks. Specialty metals producers face cyclicality tied to their end markets; a slowdown in aerospace or industrial demand could weigh on performance. Input-cost volatility for alloying elements introduces margin uncertainty. Concentration in particular sectors, while a source of expertise, can amplify exposure to downturns in those areas.
Broader risks include global economic conditions, commodity-price volatility across the metals complex, competitive pressures, and execution challenges. Balance-sheet risk is always relevant through cycles.
What Investors May Watch Next
Looking ahead, market participants are likely to monitor aerospace and industrial demand signals, alloying-element cost trends, and any commentary the company provides on order flow and utilisation. Developments in critical minerals policy and supply-chain security discussion may also shape the narrative.
Conclusion
Carpenter Technology Corp (CRS) occupies a distinctive position within the industrial metals and mining landscape, anchored in specialty alloys rather than raw commodities. Its exposure to aerospace, medical, and demanding industrial markets, combined with the broader critical minerals conversation, helps explain the market attention it has been drawing. Yet that attention comes with genuine uncertainties, from cyclical demand to input-cost volatility.
This article is for informational purposes only and does not constitute investment advice or a recommendation to buy, sell, or hold any security. Share prices can rise or fall, and past performance does not guarantee future results. Investors should conduct independent research and consult a licensed financial adviser before making investment decisions.

 Nov 02, 2026
 Please wait processing your request...