
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• DPM Metals is a gold producer recognized for low all-in sustaining costs at its core operations.
• The company combines mining with an interest in metals trading and smelting, broadening its precious-metals footprint.
• A disciplined balance sheet and a track record of capital returns distinguish DPMLF from many peers.
• Operations concentrated in Eastern Europe give the company a distinctive jurisdictional profile.
In a sector where attention often gravitates toward the largest producers and the flashiest explorers, DPM Metals Inc. (OTCMKTS:DPMLF) tends to occupy a quieter, more understated position, and that is precisely what makes it intriguing to value-minded precious-metals investors. The company has built a reputation as a disciplined, low-cost gold producer that generates healthy margins and has shown a willingness to return capital to shareholders rather than chase growth at any price. Add to that an interest in metals trading and smelting, and DPM Metals presents a more diversified precious-metals profile than a typical single-mine producer. The result is a stock that some observers consider a hidden gem: profitable, well-managed and arguably underappreciated relative to its quality. Of course, no gold producer escapes the gravitational pull of metal prices and operational realities, and DPMLF is no exception.
Company Overview
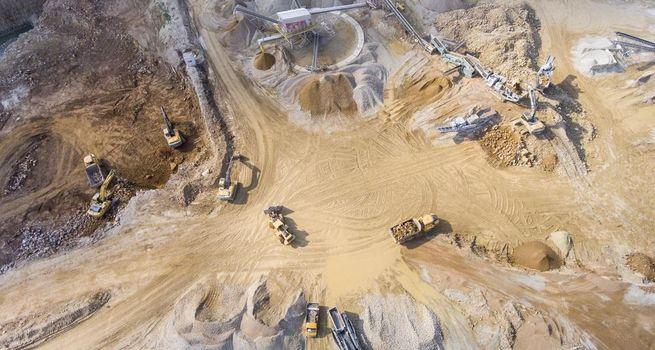
DPM Metals is a gold mining company whose core producing assets are located in Eastern Europe, where it operates mines that have historically delivered gold at competitive costs. The company's identity rests heavily on operational efficiency; it is widely regarded as a low-cost producer, a trait that translates directly into stronger margins and resilience across the gold-price cycle. Beyond its mining operations, DPM Metals holds an interest in metals trading and smelting activities, giving it exposure to the processing and movement of precious and other metals in addition to mining them. This combination provides a degree of diversification within the precious-metals value chain that pure miners lack. The company has cultivated a reputation for prudent financial management, maintaining a conservative balance sheet and returning cash to shareholders through dividends and buybacks at various points.
Rather than pursuing scale for its own sake, DPM Metals has generally emphasized quality, profitability and disciplined capital allocation, positioning DPMLF as a producer focused on generating durable cash flow.
Why the Stock Is in Focus
DPM Metals attracts attention for reasons rooted in quality rather than spectacle. Chief among them is its cost position; as a low-cost producer, the company captures a larger share of every dollar of gold revenue as profit, which becomes especially valuable when gold prices are firm and provides a cushion when they soften. This efficiency underpins strong free cash flow, which the company has at times deployed toward shareholder returns, a feature that resonates with investors seeking income and capital discipline in a sector not always known for either. The metals trading and smelting interest adds a differentiated layer, broadening the company's precious-metals exposure beyond pure mining. There is also a value angle: some market participants believe DPM Metals trades at a discount to its underlying quality, framing DPMLF as an under-the-radar name that could re-rate if its merits become more widely recognized.
In a buoyant gold environment, a profitable, well-run producer like DPM Metals naturally moves into sharper focus.
Gold, Silver and Precious-Metals Market Backdrop
As a gold-focused producer, DPM Metals is firmly tied to the dynamics of the precious-metals market. Gold's enduring role as a store of value and a hedge against inflation, currency debasement and geopolitical uncertainty drives its demand, while its price is influenced by real interest rates, central-bank buying, safe-haven flows and investor sentiment. For a low-cost producer, a rising gold price is particularly powerful because costs are relatively fixed, so additional revenue flows disproportionately to the bottom line, expanding margins. The company's smelting and trading interest also connects it to the broader flows of precious and other metals, adding a dimension beyond pure gold price exposure. While silver and other precious metals shape the wider sector narrative, DPM Metals' production is centered on gold, making the yellow metal the dominant external variable.
A supportive gold environment enhances both the company's profitability and investor appetite for quality producers, whereas a sustained downturn would compress margins and dampen sentiment, even for an efficient operator like DPMLF.
Key Catalysts Driving Investor Interest
Several catalysts can shape the DPM Metals story. The most fundamental is the gold price itself, since the company's leverage to gold, amplified by its low cost base, means that sustained strength can drive outsized margin expansion. Operational performance is a second catalyst: consistent production, stable or falling costs, and reliable execution at its core mines reinforce the quality narrative. Capital-return decisions form a third catalyst; dividends and share buybacks can attract income-oriented investors and signal management's confidence in cash generation. The performance and contribution of the metals trading and smelting interest provide another lever, as this segment diversifies and can complement mining earnings. Reserve and resource updates, along with any organic growth or exploration success around existing operations, can extend mine lives and support the long-term outlook.
Finally, any narrowing of the perceived valuation gap, as the market more fully appreciates the company's efficiency and discipline, could itself act as a re-rating catalyst. Together, these factors keep DPMLF on the radar of quality-focused precious-metals investors.
Financial and Valuation Considerations
DPM Metals is often discussed through the lens of financial quality, which sets it apart from many peers. The company's low all-in sustaining costs translate into robust margins and strong free-cash-flow generation, attributes that investors typically prize in cyclical mining names. A conservative balance sheet, generally carrying limited debt, reduces financial risk and gives the company flexibility through the gold cycle. These characteristics support a track record of returning cash to shareholders, which can make the stock appealing to those seeking yield alongside precious-metals exposure. In valuation terms, miners are commonly assessed on cash flow, free-cash-flow yield, cost position and balance-sheet strength rather than headline earnings alone, given the volatility of reported profits. A recurring theme around DPMLF is the argument that it may trade at a discount to its intrinsic quality, with the smelting and trading interest sometimes underappreciated by the market.
Investors should remember that, however efficient, the company's results remain sensitive to gold prices, so valuation must always account for the underlying cyclicality.
Growth Outlook and Project Pipeline
DPM Metals' growth philosophy leans toward disciplined, value-accretive expansion rather than aggressive scale-chasing. The company's outlook rests on sustaining and optimizing its existing low-cost operations while selectively advancing growth opportunities that meet its return thresholds. This may include extending mine lives through exploration near current operations, optimizing throughput and recoveries, and evaluating development projects or acquisitions that fit its quality-focused strategy. The metals trading and smelting interest also offers avenues to add value within the broader precious-metals chain. Because the company prioritizes profitability and capital discipline, its growth is likely to be measured and selective, aimed at preserving the strong margins and cash generation that define it. For investors, the central question is whether DPM Metals can replace and grow reserves over time while maintaining its cost advantage, ensuring that production does not simply deplete without renewal.
A pipeline that balances organic extension with disciplined opportunity could allow DPMLF to sustain its cash-generative model well into the future, supporting both stability and the potential for shareholder returns.
Major Risks Investors Should Watch
Despite its quality reputation, DPM Metals carries meaningful risks. Gold-price risk is paramount; as a price-taker, the company's revenue and margins, however efficient, would compress in a sustained downturn. Jurisdictional risk is notable given the concentration of its core operations in Eastern Europe, where political, regulatory, tax and permitting considerations can evolve and affect operations. Operational risk includes the usual mining challenges of grade variability, recovery rates, equipment performance and cost inflation in labor, energy and consumables. Concentration risk arises if a large share of production depends on a limited number of assets, making the company vulnerable to disruptions at any single operation. The metals trading and smelting interest, while diversifying, introduces its own market and operational exposures. Reserve depletion is a longer-term risk if the company cannot replenish ounces.
Finally, currency movements and shifts in investor sentiment toward mid-tier precious-metals equities can amplify share-price swings. Investors weighing DPMLF should balance its strengths against these tangible and interconnected risks.
What Could Drive the Stock Next
Looking forward, the DPM Metals narrative is likely to be driven by a blend of execution, capital allocation and macro forces. On the operational front, continued delivery of low-cost production and stable performance at its core mines would reinforce the quality thesis that underpins the stock. Capital-return announcements, whether dividends or buybacks, could attract additional investor interest and validate the company's cash-generative profile. Reserve and resource updates, along with any progress on organic growth or selective expansion, would speak to the durability of the production base. The contribution of the trading and smelting interest may also influence the story. Externally, the direction of the gold price remains the most powerful single variable; sustained strength would amplify the company's margins, while weakness would test even its efficient operations. Any shift in market recognition of the company's underlying quality could itself drive a re-rating.
For DPMLF, the combination of disciplined execution and a constructive gold backdrop is likely to determine the path ahead.
Conclusion
DPM Metals makes its case not through size or spectacle but through quality, efficiency and discipline. Its low-cost gold operations generate strong margins and free cash flow, its balance sheet is conservatively managed, and its willingness to return capital sets it apart from many peers, while a metals trading and smelting interest adds a distinctive dimension. Together, these features explain why some observers regard DPMLF as a hidden winner within the precious-metals space, potentially undervalued relative to its merits. Yet the company is not immune to the forces that shape all gold producers: its results remain tethered to the gold price, its operations carry jurisdictional and operational risks, and reserves must be replenished over time. For investors who prize cash generation and capital discipline, DPM Metals offers an analytically compelling profile, provided they remain mindful of the cyclical and regional realities that accompany it.
The story will be told in costs, cash flow and the gold market's direction.

 Nov 02, 2026
 Please wait processing your request...