
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• DRDGOLD recovers gold from surface tailings, a model that avoids the hazards of deep underground mining.
• The company has a notable history of paying dividends, making DRD attractive to income-focused investors.
• Its retreatment approach carries an environmental remediation dimension as it reprocesses old mine waste.
• DRDGOLD operates in South Africa, exposing it to local power, currency and regulatory factors.
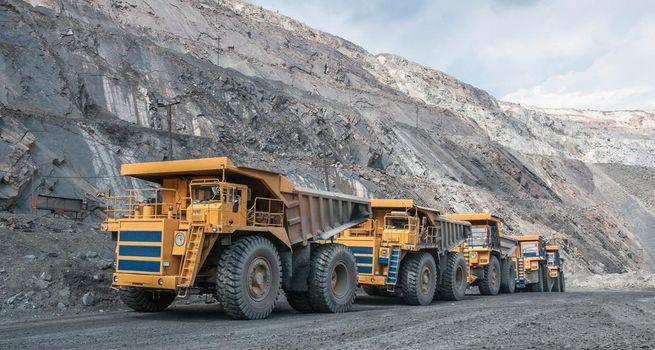
Most gold miners dig deeper and blast harder to reach their ore; DRDGOLD Limited (NYSE:DRD) takes a fundamentally different path by mining what previous generations left behind. The company specializes in recovering gold from tailings, the vast dumps of processed material that accumulated over more than a century of mining around South Africa's gold fields. This retreatment model gives DRDGOLD a personality unlike that of a conventional producer: it largely sidesteps the safety hazards, depth challenges and capital intensity of deep underground mining, instead reprocessing surface material with established technology. Layered on top is a reputation for returning cash to shareholders through dividends, a feature that draws income-oriented investors to the gold space. Some market watchers consider DRD one of the most underrated and differentiated ways to play gold, while others focus on the South African operating environment and the finite nature of tailings resources.
Company Overview
DRDGOLD is a South African gold producer whose core business is the recovery of gold from surface tailings, the residual material left over from decades of prior mining and processing. Rather than sinking shafts and extracting fresh ore, the company reclaims and reprocesses these tailings using metallurgical recovery techniques, extracting the residual gold that earlier, less efficient methods left behind. This approach transforms old mine waste into a productive resource and carries an inherent environmental remediation benefit, as reprocessing and relocating tailings can help rehabilitate land. DRDGOLD's operations are concentrated around major South African gold-mining regions, where enormous volumes of historic tailings exist. The company has invested in infrastructure to consolidate and process this material efficiently, and it has explored integrating renewable energy to manage its power needs and costs.
With a model centered on surface retreatment, DRDGOLD avoids many of the depth-related and safety challenges that burden conventional South African deep mines, positioning DRD as a lower-operational-risk producer with a distinctive, sustainability-tinged narrative.
Why the Stock Is in Focus
DRDGOLD commands attention for several differentiating reasons. The first is its business model: by recovering gold from tailings rather than mining underground, the company avoids the labor-intensive, hazardous and capital-heavy nature of deep mining, which has historically plagued South African gold producers. This translates into a comparatively simpler operational profile and can mean steadier, more predictable output. The second draw is income; DRDGOLD has built a reputation for paying dividends, a relatively uncommon and prized feature among gold equities, attracting investors who want both metal exposure and cash returns. The third is the environmental and sustainability angle, as reprocessing tailings cleans up legacy mine waste and rehabilitates land, aligning with growing investor interest in responsible mining. Add the leverage to gold prices that any producer carries, and DRD becomes a multi-dimensional story.
Some observers argue the stock is underappreciated relative to its differentiated, lower-risk model and dividend track record, which keeps DRDGOLD firmly in the conversation among gold-focused investors.
Gold, Silver and Precious-Metals Market Backdrop
DRDGOLD is, at its heart, a gold-price-driven business, so the precious-metals backdrop is central to its fortunes. Gold's enduring appeal as a store of value and a hedge against inflation, currency weakness and geopolitical instability underpins demand, with its price shaped by real interest rates, central-bank activity, safe-haven flows and sentiment. For a tailings retreatment company, the gold price interacts with the model in a particular way: because the material being processed is low-grade by nature, higher gold prices can make more tailings economically viable to reprocess, potentially extending the resource and improving margins. The South African rand adds another layer, since the company earns gold revenue in dollars while incurring many costs in local currency; a weaker rand can boost margins, while a stronger one can compress them. Although silver and other precious metals frame the wider sector, DRDGOLD is firmly a gold story.
The practical implication is that DRD's profitability and the longevity of its tailings resource are both sensitive to the prevailing and expected gold price.
Key Catalysts Driving Investor Interest
Several catalysts can move the DRDGOLD story. The gold price is the most fundamental, since higher prices lift margins and can expand the economically recoverable portion of the company's tailings resource. Dividend declarations are a major catalyst for this particular stock, given its income reputation; the size and consistency of payouts can significantly influence investor sentiment. Operational performance, including throughput, recovery rates and cost control across its retreatment facilities, forms another important driver. Investment in infrastructure and renewable energy, aimed at securing reliable, lower-cost power, represents a forward-looking catalyst, particularly relevant in a country where electricity supply has been a persistent challenge. The expansion or extension of the tailings resource base, whether through new tailings sources or improved recovery, can lengthen the company's production runway. The South African rand exchange rate acts as a recurring swing factor for margins.
Finally, any broader market recognition of the model's differentiated, lower-risk character could re-rate the stock. Together, these catalysts make DRD a name with multiple potential inflection points.
Financial and Valuation Considerations
DRDGOLD presents a financial profile shaped by its unusual model. Tailings retreatment typically involves lower capital intensity and avoids the deep-mining cost structures that burden conventional producers, which can support healthy margins and cash generation when gold prices are favorable. The company has often maintained a conservative balance sheet with limited debt, giving it flexibility, and its dividend history makes free-cash-flow yield and payout sustainability central to how investors assess it. Because the ore grade is inherently low, profitability is sensitive to both the gold price and the rand exchange rate, so margins can swing with these variables. In valuation terms, investors typically weigh cash flow, dividend yield, cost position and the remaining life and scale of the tailings resource, rather than relying on simple earnings multiples. A recurring argument is that DRD may be undervalued relative to its lower-risk operational profile and income credentials.
Still, any valuation must account for the finite nature of tailings, the gold-price dependence and the South African operating context that frames the company's results.
Growth Outlook and Project Pipeline
DRDGOLD's growth outlook is tied to the scale and longevity of the tailings it can access and reprocess. The company's pipeline revolves around consolidating and expanding its retreatment operations, securing additional sources of tailings, and improving recovery and efficiency to extend the productive life of its resource. Because tailings are a finite legacy of past mining, a central strategic objective is to extend the runway by accessing new material and optimizing the processing of existing dumps. Investment in infrastructure, including efforts to integrate renewable energy and stabilize power supply, supports both cost control and operational reliability, which underpin sustainable production. The environmental remediation dimension can also align the company with regulatory and community expectations, potentially smoothing access to additional tailings.
The growth question for investors is whether DRDGOLD can keep replenishing and extending its resource base while maintaining margins, thereby sustaining its cash-generative, dividend-paying model over the long term. A pipeline that successfully lengthens the tailings life would reinforce the durability of the DRD story.
Major Risks Investors Should Watch
DRDGOLD carries a distinctive set of risks alongside its advantages. Gold-price risk is paramount, as lower prices squeeze margins and can shrink the economically recoverable portion of low-grade tailings. South African operating risk is significant and multifaceted, encompassing unreliable electricity supply, regulatory and political factors, labor considerations and broader economic conditions in the country. Currency risk is material, since a stronger rand can erode the margin benefit the company derives from earning in dollars while spending in local currency. Resource-life risk is inherent to the model, because tailings are finite and must be continually replenished to sustain production. Operational risks include variability in recovery rates and processing efficiency. Environmental and regulatory obligations, while also an opportunity, carry compliance costs and responsibilities. Dividend sustainability depends on continued cash generation, so a downturn could pressure payouts that investors prize.
Finally, sentiment toward South African equities and gold producers can amplify share-price volatility. Investors should weigh these interconnected risks against the model's genuine strengths.
What Could Drive the Stock Next
The next phase of the DRDGOLD story is likely to be shaped by gold prices, currency dynamics and operational execution. A firm or rising gold price would lift margins and could extend the economic life of the tailings resource, while a weaker price would do the opposite. The rand exchange rate will remain a key swing factor for profitability. Dividend announcements will continue to be closely watched given the stock's income identity, with consistency and sustainability central to sentiment. Progress on securing reliable, lower-cost power, including renewable-energy initiatives, could improve cost stability in a challenging electricity environment. The company's success in accessing new tailings sources and extending its resource life will speak to the durability of the model. Any broader recognition of DRDGOLD's differentiated, lower-operational-risk character could prompt a re-rating.
Externally, sentiment toward South African equities and the gold sector will color how the market receives each development. For DRD, the blend of macro tailwinds and steady execution will largely determine its trajectory.
Conclusion
DRDGOLD stands apart in the gold sector by building its business on the residue of past mining rather than fresh ore. Its tailings retreatment model avoids the depth, danger and capital intensity of conventional South African mines, while its dividend history and environmental remediation dimension give it a distinctive, income-tinged identity that some investors consider underrated. These strengths make DRD a genuinely differentiated way to gain gold exposure. Yet the company cannot escape the realities that frame it: heavy sensitivity to gold prices and the rand, the finite nature of its tailings resource, and the operational and regulatory challenges of its South African setting. Dividend sustainability, too, rests on continued cash generation.
For investors drawn to a lower-operational-risk, cash-returning gold play, DRDGOLD offers an analytically intriguing case, provided they remain mindful of the price, currency, resource-life and country-specific risks that accompany its undeniable points of difference.

 Nov 02, 2026
 Please wait processing your request...