
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Fortuna Silver Mines operates across multiple countries, spreading its production base geographically.
• The company earns revenue from both silver and gold, giving it a balanced precious-metals profile.
• Its expansion into West Africa added meaningful gold output and reshaped the investment story.
• Cost discipline and jurisdictional management are central themes for FSM shareholders.
Fortuna Silver Mines Inc. (NYSE:FSM) has quietly transformed itself from a regionally focused silver producer into a more diversified precious-metals company with assets stretching across two continents. That evolution has changed the way investors perceive the stock. Where once it was viewed primarily as a silver play tied to Latin American geology, it now carries a meaningful gold component and a broader geographic spread that alters its risk and reward profile. After periods of volatility shaped by metal prices, operational challenges, and jurisdictional headlines, some market observers have begun asking whether FSM is positioned for a rebound. Answering that requires looking beyond the ticker's recent swings and examining the company's underlying assets, the balance between its silver and gold output, and the macro forces shaping the precious-metals complex.
Fortuna's story is one of diversification and adaptation, and understanding it means appreciating how those choices influence both opportunity and exposure.
Company Overview
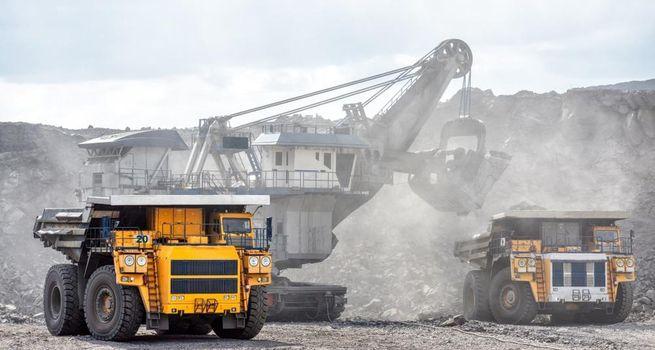
Fortuna Silver Mines is a precious-metals producer that has built a portfolio of operating mines across Latin America and, more recently, West Africa. Historically rooted in silver production in countries with deep mining traditions, the company expanded its reach through acquisitions and development that broadened both its commodity mix and its geographic footprint. Today the company produces a combination of silver and gold, with the relative contribution of each metal varying by site. Its move into West Africa marked a significant strategic shift, adding substantial gold output and exposing it to new operating environments. This diversification was designed to reduce reliance on any single mine, metal, or jurisdiction. Fortuna operates underground and open-pit mines, applies conventional processing methods, and pursues exploration to extend mine lives and grow resources.
The company's management has emphasized operational discipline and portfolio balance, positioning Fortuna as a mid-tier producer rather than a single-commodity specialist, and giving it a more varied revenue base than many silver-focused peers.
Why the Stock Is in Focus
Fortuna Silver Mines draws attention for several reasons, beginning with its hybrid identity as both a silver and gold producer. This dual exposure means the stock can benefit from rallies in either metal, attracting investors who want diversified precious-metals participation without committing to a pure-play name. The company's geographic transformation, particularly its expansion into West Africa, generated significant interest because it reshaped the production profile and introduced new growth potential. FSM also tends to feature in discussions about mid-tier miners that could re-rate if metal prices strengthen and operational execution improves. Periodic news on production results, cost trends, jurisdictional developments, and project milestones keeps the stock in the conversation. For value-oriented investors, the appeal often lies in the possibility that the market has not fully recognized the company's diversification and gold contribution.
For others, the focus is on whether Fortuna can convert its broadened asset base into consistent cash flow, making it a closely watched name within the sector.
Gold, Silver and Precious-Metals Market Backdrop
The market environment for Fortuna Silver Mines reflects the interplay of gold and silver dynamics. Gold typically responds to real interest rates, central-bank purchasing, currency trends, and geopolitical uncertainty, often serving as a store of value during turbulent periods. Silver carries those monetary characteristics but adds substantial industrial demand, with applications in solar energy, electronics, and electrification driving a portion of its consumption. Because Fortuna earns revenue from both metals, its fortunes are tied to the combined behavior of these markets. Gold's relative stability can cushion the company during periods when silver is volatile, while silver's leverage can amplify upside during precious-metals rallies. The silver-to-gold ratio, industrial demand signals, and broad macro variables such as inflation expectations and monetary policy all shape the backdrop.
For a diversified producer like FSM, this balanced exposure can smooth some of the extremes seen in single-metal miners, though it does not eliminate the cyclical nature of the precious-metals sector that ultimately governs the company's profitability.
Key Catalysts Driving Investor Interest
Several catalysts can influence Fortuna Silver Mines and sustain investor engagement. Metal prices are foremost: rising gold or silver prices can quickly expand margins given the operating leverage inherent in mining. Operational performance is another key driver, including production volumes, grade trends, recovery rates, and the smooth running of newer assets that materially affect output. The integration and ramp-up of its West African gold operation has been a focal point, as its contribution shifts the company's overall metal mix and scale. Cost management is a quieter but critical catalyst; improvements in all-in sustaining costs can transform the investment case. Exploration success that extends mine lives or upgrades resources can also re-rate the stock. Jurisdictional developments, including permitting, taxation, and regulatory matters across its operating countries, can move sentiment in either direction.
Finally, broader shifts in precious-metals sentiment and capital flows into mid-tier producers can lift or pressure FSM, reflecting its position within the diversified miner cohort.
Financial and Valuation Considerations
Evaluating Fortuna Silver Mines requires attention to its diversified revenue base and the variability of mining economics. Because the company produces both silver and gold, analysts often assess its blended cost structure, the contribution of each metal, and how margins respond across different price scenarios. Common reference points include price-to-cash-flow, enterprise value relative to production, and all-in sustaining costs, since reported earnings can fluctuate meaningfully between periods due to commodity swings and non-cash items. Balance-sheet considerations such as debt levels, liquidity, and the capacity to fund capital projects without excessive dilution are important, particularly for a company that has grown through acquisition. Fortuna's diversification can support a steadier valuation profile than pure-play silver names, though it still carries the cyclicality of the sector.
Rather than anchoring on any single figure, it is more useful to consider how the company's geographic spread, metal mix, and cost discipline position it across a range of plausible precious-metals environments and operating outcomes over time.
Growth Outlook and Project Pipeline
Fortuna Silver Mines' growth outlook centers on optimizing its existing operations, extending mine lives through exploration, and realizing the full potential of its expanded asset base. The company's move into West Africa added a substantial gold operation that has been central to its growth narrative, and the success of that asset's performance shapes expectations for scale and cash generation. Across its portfolio, Fortuna pursues drilling programs aimed at upgrading resources, identifying new ore zones, and prolonging the productive lives of established mines. Efficiency initiatives and processing improvements form part of the strategy to control costs and recover more metal. The pipeline's success depends on disciplined execution, including delivering projects on budget, managing permitting across diverse jurisdictions, and maintaining stable operations. Investors assessing the growth story typically focus on whether the company can grow output profitably and sustainably rather than simply expanding volume.
Consistent operational delivery, prudent capital allocation, and credible guidance are the signals that distinguish durable growth from speculative expansion for FSM.
Major Risks Investors Should Watch
Fortuna Silver Mines faces a range of risks that warrant careful consideration. Commodity-price risk is fundamental, as declines in gold or silver can compress margins given mining's operating leverage. Jurisdictional risk is especially pronounced for a company operating across multiple countries in Latin America and West Africa, each with its own regulatory framework, taxation regime, permitting process, and political environment; changes in any of these can affect operations and profitability. Operational risks include grade variability, geological surprises, equipment issues, and potential disruptions at individual mines. The ramp-up and ongoing performance of newer assets carry execution risk. Cost inflation in energy, labor, and consumables can erode margins even when metal prices hold steady. Currency fluctuations across the multiple jurisdictions add complexity. Security and social-license considerations can also affect operations in certain regions.
Finally, capital-allocation decisions, debt servicing, and potential dilution from financing activities could weigh on shareholders. These factors make FSM a stock that requires close monitoring of both macro and company-specific developments.
What Could Drive the Stock Next
The next chapter for Fortuna Silver Mines is likely to hinge on a combination of metal prices and operational delivery. Strengthening gold or silver prices, driven by monetary uncertainty, central-bank demand, or industrial trends, could lift margins and renew investor enthusiasm for diversified producers. On the company-specific side, evidence of strong and stable performance from its key assets, including the West African gold operation, could reinforce the rebound thesis. Demonstrated cost discipline, encouraging exploration results, and successful execution of growth projects would strengthen the fundamental case and potentially support a re-rating. Conversely, weaker metal prices, operational setbacks, jurisdictional shocks, or rising costs could dampen momentum. Capital-allocation decisions and balance-sheet management will also shape sentiment. Because Fortuna spans multiple metals and regions, its trajectory will reflect a blend of macro forces and granular operating outcomes.
Investors watching the stock should track both the broad precious-metals narrative and the specific signals that reveal whether the company's diversification is translating into consistent results.
Conclusion
Fortuna Silver Mines has reinvented itself into a diversified precious-metals producer, blending silver and gold output across a broad geographic footprint that now spans Latin America and West Africa. That transformation has given the stock a different complexion than the single-metal miners it is often grouped with, offering balanced exposure that can soften some volatility while introducing fresh jurisdictional considerations. Whether FSM is genuinely poised for a rebound depends on the interplay of metal prices, operational execution, and cost discipline, none of which any single investor controls. The company's expanded asset base and dual-metal profile create real potential, but they come paired with the inherent risks of cross-border mining. For those studying the sector, Fortuna offers an instructive example of diversification in action and the trade-offs it entails.
The key takeaway is to approach the stock analytically, weighing both its rebound potential and its multifaceted risks with a clear and balanced perspective.

 Nov 02, 2026
 Please wait processing your request...