
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Namib Minerals is positioned as an African-focused gold producer and developer with legacy operations and restart ambitions.
• The company's appeal blends near-term production with the optionality of expanding output as gold prices stay elevated.
• Southern Africa offers rich geology but introduces jurisdiction, currency and infrastructure considerations.
• Speculative interest reflects the leverage smaller gold names carry to bullion's direction and to operational milestones.
Few corners of the equity market move as quickly on sentiment as small-capitalization gold names, and Namib Minerals (NASDAQ:NAMM) sits squarely in that category. The company has captured speculative attention by pairing a recognizable African gold footprint with the promise of expanded production into a strong bullion environment. For traders and longer-horizon investors alike, NAMM represents the classic high-beta gold proposition: a business whose share price can swing sharply on the twin engines of metal prices and project execution. The goal is not to tell anyone what to do, but to lay out the moving parts so the story is easier to understand. Gold's recent strength has lifted the entire sector, yet smaller producers and developers behave differently from blue-chip miners, and understanding that distinction is essential before forming any view on a name like NAMM.
Company Overview
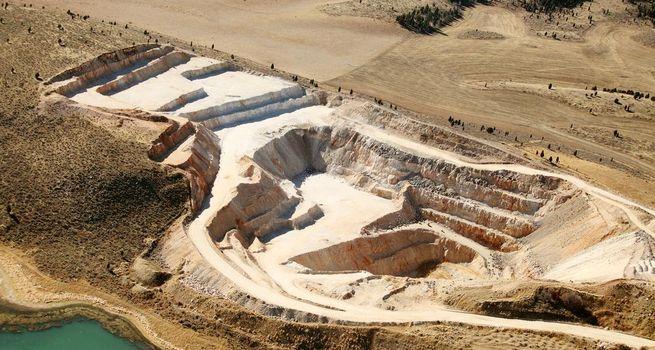
Namib Minerals is a gold-focused mining and development company with its operational center of gravity in southern Africa, where Zimbabwe in particular has long been associated with substantial gold endowment. The company's identity is built around hard-rock gold assets that combine historical mining heritage with the potential to be modernized, expanded or restarted. In practical terms, that means NAMM is part operator and part developer, seeking to convert known mineralized systems into steady ounces while evaluating ways to lengthen mine life and lift throughput. Companies in this mold typically control processing infrastructure, underground or open-pit resources, and exploration ground that surrounds existing workings. The investment character of such a business is distinct from a pure explorer, because cash flow potential and resource definition can coexist.
For NAMM, the overarching narrative is about taking established gold districts and applying capital, technical discipline and operational focus to unlock value that may have been underexploited in prior cycles.
Why the Stock Is in Focus
Namib Minerals has drawn attention for reasons that are partly company-specific and partly sector-wide. On the sector side, gold has been trading at historically elevated levels, and that environment tends to pull capital toward smaller producers and developers that offer outsized leverage to the metal. When bullion rises, the percentage uplift to a marginal-cost producer's potential margin can be dramatic, and the market often rewards that optionality aggressively. On the company side, NAMM's profile as an African gold play with restart and growth potential gives it a narrative that speculators find compelling: the prospect of rising output meeting rising prices. The "strong-buy" framing that sometimes circulates around such names reflects momentum and expectation rather than guaranteed outcomes. It is worth stressing that focus and enthusiasm are not the same as proven results.
Still, the combination of a clear gold theme, an emerging-market growth story and a high-beta share structure explains why NAMM repeatedly surfaces in speculative conversations.
Gold, Silver and Precious-Metals Market Backdrop
The broader precious-metals backdrop is the single most important external force acting on Namib Minerals. Gold has benefited from a confluence of supportive themes: persistent macro uncertainty, central-bank buying, currency-debasement concerns and demand for assets perceived as stores of value. Silver, often described as gold's more volatile cousin, carries an additional industrial dimension through electronics and solar demand, and its swings can amplify sentiment across the whole complex. For a gold-centric producer like NAMM, the practical takeaway is straightforward: the prevailing metal price sets the ceiling and floor on potential profitability, while the company's cost base determines how much of that price converts into margin. When prices are firm, even modest operational progress can translate into meaningful cash generation. Conversely, a sharp pullback in bullion would compress margins quickly. Investors watching the sector also track real interest rates, the U.S.
dollar and physical demand trends, since these variables tend to drive gold's direction more than any single mining headline.
Key Catalysts Driving Investor Interest
Several catalyst types tend to move a speculative gold name like Namib Minerals. The first is operational: any evidence that production is ramping, that recoveries are improving, or that a dormant asset is being restarted can re-rate the shares. The second is resource-related: drilling results, resource or reserve updates, and mine-life extensions all feed the market's sense of how many ounces ultimately sit behind the company. The third is corporate and financial: securing funding, refinancing, partnerships, offtake arrangements or strategic transactions can each shift the risk profile materially. A fourth catalyst is simply the gold price itself, since macro moves can lift NAMM independent of any company news. Finally, broader visibility events, index inclusion, expanded coverage or rising trading liquidity, can attract new buyers.
None of these catalysts is guaranteed to occur or to be positive, but they form the menu of developments that speculators monitor closely when deciding whether the NAMM story is gaining or losing momentum.
Financial and Valuation Considerations
Valuing a smaller gold company such as Namib Minerals requires care, because the usual blue-chip yardsticks can mislead. Rather than fixating on a single earnings multiple, analysts often look at metrics tailored to mining: enterprise value relative to resources and reserves, projected all-in sustaining costs, and the net present value of producing assets under various gold-price scenarios. Cash flow and balance-sheet strength matter enormously, since development and restart activity is capital intensive and any reliance on external financing introduces dilution or debt risk. Investors also weigh the gap between a company's current market capitalization and the theoretical value of its in-ground ounces, recognizing that the discount reflects execution and jurisdiction risk. For NAMM, the qualitative point is that valuation hinges on the credibility of its production trajectory and cost profile.
A name perceived to be converting resources into low-cost ounces can command a premium; one viewed as capital-hungry and uncertain typically trades at a steep discount, regardless of how attractive the underlying geology may appear.
Growth Outlook and Project Pipeline
The growth story behind Namib Minerals rests on the idea that its asset base contains more potential than current activity reflects. In southern African gold districts, that potential often takes several forms: extending known orebodies at depth, reprocessing or expanding existing operations, and bringing previously idled mines back into service. A credible pipeline would blend near-term production with longer-dated development optionality, allowing the company to fund growth partly from internal cash flow rather than relying entirely on markets. Exploration upside is a recurring theme, because mature mining regions frequently host underexplored extensions and satellite deposits. For NAMM, the key question investors ask is whether management can sequence these opportunities sensibly, prioritizing the highest-return, lowest-risk ounces first, while maintaining financial flexibility. A well-articulated, adequately funded pipeline can sustain a re-rating over time, whereas an overly ambitious plan without matching capital can strain the balance sheet.
The outcome will ultimately be judged on delivered ounces and demonstrated cost control, not on aspiration alone.
Major Risks Investors Should Watch
The risks attached to Namib Minerals are substantial and deserve equal weight to the opportunity. Jurisdiction risk is prominent: operating in southern Africa, and Zimbabwe specifically, exposes the company to political, regulatory, currency and repatriation considerations that can change with little warning. Operational risk is ever-present in mining, where grade variability, equipment issues, power supply and labor matters can disrupt output. Financing risk looms large for capital-intensive restart and expansion plans, raising the possibility of dilution. Commodity risk is fundamental: a meaningful drop in gold prices would pressure margins quickly for any producer not operating at the low end of the cost curve. Liquidity and volatility risk affect smaller stocks, where thin trading can exaggerate price moves in both directions. Finally, execution risk, the chance that timelines slip or costs overrun, is the thread connecting many of these concerns.
For a speculative name like NAMM, these risks are not peripheral; they are central to why the shares can move so sharply.
What Could Drive the Stock Next
Looking ahead, the near-term direction of Namib Minerals will likely be shaped by a handful of observable developments. Production and operational updates that show ounces flowing and costs contained would support a constructive reading, while delays or cost inflation would do the opposite. News on financing and balance-sheet management could prove pivotal, since the market's tolerance for dilution often determines how growth plans are received. Drilling and resource updates that expand the ounce count would feed the longer-term story, and any strategic moves, partnerships, offtakes or corporate activity, could reset the risk profile. Overlaying all of this is the gold price itself, which can dominate the share's behavior on any given day regardless of company specifics.
Investors tracking NAMM tend to watch the interplay between these company milestones and the macro tape, recognizing that a speculative gold stock can be moved as much by sentiment shifts in the broader complex as by anything happening at the asset level.
Conclusion
Namib Minerals captures the essence of a speculative gold story: a southern African asset base with production and growth potential, riding the tailwind of a strong precious-metals market. The case for attention is clear, given the leverage smaller producers carry to bullion and the optionality embedded in restart and expansion plans. Equally clear are the risks, jurisdiction, financing, operational execution and commodity-price swings, that make NAMM a name where outcomes can diverge sharply from expectations. For anyone studying the stock, the sensible approach is to track the concrete milestones that will validate or undermine the thesis, while keeping the macro gold backdrop firmly in view. NAMM is neither a guaranteed winner nor an automatic avoid; it is a high-variance gold play whose ultimate value will be settled by execution.
As always, independent research and a clear understanding of one's own risk tolerance should anchor any decision related to a name like NAMM.

 Nov 02, 2026
 Please wait processing your request...