
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Osisko Gold Royalties operates a royalty and streaming model anchored by the Canadian Malartic royalty in Quebec.
• The business earns revenue from mines it does not operate, reducing direct operating and capital cost exposure.
• A diversified portfolio of royalties and streams spreads risk across multiple assets and jurisdictions.
• The model offers leverage to gold prices alongside inflation-resistant margins.
In the gold sector, not every company that profits from rising metal prices actually digs gold out of the ground. Royalty and streaming companies occupy a distinctive niche, financing mines in exchange for the right to a percentage of future production or revenue, and in doing so, they capture gold-price upside while sidestepping much of the operational grind of mining. Osisko Gold Royalties Ltd. (NYSE:OR) is a prominent example of this model, built around a cornerstone royalty on one of Canada's largest gold mines. For investors who want exposure to gold but are wary of the cost overruns, labor issues and capital intensity that plague operators, the royalty model holds obvious appeal. It is often described as a lower-risk, more resilient way to participate in the precious-metals cycle. Yet "safer" does not mean risk-free.
Company Overview
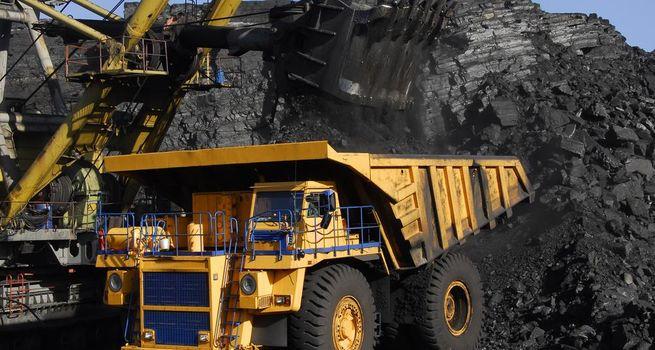
Osisko Gold Royalties is a precious-metals royalty and streaming company headquartered in Canada. Rather than operating mines, it provides capital to mining companies and, in return, holds royalties (a right to a percentage of revenue or production) or streams (a right to purchase a portion of metal at a predetermined low price). Its cornerstone asset is a royalty on the Canadian Malartic mine in Quebec, one of the largest gold operations in Canada, which provides a substantial and long-life revenue base. Around this anchor, the company has assembled a diversified portfolio of royalties and streams spanning numerous assets at various stages, from producing mines to development and exploration projects, across multiple jurisdictions. This structure allows Osisko Gold Royalties to benefit from production and exploration success at mines it does not operate, while avoiding the direct burden of operating costs, sustaining capital and development expenditure.
The result is a business model with high margins and meaningful leverage to gold, underpinned by a marquee Canadian asset.
Why the Stock Is in Focus
Osisko Gold Royalties is in focus because the royalty and streaming model has proven attractive across market cycles, and especially so when gold prices are elevated. The model's appeal rests on several structural advantages. Because royalty companies do not bear operating or sustaining capital costs, their margins tend to be high and relatively resilient to cost inflation, a meaningful benefit when mining costs are rising industry-wide. They also enjoy diversification: a portfolio of royalties spreads risk across many assets, so a problem at any single mine has a limited effect on the whole. The cornerstone Canadian Malartic royalty gives Osisko Gold Royalties a stable, long-life foundation in a top-tier jurisdiction. Investors seeking gold exposure with a smoother risk profile than operators often gravitate toward royalty names for these reasons.
As gold trades at high levels, the leverage embedded in royalty revenue, combined with the model's defensive characteristics, keeps Osisko Gold Royalties in the spotlight.
Gold, Silver and Precious-Metals Market Backdrop
The precious-metals backdrop has been favorable, with gold supported by macroeconomic uncertainty, geopolitical risk and sustained central-bank buying. Gold's traditional roles as an inflation hedge, store of value and safe haven have kept demand firm. For a royalty company, this environment is especially advantageous. Royalty revenue rises with the gold price, but because the company's costs are largely fixed, much of any price increase flows through to margins, giving royalty firms strong operating leverage to gold without the cost inflation that erodes operators' returns. This inflation resistance is a defining feature of the model: when mining costs climb, operators' margins can be squeezed, but royalty holders typically continue to receive their percentage regardless. Silver and other precious metals tend to move with gold, and royalty portfolios often include exposure to these and to byproduct metals.
For Osisko Gold Royalties, a strong and stable precious-metals market amplifies revenue while the model's structure preserves the resulting margins, reinforcing its appeal during buoyant gold cycles.
Key Catalysts Driving Investor Interest
Several catalysts shape interest in Osisko Gold Royalties. The performance of the cornerstone Canadian Malartic royalty is foremost, since this asset underpins a large share of revenue; production growth, mine-life extension and exploration success there directly benefit the company. Portfolio growth is a second key catalyst: royalty companies expand by acquiring new royalties and streams or financing new projects, and accretive deals can meaningfully increase future cash flow. Production ramp-ups and developments coming online across the existing portfolio add new revenue streams over time. Exploration success at the underlying mines can extend the life and scale of royalties at no additional cost to the company. Capital-allocation decisions, balancing new acquisitions, balance-sheet strength and shareholder returns such as dividends, also influence sentiment, since royalty companies are often valued partly for their income characteristics.
Because the model carries low incremental costs, growth in royalty revenue tends to translate efficiently into cash flow, making each of these catalysts potentially significant for the company's trajectory.
Financial and Valuation Considerations
Royalty and streaming companies are typically valued differently from operators, often commanding premium multiples that reflect their high margins, low capital requirements, diversification and resilience to cost inflation. Common analytical tools include price-to-net-asset-value, price-to-cash-flow and dividend yield, alongside an assessment of the quality and longevity of the underlying assets. A central consideration for Osisko Gold Royalties is the durability and growth of its revenue, anchored by the long-life Canadian Malartic royalty and supplemented by a diversified portfolio. Because royalty companies bear minimal operating and capital costs, a high proportion of revenue converts to cash flow, supporting both reinvestment and shareholder returns. The premium valuation the market often assigns to royalty names means expectations are embedded in the price, so the pace and quality of portfolio growth matter. These are qualitative observations; precise multiples and figures move continuously with the gold price and quarterly results.
The analytical essence is that the model's structural advantages tend to justify a richer valuation, provided the company keeps growing its high-margin revenue base.
Growth Outlook and Project Pipeline
Osisko Gold Royalties grows along two main avenues. The first is organic: the existing portfolio matures as development and exploration-stage assets advance toward and into production, adding new revenue streams over time without further investment by the company. Exploration success at underlying mines can expand and extend royalties, increasing their value at no incremental cost. The second avenue is acquisitive: royalty companies actively deploy capital to acquire new royalties and streams or to finance mining projects, and a disciplined deal pipeline is central to long-term growth. The cornerstone Canadian Malartic royalty provides a stable base, while the diversified portfolio offers numerous embedded growth options as assets are developed and expanded. The strategic challenge is to grow the portfolio accretively, adding high-quality, long-life royalties at attractive prices, rather than overpaying in competitive markets.
Because the incremental cost of adding a royalty is low once acquired, successful portfolio growth compounds efficiently into rising cash flow, underpinning the company's longer-term outlook.
Major Risks Investors Should Watch
Although the royalty model reduces certain risks, Osisko Gold Royalties is not risk-free. Commodity-price risk remains: royalty revenue rises and falls with the gold price, so a sustained decline would reduce cash flow. Counterparty and operator risk is significant, because the company depends on third-party operators to run the underlying mines well; operational problems, closures or financial distress at a key mine, particularly the cornerstone Canadian Malartic, would affect royalty income, and the company has limited control over those operations. Concentration risk attaches to reliance on any single major asset for a large share of revenue. Acquisition risk is relevant, as growth depends on sourcing and pricing deals well; overpaying or misjudging asset quality can erode value. Jurisdictional risk varies across the portfolio.
There is also valuation risk: royalty stocks often trade at premium multiples, so disappointments in growth or asset performance could lead to de-rating. Finally, broader macro and equity-market sentiment can move the shares regardless of company-specific factors.
What Could Drive the Stock Next
The trajectory of Osisko Gold Royalties will be shaped by both its portfolio and the gold market. Continued strong performance and mine-life extension at the Canadian Malartic royalty would reinforce the stable foundation of the business. Accretive acquisitions and the addition of high-quality royalties and streams would expand future cash flow and support a growth narrative. Production ramp-ups across the existing portfolio, and exploration success at underlying mines, would add and extend revenue streams over time. On the macro side, the gold price is a powerful driver: continued strength flows efficiently through to royalty margins, while weakness would pressure revenue. Capital-allocation decisions, balancing growth, balance-sheet strength and shareholder returns, will influence how income-oriented investors view the stock. Conversely, problems at a key underlying mine, poorly priced acquisitions or a sustained gold decline could weigh on sentiment.
For Osisko Gold Royalties, the combination of portfolio quality, disciplined growth and a supportive gold market is what will drive the shares next.
Conclusion
Osisko Gold Royalties offers a distinctive way to participate in the gold market. By financing mines rather than operating them, the company captures the upside of rising gold prices while sidestepping much of the cost inflation, capital intensity and operational risk that weigh on producers, a structure that delivers high margins, diversification and inflation-resistant cash flows. Anchored by the long-life Canadian Malartic royalty and supported by a diversified portfolio, it embodies the resilience that makes royalty companies appealing across market cycles. Yet the model is not without risk: it depends on the performance of third-party operators, concentration in key assets and the discipline to grow accretively, and its premium valuation leaves little room for disappointment. For those studying lower-risk routes into gold, Osisko Gold Royalties provides a clear example of how the royalty model balances structural strength against the risks that remain.

 Nov 02, 2026
 Please wait processing your request...