
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Gold and Copper Production Both Rise: Barrick reported Q1 2026 gold production up 4% and copper production up 11% year-over-year, reflecting broad operational strength.
• Costs Decline as Output Grows: All-in sustaining costs fell 4% during the quarter even as production volumes increased, indicating improved operational efficiency.
• Net Earnings Surge 238%: The combination of higher output and lower costs drove net earnings up 238% to $1.6 billion, supporting a $57 average analyst price target.
Barrick Mining (NYSE: B) continues to draw investor attention following a standout Q1 2026 operational performance that has reinforced confidence in the company's diversified mining portfolio, even as today's broader price action is primarily driven by gold's renewed strength above the $4,000/oz level. The underlying quarterly metrics, however, provide important context for why analysts remain constructive on the stock's longer-term trajectory.
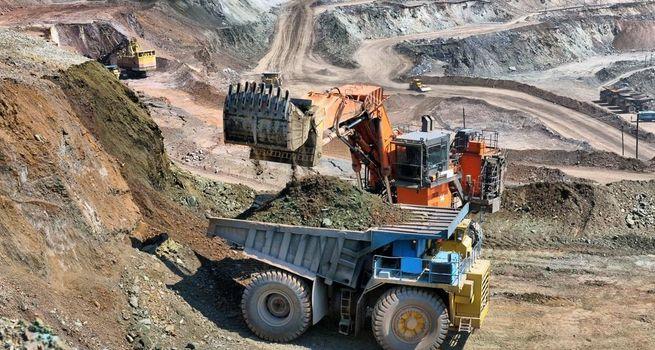
The company's first-quarter results showed gold production increasing 4% year-over-year, alongside an even more pronounced 11% increase in copper production. That dual-metal growth profile distinguishes Barrick from more narrowly focused gold-only producers, providing the company with diversified exposure to both precious metals demand and the structural growth story increasingly associated with copper, given its critical role in electrification and AI infrastructure applications.
Perhaps even more notable than the production growth itself was the simultaneous improvement in cost efficiency. All-in sustaining costs, a comprehensive measure of total production costs used widely across the mining industry, declined 4% during the quarter even as output volumes increased. Achieving cost reductions alongside production growth reflects meaningful operational discipline and suggests Barrick's mining operations are becoming more efficient rather than simply benefiting from higher commodity prices alone.
The combined effect of higher production, lower costs, and a generally favorable pricing environment for both gold and copper translated into dramatic bottom-line growth. Barrick reported net earnings surging 238% to $1.6 billion for the quarter, a figure that substantially outpaced the prior-year comparison and underscored the significant operating leverage embedded in the company's business model during periods of favorable commodity pricing.
That combination of operational strength and financial performance continues to support a constructive analyst outlook, with the average 12-month price target for Barrick sitting near $57, implying meaningful upside from current levels. Investors will likely continue monitoring whether the company can sustain this trajectory of simultaneous production growth and cost discipline in upcoming quarterly reports.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Stock prices, analyst price targets, and market data referenced are subject to change and should be independently verified. Readers should conduct their own research or consult a licensed financial advisor before making any investment decisions.

 Nov 06, 2026
 Please wait processing your request...