
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity

Key Highlights
- Industrials Remain the Strongest Market Leader: XLI continues to hold a firm position within the Leading quadrant, maintaining superior relative strength despite some moderation in momentum.
- Consumer Discretionary Emerges as a Leadership Candidate: XLY remains the only sector in the Improving quadrant, signalling strengthening momentum and the potential for a future move into Leading.
- Technology Continues Recovering: XLK remains in the Weakening quadrant but has improved significantly in recent periods, suggesting the sector may be preparing to re-establish market leadership.
- Materials Enter Weakening: XLB has rotated from Leading into Weakening, indicating that relative momentum is deteriorating despite maintaining above-average relative strength.
- Energy Remains the Weakest Sector: XLE continues to occupy the deepest position within the Lagging quadrant, reflecting persistent relative underperformance versus the broader market.
The US sector rotation profile on June 30, 2026, highlights a market undergoing an important transition. While Industrials, Financials, Utilities, and Consumer Staples continue to hold leadership positions, momentum is increasingly shifting toward growth-oriented sectors such as Technology and Consumer Discretionary. Meanwhile, Materials has begun losing momentum, and Energy remains the market's weakest area.
The latest Relative Rotation Graph suggests investors are gradually rotating away from defensive leadership and toward sectors that could benefit from improving economic conditions and renewed enthusiasm for growth opportunities. This evolving rotational pattern may broaden market leadership in the weeks ahead. This article follows the structure and style of the reference report.
US Sector Momentum Summary
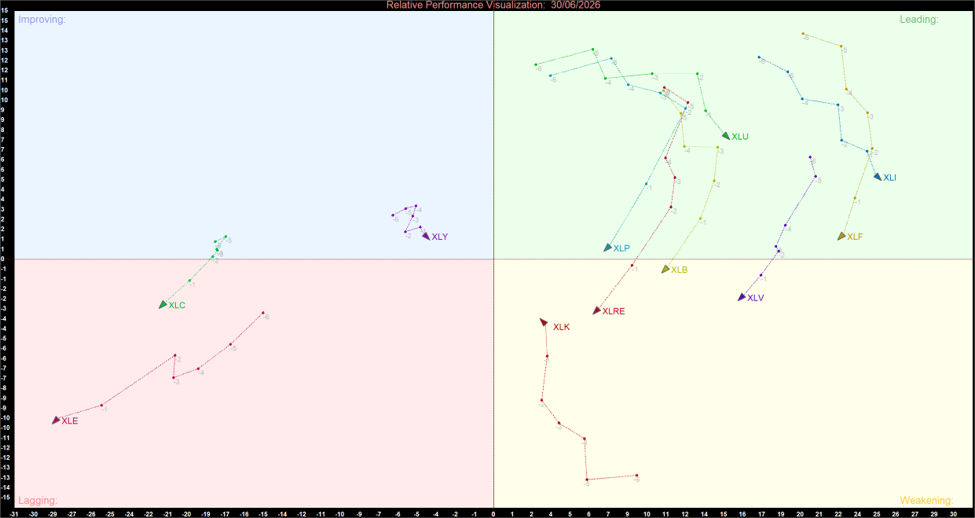
US Sector Relative Momentum Chart (at the closing price of 30/06/2026). Powered by: amibroker.com
The Leading Quadrant (The Market Leaders)
- Industrials (XLI) remains one of the strongest sectors on the Relative Rotation Graph. Although relative momentum has eased slightly from previous highs, the sector continues to demonstrate superior relative strength as investors maintain confidence in economic expansion, infrastructure spending, and industrial activity.
- Financials (XLF) continues to occupy the Leading quadrant. Despite modest weakness in daily performance, the sector maintains positive relative strength, reflecting stable expectations for banking profitability and economic resilience.
- Utilities (XLU) remains within the Leading quadrant but is showing signs of slowing momentum. The sector continues to benefit from its defensive characteristics and stable earnings profile; however, recent tail direction suggests leadership may be becoming less dominant.
- Consumer Staples (XLP) also remains positioned in the Leading quadrant. The sector continues to attract investors seeking earnings stability and reliable cash flows, although momentum has moderated compared with earlier periods.
The Improving Quadrant (The Emerging Leadership Candidates)
- Consumer Discretionary (XLY) is currently the only sector firmly positioned within the Improving quadrant. Its north-easterly trajectory reflects strengthening relative momentum and growing investor confidence in consumer spending trends. If current momentum persists, XLY may become the next sector to rotate into Leading territory.
- The sector's improving position is particularly noteworthy given the market's increasing preference for cyclical and growth-oriented opportunities.
The Weakening Quadrant (Losing Momentum)
- Technology (XLK) remains within the Weakening quadrant despite delivering the strongest daily performance among all sectors. The sector's recent upward trajectory suggests momentum is recovering, and continued outperformance could support a rotation back toward Leading in coming weeks.
- Materials (XLB) has recently entered the Weakening quadrant from Leading. Although relative strength remains positive, momentum has deteriorated noticeably. This transition indicates investors are becoming more selective toward commodity-related and industrial materials companies after a period of strong outperformance.
- Health Care (XLV) remains in Weakening but has shown encouraging improvement in recent sessions. The sector's trajectory suggests momentum is stabilising and could eventually support a return to leadership if the trend continues.
- Real Estate (XLRE) continues to occupy the Weakening quadrant. While relative strength remains above average, momentum has softened significantly as investors rotate capital toward sectors offering stronger growth prospects.
The Lagging Quadrant (Structural Underperformers)
- Energy (XLE) remains the weakest sector on the Relative Rotation Graph. Despite minor improvements in momentum, the sector continues to display both weak relative strength and weak momentum compared with the broader market.
- Communication Services (XLC) remains within the Lagging quadrant but is showing signs of recovery. Its trajectory has been moving toward the Improving quadrant, suggesting selling pressure may be easing and relative performance could improve over time.
- The continued presence of Energy and Communication Services within Lagging reflects the market's preference for sectors exhibiting stronger relative momentum and more favourable earnings expectations.
Strategic Summary
The latest Relative Rotation Graph continues to favour Industrials (XLI), Financials (XLF), Utilities (XLU), and Consumer Staples (XLP), all of which remain positioned within the Leading quadrant and continue to exhibit positive relative strength.
Meanwhile, Consumer Discretionary (XLY) remains the most compelling emerging leadership candidate within the Improving quadrant, while Technology (XLK) is showing encouraging signs of recovery despite remaining in Weakening. The rotation of Materials (XLB) into Weakening represents one of the most significant changes in the current sector landscape, highlighting a loss of momentum among previous leaders.
On the other hand, Energy (XLE) and Communication Services (XLC) continue to lag the broader market, although Communication Services is beginning to display improving characteristics. Overall, sector rotation suggests market leadership is gradually shifting away from defensive sectors and toward cyclical and growth-oriented industries. If this trend continues, Technology and Consumer Discretionary could become increasingly influential drivers of market performance during the coming weeks.

 Nov 16, 2026
 Please wait processing your request...