
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
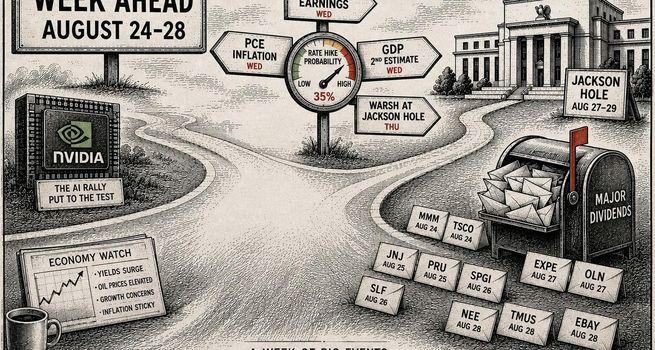
Global bond yields surged this week, sending the 30-year Treasury Yield to its highest level since 2007 and pulling the S&P 500 about 2% below its record high, with the Philadelphia SE Semiconductor index down roughly 5% for the week. The Treasury Department's move to double Buybacks for long-dated Debt offered only brief relief before yields rebounded Thursday, sharpening focus on the Federal Reserve's Jackson Hole symposium running August 27-29.
Chair Kevin Warsh delivers his keynote in what will be his first appearance at the event since taking office, and investors are looking for any signal on how he intends to articulate a durable policy framework after having abandoned traditional forward guidance. Nvidia reports second-quarter results Wednesday in what has become the single most consequential Earnings event for the AI trade, given the company's role financing more than $500 billion in AI infrastructure buildout commitments alongside six major financial institutions. July PCE Inflation and the second Q2 GDP estimate arrive Wednesday as well, giving markets an updated growth and inflation picture just ahead of Warsh's Thursday keynote.
Monday, August 24
Earnings
Palo Alto Networks (NASDAQ:PANW) reports in the afternoon, opening the week with a Cybersecurity and enterprise security spending read. Its results will be watched for evidence of whether AI-driven threat detection Demand is translating into sustained platform Revenue growth, providing an early signal ahead of the more consequential technology earnings later in the week.
Economic Data
No major data releases are scheduled Monday.
Tuesday, August 25
Earnings
Intuit (NASDAQ:INTU) reports in the afternoon, providing a small Business financial software and tax services read on enterprise spending health heading into the fiscal year-end reporting cycle.
Economic Data
The S&P Case-Shiller Home Price Index for June, prior at 0.9%, opens Tuesday's data calendar at 9:00 am ET. New home sales for July, prior at 628,000, and the Conference Board Consumer Confidence Index for August, prior at 90.8, round out the day. Consumer confidence will be watched closely for any evidence that surging Treasury yields and elevated borrowing costs are beginning to weigh on household sentiment ahead of the more consequential data releases Wednesday.
Wednesday, August 26
Earnings
Nvidia (NASDAQ:NVDA) reports in the afternoon as the week's single most consequential event and the clearest bellwether for the AI infrastructure trade. Its data centre GPU revenue and forward guidance will be scrutinised for evidence that demand underpinning the AI ecosystem, spanning chipmakers to the companies financing data centre expansion, remains intact despite rising bond yields pressuring the cost of that capital. Given Nvidia's central role in over $500 billion of announced AI infrastructure financing, any softening in guidance would carry implications well beyond the semiconductor sector.
CrowdStrike Holdings (NASDAQ:CRWD) and Salesforce (NYSE:CRM) also report Wednesday afternoon, extending the enterprise software and cybersecurity read alongside Nvidia's results. Synopsys (NASDAQ:SNPS) rounds out Wednesday's earnings with an electronic design automation software read that functions as a leading indicator of semiconductor design complexity investment.
Economic Data
Wednesday carries the week's heaviest data load. Durable goods orders for July, prior at -4.6% and forecast at 0.7%, land at 8:30 am ET alongside the second estimate of Q2 GDP, prior at 1.5%. Personal Income for July, forecast at 0.3%, and personal spending, forecast at 0.2%, arrive simultaneously. July PCE prices are forecast at 0.1% month-on-month, with core PCE forecast at 0.2% month-on-month and 3.3% year-on-year. The PCE release is the Fed's preferred inflation gauge and arrives just one day before Warsh's Jackson Hole keynote, meaning any upside surprise would materially complicate his messaging task and could shift the September rate hike probability, currently priced at 35%, meaningfully higher.
Thursday, August 27
Earnings
Autodesk (NASDAQ:ADSK) reports in the afternoon, providing a software spending read across construction, manufacturing, and media sectors, two of which are directly exposed to elevated Interest Rate sensitivity.
Economic Data
Weekly jobless claims for the week ending August 22 provide the labour market read. The advance U.S. trade balance in goods for July, prior at -$101.6 billion, and wholesale inventories, prior at 0.3%, round out the morning's releases. The Kansas City Fed Manufacturing Survey for August, prior at 17, closes Thursday's data calendar. Separately, the annual revision to nonfarm payrolls through March 2026 is released this week, providing an updated structural read on labour market trends that could reshape how markets interpret recent employment reports.
Federal Reserve
Federal Reserve Chair Kevin Warsh delivers the keynote address at the Jackson Hole Economic Policy Symposium, hosted by the Federal Reserve Bank of Kansas City. This is Warsh's first Jackson Hole appearance since taking office in May and is widely viewed as his most significant opportunity yet to articulate a durable policy framework after having stepped back from traditional forward guidance following the July meeting. Investors will watch for whether he reinforces a data-dependent posture or offers more concrete signals on the path of rates, particularly given that Treasury yields have surged this week despite the Treasury Department's Bond Market intervention. Markets are currently pricing a 35% probability of a September rate hike, rising to 66% by December, and any shift in tone from Warsh could move both figures materially in either direction.
Friday, August 28
Economic Data
The Chicago Business Barometer PMI for August, prior at 67.6, and the final University of Michigan Consumer Sentiment reading for August, prior at 65.2, close the week. Both releases will be read in the immediate aftermath of Warsh's Thursday keynote, providing the first market-based data points on how businesses and consumers are processing his Jackson Hole messaging alongside Wednesday's PCE inflation print.
Geopolitical Backdrop
Elevated energy prices, increasing Deficit spending, and soaring corporate Credit issuance remain the structural backdrop pressuring long-term sovereign yields this week. The 30-year Treasury yield's climb to its highest level since 2007 reflects a confluence of factors beyond the Iran conflict alone, including concerns about the sustainability of federal borrowing at a moment when corporate credit markets are also absorbing record issuance tied to AI infrastructure financing. The Treasury Department's decision to double buybacks for long-dated debt was an explicit attempt to calm this dynamic, but the rebound in yields on Thursday suggests the intervention provided only temporary relief. This yield backdrop is the single most important variable shaping how markets will interpret both Nvidia's earnings and Warsh's keynote, since rising borrowing costs directly threaten the Economics of the AI infrastructure buildout that Nvidia's results will be judged against.
The Week in Context
Two events will define whether the AI-driven rally can withstand the current uncertainty over growth and interest rates. Nvidia's Wednesday results will test whether demand for AI infrastructure remains robust enough to justify continued Capital deployment at current borrowing costs, with the company's role in financing platforms targeting more than $500 billion in data centre buildout making its guidance uniquely consequential. Warsh's Thursday keynote will then determine whether the Fed offers markets a coherent framework to anchor expectations around, or whether his continued departure from forward guidance leaves Treasury yields as volatile as they have been this week. A strong Nvidia print paired with a framework-clarifying Warsh speech would represent the most powerful combination of catalysts available to the market. Either falling short would test how much of the year's gains have been built on assumptions that are now being directly challenged by the bond market.

 Nov 20, 2026


 Please wait processing your request...