The Offer
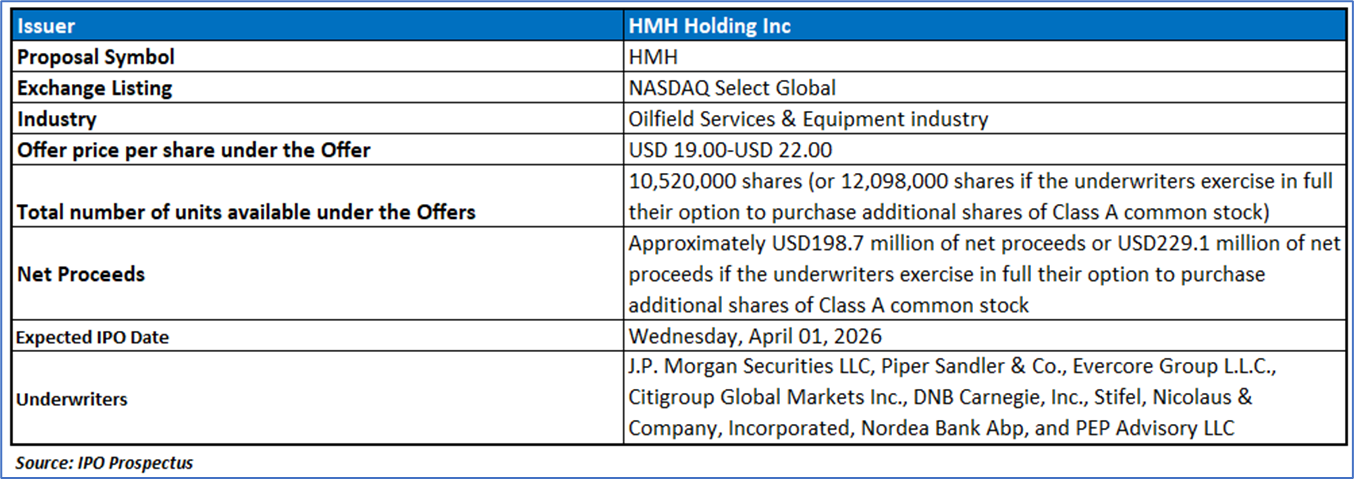
Company Overview
HMH Holding Inc. (HMH) is a global provider of highly engineered, mission-critical equipment and services for the oil and gas drilling industry, serving both offshore and onshore markets through an integrated portfolio spanning equipment manufacturing, project delivery, aftermarket services, and spare parts. The company derives a significant portion of its revenue from recurring aftermarket services, supported by a large installed base—predominantly in the offshore segment, which demands advanced, regulated, and technically sophisticated solutions. Leveraging its asset-light OEM/CEM operating model, HMH combines engineering expertise, digital solutions, and lifecycle service capabilities to enhance operational efficiency, safety, and longevity of drilling assets. With a presence across multiple geographies and a diversified customer base including drilling contractors, operators, and equipment manufacturers, the company is also expanding into adjacent sectors such as mining while maintaining a strong focus on safety, operational excellence, and capital-efficient growth.
Key Highlights
Primary Offering:
10,520,000 shares (or 12,098,000 shares if the underwriters exercise in full their option to purchase additional shares of Class A common stock).
Use of proceeds:
- Use of Proceeds from Offering: HMH Holding Inc. expects to generate net proceeds of approximately USD 198.7 million from the offering (based on the midpoint pricing), which may increase to USD 229.1 million if the underwriters fully exercise their option to purchase additional shares. A portion of these proceeds, amounting to USD 40.5 million, is designated toward funding the cash consideration for the acquisition of equity interests from Baker Hughes and Akastor as part of the corporate reorganization. The remaining proceeds will be contributed to HMH B.V. in exchange for corresponding equity shares, thereby aligning the capital structure with the shares issued in the public offering.
- Debt Repayment and Capital Allocation Strategy: HMH B.V. intends to utilize approximately USD 137.1 million of the contributed proceeds to fully repay outstanding shareholder loans owed to Baker Hughes and Akastor, including accrued interest. These loans, which carried an interest rate of 8.0% per annum and had a balance of USD 143.7 million as of December 31, 2025, are expected to be reduced upon completion of the transaction. In the event of additional proceeds arising from the underwriters’ option, such funds will similarly be deployed toward equity restructuring and proportional buybacks from existing shareholders, further optimizing the company’s balance sheet and ownership structure.
Dividend Policy:
HMH Holding Inc. does not currently intend to declare or pay dividends and expects to retain any future earnings to support business growth and development. The declaration of dividends remains entirely at the discretion of the board of directors and will be contingent upon various factors, including the company’s financial performance, capital requirements, investment opportunities, and prevailing statutory or contractual constraints. Furthermore, existing and anticipated debt agreements impose restrictions on the company’s ability to distribute cash dividends. Accordingly, shareholders are unlikely to receive dividend income in the foreseeable future, and any potential return on investment will primarily depend on capital appreciation in the company’s Class A common stock.
HMH Holding Inc. – Industry Overview
- Global Energy Demand and Hydrocarbon Outlook: Global energy consumption is projected to increase to 541 EJ by 2050, representing a 19% rise from 2024 levels and a 43% increase from 2010, primarily driven by population growth and higher energy intensity in emerging economies. Electricity demand alone is expected to grow from 95 EJ in 2024 to 169 EJ by 2050, while oil demand is anticipated to plateau and natural gas demand to expand through the mid-2030s before gradual decline. Despite energy transition initiatives, hydrocarbons remain essential, reinforcing sustained demand for drilling activity and supporting HMH’s core markets.
- Upstream Investment Cycles and Supply Dynamics: Global upstream capital expenditures declined sharply by 33% to approximately USD 470 billion in 2020, leading to a supply-demand imbalance and an average supply shortfall of 6 million barrels per day between 2021 and 2024, before recovering to a surplus of 1.1 million barrels per day in 2025. Looking ahead, global hydrocarbon production is expected to increase from 172 MM Boe/day in 2025 to 188 MM Boe/day by 2030, reflecting a 9% increase, with offshore production alone projected to grow by 13% (6.1 MM Boe/day). These trends indicate a structurally tightening supply environment that supports renewed investment in drilling infrastructure.
- Offshore Drilling Market Fundamentals: Offshore drilling is emerging as a key growth segment, with offshore-directed spending expected to reach USD 240 billion by 2027, up from USD 140 billion in 2021, alongside the requirement to drill approximately 14,000 additional offshore wells between 2025 and 2028. The floater market has seen constrained supply, with only 173 floaters available as of 2025 following significant retirements, while utilization rates have risen to the low-80% range and day rates for high-spec rigs have increased to approximately USD 434,000 per day. Similarly, the global jack-up fleet stands at 484 rigs, with utilization levels improving to 80%, indicating tightening market conditions and strong demand for equipment upgrades and aftermarket services.
- Critical Minerals Demand and Diversification Opportunity: The critical minerals sector is experiencing accelerated growth, with demand for lithium and cobalt projected to increase by 8% and 14.1% respectively in 2025, driven by electrification and renewable energy adoption. Between 2023 and 2028, total demand for key minerals is expected to rise by 8.0 megatons, including copper (+5.7 MT to 37.7 MT), nickel (+1.1 MT to 4.3 MT), lithium (+1.2 MT to 2.2 MT), and cobalt (+0.1 MT to 0.3 MT). Additionally, battery electric vehicle penetration is forecast to increase from 13% in 2024 to 37% by 2035, significantly increasing mineral intensity requirements. These trends provide a strong growth avenue for HMH’s mining-related equipment portfolio, supporting long-term diversification.
Financial Highlights (Results of Operations) (Expressed in USD)
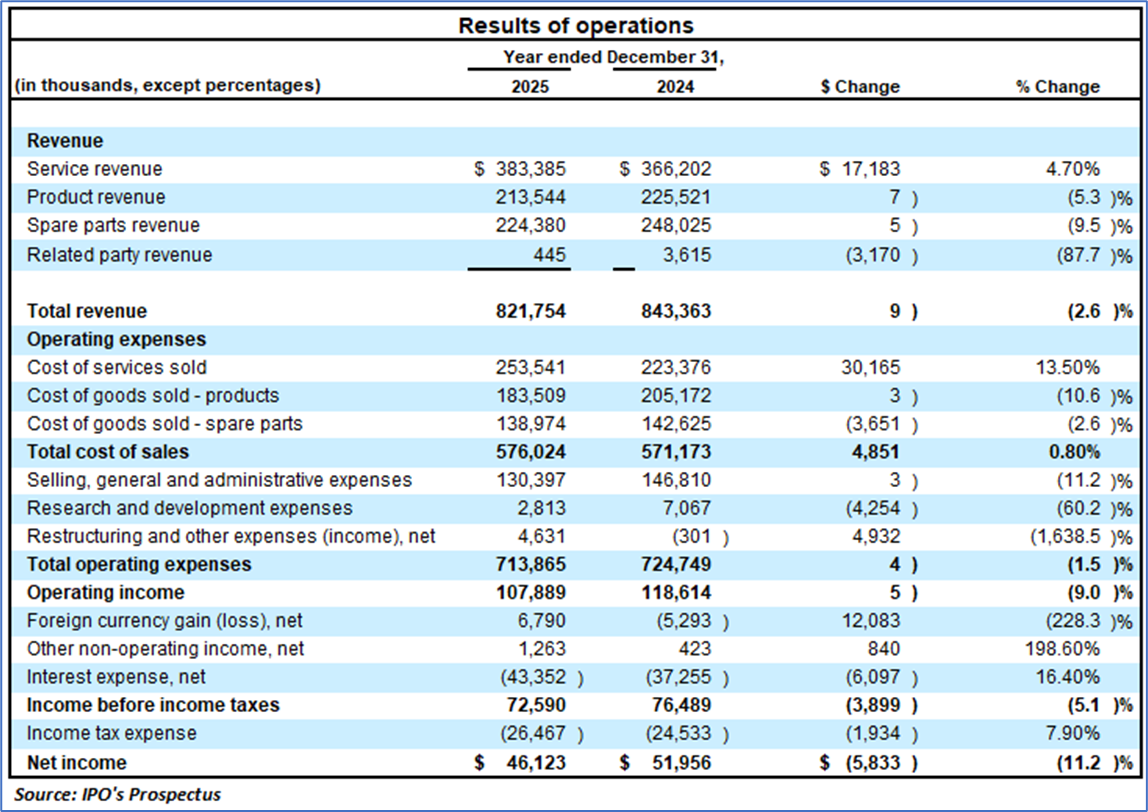
- Profitability and Earnings Performance: HMH reported Adjusted EBITDA of USD 156.2 million for FY2025, reflecting a marginal decline of 4% compared to USD 158.4 million in FY2024, primarily driven by lower net income resulting from subdued revenue amid less favorable market conditions. Overall revenue declined by 2.6% to USD 821.8 million, impacted by reduced contributions from spare parts, product sales, and related party revenue, partially offset by a 4.7% increase in service revenue, which constituted 46.7% of total revenue. Despite revenue pressure, cost optimization initiatives led to a reduction in selling, general and administrative expenses, partially mitigating profitability pressures.
- Cash Flow Generation and Liquidity Position: The company demonstrated a significant improvement in cash flow generation, with Free Cash Flow increasing to USD 72.0 million in FY2025 from USD 16.5 million in FY2024, representing a substantial 1% growth. This improvement was primarily driven by higher operating cash flows, supported by favorable working capital movements, particularly inventory optimization, and reduced capital expenditures. Net cash provided by operating activities increased to USD 88.3 million, while overall cash and cash equivalents nearly doubled to USD 96.6 million, reinforcing HMH’s liquidity position and financial flexibility.
- Capital Efficiency and Returns: Adjusted Return on Capital Employed (ROCE) declined to 9% in FY2025 from 22.0% in FY2024, reflecting the impact of reduced net income and changes in balance sheet structure, including lower current liabilities. Despite this decline, the company continues to maintain strong capital efficiency supported by its asset-light operating model and disciplined capital expenditure strategy. With total capital expenditures of approximately USD 20.0 million in FY2025 and a continued focus on optimizing asset utilization and limiting incremental investments, HMH remains well-positioned to sustain returns while supporting long-term growth.
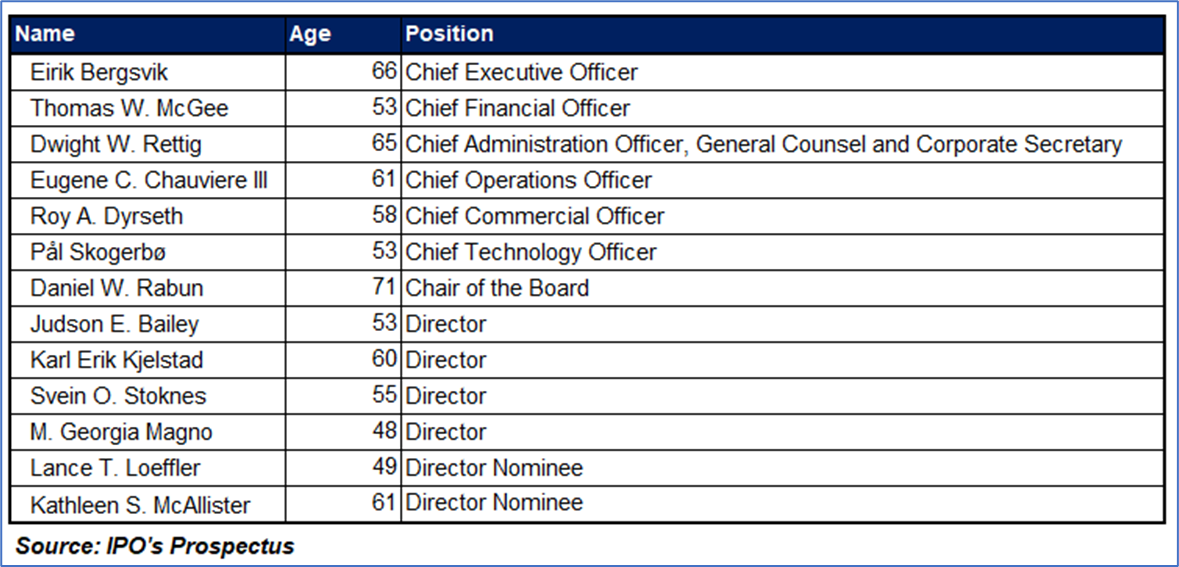
Key Management Highlights
Risk Associated (High)
Investment in the IPO of “HMH” is exposed to a variety of risks such as:
- Cyclicality of Oil & Gas Industry: HMH’s financial performance is highly dependent on upstream oil and gas activity, which is inherently cyclical and influenced by volatile commodity prices, global economic conditions, and capital spending by E&P operators. A downturn in oil prices or reduced exploration and production budgets can directly impact demand for drilling equipment, spare parts, and services, leading to revenue contraction and margin pressure.
- Offshore Market Concentration Risk: A significant portion of HMH’s installed base and revenue is concentrated in the offshore drilling segment, which is more capital-intensive, highly regulated, and sensitive to long-cycle investment decisions. Any delays, cancellations, or reductions in offshore projects, as well as regulatory or environmental constraints, could materially affect equipment demand and aftermarket service revenues.
- Cost Structure and Execution Risks: The company faces risks related to cost inflation, project execution, and operational efficiency, including potential contract write-offs, fluctuating utilization levels, and supply chain disruptions. Additionally, exposure to complex, large-scale projects increases the risk of margin volatility and cost overruns, which may adversely impact profitability.
Conclusion
HMH Holding Inc. operates as a global provider of mission-critical equipment and services for the oil and gas drilling industry, with a strong presence in offshore markets and a growing footprint in adjacent sectors such as mining. The company’s offering is supported by a large installed base and recurring aftermarket services, while its asset-light operating model enables capital-efficient growth. Industry fundamentals remain supported by long-term energy demand, increasing offshore investment, and rising demand for critical minerals; however, the business remains exposed to cyclical oil and gas dynamics. Financially, HMH has demonstrated stable profitability with moderate revenue pressure, alongside a significant improvement in free cash flow and a solid liquidity position, although returns on capital have moderated. The IPO proceeds are primarily intended for corporate restructuring and debt reduction, with limited near-term dividend expectations, and overall investment considerations are balanced by exposure to industry cyclicality, offshore concentration, and execution-related risks.
Hence, given the financial performance of the company, use of proceeds, and associated risks “HMH Holding Inc (HMH)” IPO seems “Neutral" at the IPO price.
Past performance is not a reliable indicator of future performance.

 CA
 NZ
 UK
 AU
 IND

 US

 Please wait processing your request...