Explore 3 Stock Ideas & Industry Insights Download Free Report

mid-cap

Advancing Growth with Skouries Near Commissioning - EGO

Feb 04, 2026 | Team Kalkine
Advancing Growth with Skouries Near Commissioning - EGO
Image source: Shutterstock

  • EGO:NYSE
  • Investment Type
    Mid - Cap
  • Risk Level
  • Action
  • Rec. Price (US$)

Eldorado Gold Corporation

Eldorado Gold Corporation (NYSE: EGO) is a Canada-based gold and base metals producer with mining, development and exploration operations in Turkiye, Canada and Greece. The Company operates four mines: Kisladag, Efemcukuru, Lamaque, and Olympias. 

Key Business and Financial Updates:

  • Operational Delivery Remains Constructive Despite Localised Headwinds: Eldorado Gold reported Q3 2025 gold production of 115,190 ounces, supported by stronger output at the Lamaque Complex following accelerated processing at Ormaque, partially offset by weaker-than-expected performance at Olympias due to ongoing flotation circuit challenges. Gold sales totalled 116,529 ounces at an average realised price of USD 3,527/oz, underscoring a favourable commodity pricing backdrop. Cost performance reflected higher operational intensity, with total cash costs of USD 1,195/oz and AISC of USD 1,679/oz, while total production costs stood at USD 164.1m for the quarter.
  • Financial Results Strengthened by Gold Price Tailwinds and Robust Operating Cash Generation: The quarter delivered revenue of USD 434.7m and operating cash flow from continuing operations of USD 170.2m (USD 5m pre-working capital), reflecting solid cash conversion in a high-price gold environment. Net earnings attributable to shareholders from continuing operations were USD 56.5m (USD 0.28/share), including USD 39.4m of realised derivative losses linked to gold collars. On an adjusted basis, Eldorado produced Adjusted EBITDA of USD 196.3m and Adjusted net earnings of USD 82.3m (USD 0.41/share), with key adjustments including derivative and FX-related losses. The balance sheet remained notably strong, with cash and cash equivalents of USD 1.04bn, supported by strong metal prices and monetisation proceeds (including G Mining Ventures-related transactions), partially offset by increased costs, elevated capex, and share repurchases.
  • Skouries Execution Progressing Into the Final Stretch, With Schedule Intact: Skouries remains a central strategic catalyst, with Eldorado maintaining first concentrate production expectations for end-Q1 2026 and commercial production targeted for mid-2026. Q3 project capital spend totalled USD 137.7m, bringing nine-month spend to USD 338.6m, while project progress stood at 73% complete for Phase 2 construction (86% including Phase 1). Execution highlights included progress across the filtered tailings plant (critical path), primary crusher infrastructure, process plant installations, and accelerating underground development, with the first underground test stope blast successfully executed. The 2025 Skouries capital budget was revised upward to USD 440–470m, reflecting accelerated non-critical work and de-risking, while the total project capital estimate remains unchanged at USD 1.06bn.
  • Guidance Tightened; Capital Allocation Signals Confidence While Growth Capex Pressures FCF: Management tightened 2025 gold production guidance to 470,000–490,000 ounces and revised consolidated cost expectations upward to USD 1,175–1,250/oz (cash costs) and USD 1,600–1,675/oz (AISC), largely driven by record gold prices increasing royalty expense and weaker Olympias by-product contribution. Free cash flow was negative USD 87.4m, primarily due to accelerated growth investment, although FCF excluding Skouries capex was positive at USD 76.9m, highlighting the underlying cash-generation capacity of the operating base. Eldorado also reinforced capital allocation discipline via USD 78.8m of share repurchases during the quarter, alongside leadership updates including the appointment of Christian Milau as President and a board transition with Samantha Espley joining as a director.

Key Company specific risks for OWL:

  • Operational execution risk (mine performance + ramp-ups): Underperformance at key assets (e.g., processing disruptions, lower recoveries, throughput issues) could pressure production volumes, unit costs, and cash generation, especially as multiple sites are undergoing optimisation and development activity.
  • Skouries project delivery risk (schedule / capex / commissioning): Any delay in first concentrate production, cost overruns, or commissioning underperformance at Skouries could weaken near-term earnings visibility and increase funding pressure, given the project’s material contribution to Eldorado’s medium-term growth profile.
  • Commodity price and jurisdiction risk (gold + regulatory/royalty exposure): A pullback in gold prices or adverse changes in taxes/royalties and permitting conditions across operating regions could reduce margins, cash flows, and capital return flexibility, particularly during a heavy investment cycle.

Technical Observation (on the daily chart):
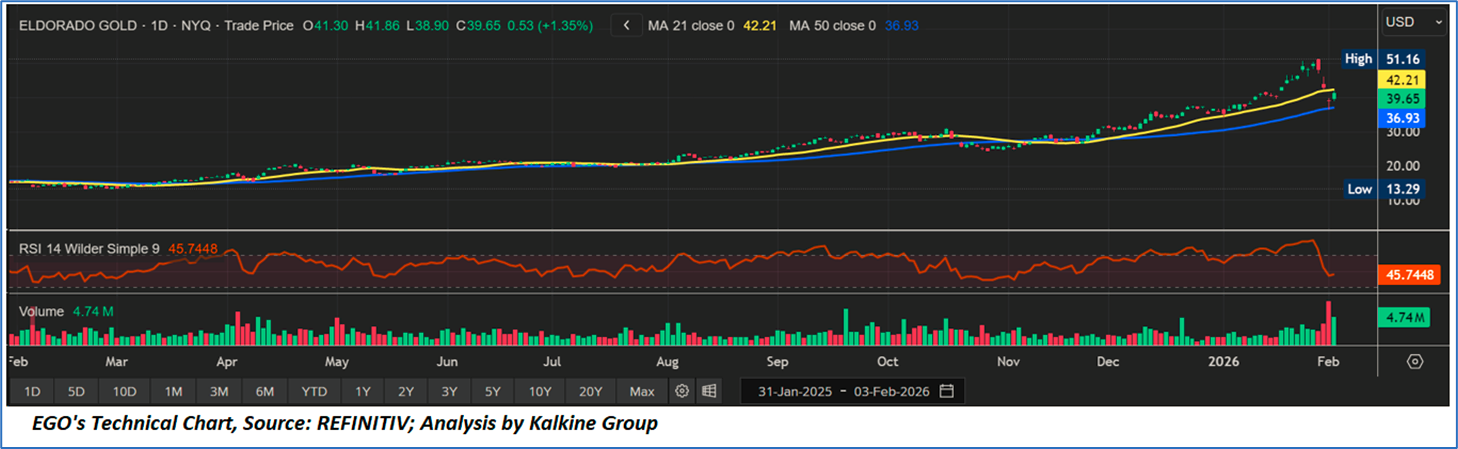
  • Trend & Price Structure: Uptrend Holds: EGO remains in a broader uptrend, with the latest move appearing more like a consolidation after a strong rally rather than a trend breakdown. The stock pulled back from the recent high near USD 51.16 and is now around USD 39.65, indicating near-term volatility but still constructive longer-term structure.
  • Moving Averages: Key Support Remains Intact: The technical setup stays supportive as the moving averages are still rising, with the 21-day MA near USD 42.21 and the 50-day MA near USD 36.93. While price is slightly below the 21-day level, it remains above the 50-day MA, keeping the bullish structure intact so long as the USD 36.9–37.0 support zone holds.
  • Momentum & Volume: RSI Cooling Signals Reset: Momentum has moderated, with RSI around 7, showing a healthy cooling-off from prior stronger conditions. This supports a base-building phase, though a stronger upside move would typically require renewed momentum and price regaining the USD 42+ zone.

Eldorado Gold’s Q3 FY2025 update reflects a resilient operating profile and strengthening strategic visibility, underpinned by solid quarterly production and strong realised gold pricing, while the balance sheet remains notably robust to support ongoing investment. Despite localized headwinds at Olympias, performance at Lamaque and favourable commodity conditions supported healthy revenue and operating cash generation, with adjusted profitability metrics indicating durable underlying earnings capacity even after derivative and FX-related impacts. Importantly, the investment thesis continues to be anchored by Skouries, where execution remains firmly on track with tangible construction and underground milestones achieved, supporting expectations for first concentrate production by end-Q1 2026 and commercial production in mid-2026—thereby establishing a credible pathway to higher production scale and improved quality of cash flows over the medium term. While consolidated cost guidance has been revised upward amid royalty impacts and operational mix, the company’s ability to generate positive free cash flow excluding Skouries capex, alongside continued share repurchases, reinforces management confidence in the asset base and enhances the overall long-term value proposition. 

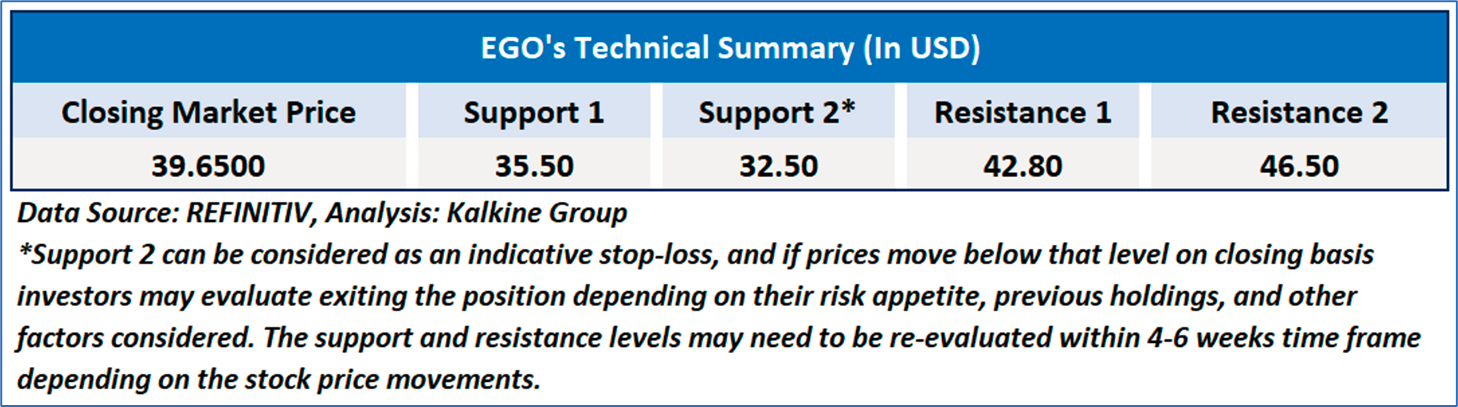
As per the above-mentioned price action, important support near USD 34.00- USD 36.00, momentum in the stock over the last month, and technical indicators analysis, a ‘Buy’ rating has been given for Eldorado Gold Corporation (NYSE: EGO) at the closing price of USD39.65, as of February 03, 2026.

Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario. 

Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.

Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc. 

Note 1: Past performance is not a reliable indicator of future performance.

Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 03, 2026. The reference data in this report has been partly sourced from REFINITIV.

Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.

Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.

Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.


Disclaimer-

Kalkine Equities LLC, with Delaware File Number 4697384, Foreign Qualification Registration in California File Number 202109211078, and Texas File Number 805521396, is authorized to provide general advice only. The information on https://kalkine.com/ does not take into account any of your investment objectives, financial situation or needs. You should consider the appropriateness of advice taking into account your own objectives, financial situation and needs and seek independent financial advice before making any financial decisions. The link to our Terms and Conditions  and Privacy Policy has been provided for your reference. On the date of publishing the reports (mentioned on the website), employees and/or associates of Kalkine do not hold positions in any of the stocks covered on the website. These stocks can change any time and readers of the reports should not consider these stocks as advice or recommendations later.

Past performance is not a reliable indicator of future performance.

Support

Hi! How can we help you today?

Loading…