Endeavour Silver Corporation
Endeavour Silver Corp. (NYSE: EXK) is a Canada-based mid-tier silver producer with three operating mines in Mexico and Peru and a pipeline of exploration projects across Mexico, Chile, and the United States. The Company is engaged in silver mining and related activities including acquisition, exploration, development, extraction, processing, refining and reclamation. The Company’s Guanacevi mines is a highest-grade silver mine, which is located in Durango, Mexico.

Key Business and Financial Updates:
- Strategic Transformation and Capital Positioning: Endeavour Silver (EXK) executed a material strategic repositioning in FY2025, highlighted by the acquisition of Kolpa, commencement of commercial production at Terronera (October 2025), and the divestiture of the Bolañitos mine (closed January 2026). The company further strengthened its capital structure through a USD 350 million convertible debt issuance, enhancing balance sheet flexibility to advance its flagship Pitarrilla project. As of December 31, 2025, liquidity remained robust with USD 215 million in cash, supporting ongoing exploration, feasibility work, and early-stage development initiatives, including a planned USD 68 million investment in Pitarrilla during 2026.
- Financial Performance and Production Scale-Up: The company delivered record financial performance, supported by significant production growth and favorable commodity pricing. FY2025 revenue reached USD 468 million (+115% YoY), while mine operating earnings stood at USD 83 million and mine operating cash flow before taxes totaled USD 156 million (+116% YoY). Total production increased to ~11 million silver-equivalent ounces (+48% YoY), driven by contributions from Kolpa and Terronera. In Q4 alone, production reached nearly 4 million silver-equivalent ounces, including 2 million ounces of silver and 14,000 ounces of gold, reflecting a 146% increase YoY. Adjusted net earnings for Q4 were USD 4.8 million (USD 0.02 per share), despite headwinds from derivative losses and financing costs.
- Cost Structure and Margin Drivers: Cost metrics reflected transitional pressures associated with ramp-up and portfolio expansion. Cash costs increased to approximately USD 19 per ounce of payable silver, while direct operating costs per ton rose by ~8% YoY, primarily due to higher initial costs at Terronera and increased royalties, duties, and third-party ore purchases. All-in sustaining costs (AISC) were temporarily elevated, with Terronera alone incurring USD 16.3 million in sustaining capital in Q4, translating to approximately USD 48 per ounce AISC for the quarter. Importantly, cost sensitivity to metal prices remains significant, with each USD 1 increase in silver price increasing per-ton costs by USD 0.90 (Terronera), USD 0.50 (Kolpa), and USD 3.80 (Guanaceví) due to royalty and duty structures.
- Operational Execution and Asset-Level Metrics: Operationally, Terronera remains in a ramp-up optimization phase, with throughput stabilizing and recoveries improving sequentially. The company is targeting 2,000 tons per day throughput through 2026, with a transition to higher-grade zones in H2 2026 expected to enhance output quality. Kolpa is undergoing expansion from 2,000 to 2,500 tons per day in Q1 2026, supporting incremental production growth and cost efficiencies. Notably, operational disruptions such as power instability are being addressed through a transition from diesel generation (USD 0.33/MWh) to LNG-based power (USD 0.17/MWh), implying ~50% reduction in energy costs and improved reliability. Additionally, grade profiles are expected to improve progressively, with materially higher-grade ore (200–280 g/t silver range) anticipated from 2027 onwards.
- Outlook, Growth Pipeline, and Market Leverage: Looking forward, Endeavour Silver is positioned to leverage elevated precious metal prices (silver ~USD 90+, gold ~USD 5,000 levels), which significantly enhance cash flow generation despite cost inflation. The company maintains strong production visibility supported by asset diversification and long-term agreements, while advancing Pitarrilla toward a feasibility study completion in Q3 2026 and potential construction decision in early 2027. With improving cost efficiencies, expanding throughput, and a clear trajectory toward higher-grade production, EXK is transitioning toward a higher-margin, scalable silver producer with increasing operating leverage to commodity prices.
Key Company specific risks for EXK:
- Operational Ramp-Up and Execution Risk: Endeavour Silver’s near-term performance is highly dependent on the successful ramp-up and stabilization of key assets, particularly Terronera and Kolpa. Terronera remains in its early production phase, with ongoing challenges related to throughput consistency, power reliability, and cost efficiency. Delays in achieving nameplate capacity (2,000 TPD), slower-than-expected recovery rates, or operational disruptions (including energy transition and regional security concerns) could adversely impact production volumes, unit costs, and overall profitability.
- Cost Inflation and Margin Sensitivity: The company faces elevated cost sensitivity driven by royalties, duties, energy inputs, and labor inflation, particularly in a high commodity price environment. Cost per ton increases with rising silver prices due to royalty-linked structures, while wage inflation and input cost pressures may further compress margins. In addition, transitional inefficiencies and sustaining capital requirements at Terronera could keep all-in sustaining costs elevated in the near term, limiting margin expansion despite favorable pricing.
- Commodity Price and Hedging Exposure: EXK remains significantly exposed to volatility in silver and gold prices, which are primary drivers of revenue and cash flow. Any correction in precious metals prices could materially affect earnings and valuation. Additionally, the company has ongoing gold hedge exposure extending into 2027, which may constrain upside participation in a rising price environment and introduce mark-to-market earnings variability. Foreign exchange fluctuations, particularly related to the Mexican peso, further add to financial uncertainty.
Technical Observation (on the daily chart):
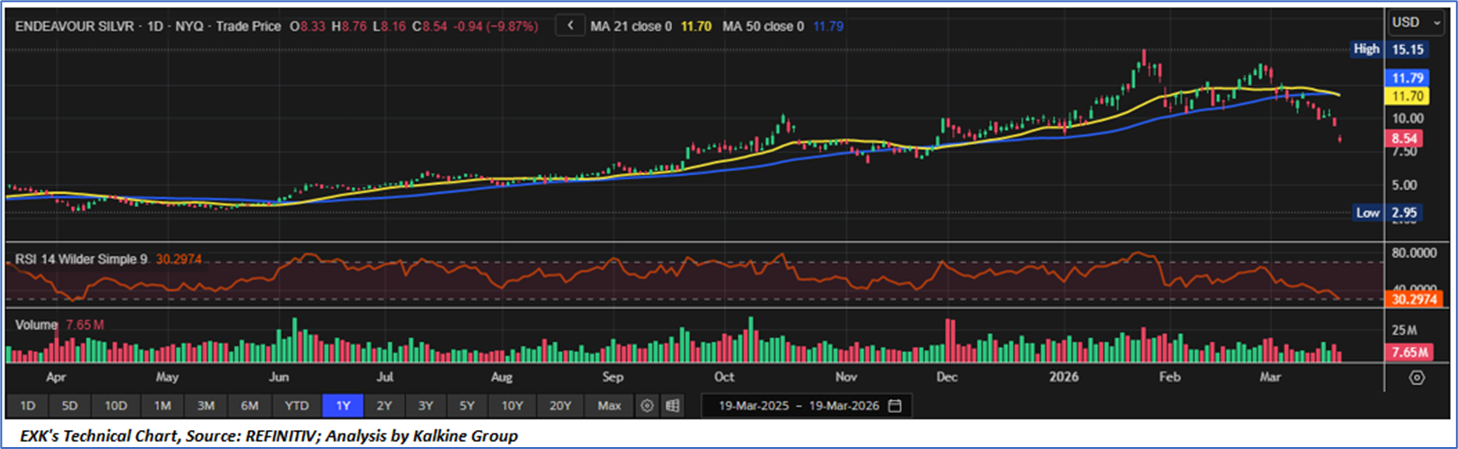
- Price Trend and Moving Average Breakdown: Endeavour Silver (EXK) has recently exhibited a clear breakdown in its prior uptrend, following a sustained rally that peaked near USD 15.15. The stock has corrected sharply and is currently trading around USD 8.54, reflecting a significant drawdown. Importantly, price action has fallen below both the 21-day moving average (USD 11.70) and the 50-day moving average (USD 11.79), indicating a shift from a bullish to a bearish short-term and intermediate trend structure. The downward slope in these moving averages further reinforces weakening price momentum and suggests continued pressure unless a strong reversal emerges.
- Momentum Indicators and Relative Strength: Momentum indicators confirm the deterioration in technical strength, with the Relative Strength Index (RSI) positioned near 30, approaching oversold territory. While this indicates that the stock is technically stretched on the downside, it also reflects persistent selling pressure rather than immediate reversal confirmation. The absence of bullish divergence suggests that momentum remains weak, and any near-term bounce may initially be corrective rather than indicative of a sustained trend reversal.
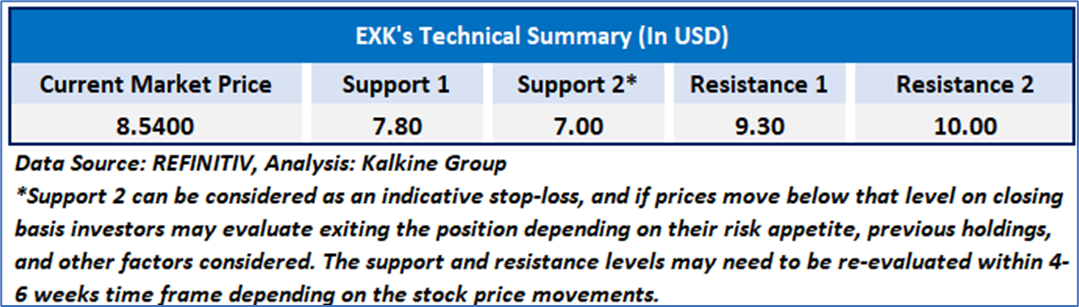
- Support, Resistance, and Volume Dynamics: From a key levels perspective, immediate support is observed around the USD 8.00–USD 8.50 range, with a breakdown potentially exposing the next major support near USD 5.00, as indicated by historical price zones. On the upside, the USD 11.70–USD 11.80 region (21DMA and 50DMA) now acts as a strong resistance band, and a decisive move above this level would be required to re-establish bullish momentum. Volume trends show elevated selling activity during the recent decline, suggesting distribution rather than accumulation. Overall, the technical setup remains bearish with oversold conditions, implying a potential short-term bounce but continued caution until key resistance levels are reclaimed.
Endeavour Silver (EXK) presents a compelling growth-oriented investment case, supported by a transformational operational scale-up, strengthening balance sheet, and strong leverage to elevated precious metal prices. The company delivered record FY2025 performance with revenue of USD 468 million (+115% YoY) and production growth of ~48%, driven by the successful integration of Kolpa and the commencement of Terronera. With USD 215 million in liquidity and USD 350 million in fresh capital, EXK is well-capitalized to advance its high-quality development pipeline, particularly Pitarrilla, which underpins long-term production visibility. Operationally, ongoing improvements at Terronera, capacity expansion at Kolpa, and a transition to lower-cost energy are expected to drive cost normalization and margin expansion through 2026, while higher-grade production from 2027 provides further upside. In the context of structurally strong silver prices and rising industrial demand, EXK is transitioning into a higher-scale, higher-margin silver producer with significant operating leverage, positioning it favorably for sustained value creation despite near-term execution and cost headwinds
As per the above-mentioned price action, important support near USD 8.00- USD 8.50, momentum in the stock over the last month, and technical indicators analysis, a ‘Buy’ rating has been given for Endeavour Silver Corp. (NYSE: EXK), at the current price of USD 8.54, as of March 19, 2026, at 07:20 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 19, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 AU
 IND

 US

 Please wait processing your request...