Nu Holdings Ltd
Nu Holdings Ltd (NYSE: NU) is a Brazil-based holding company, which engages in the provision of digital banking services. The Company offers its customers products across the five financial seasons: spending, saving, investing, borrowing, and protecting. Its spending solutions are designed to help customers pay for goods and services in their everyday lives with a customized credit line or instantly through a mobile phone, while collecting loyalty points and rewards on applicable transactions.

Key Business and Financial Updates:
- Record Financial Performance and Scalable Growth Model: NU delivered a historically strong first quarter, supported by its established growth model centered on customer expansion, increasing monetization, and scalable operating leverage. The company surpassed 135 million customers globally, including more than 115 million in Brazil, over 15 million in Mexico, and nearly 5 million in Colombia. Consolidated monthly activity rates remained robust at 83%, while Average Revenue per Active Customer (ARPAC) increased sequentially to approximately USD 16. This translated into record quarterly revenue of USD 5 billion and first-quarter net income of USD 871 million, reflecting continued operational scalability and earnings compounding. Management emphasized that the company’s efficiency ratio declined below 18%, demonstrating the benefits of platform scale despite ongoing investments in AI transformation and international expansion.
- Credit Expansion Supported by Resilient Asset Quality: Nu continued to expand its credit operations aggressively while maintaining confidence in the resilience of its underwriting framework and portfolio quality. The consolidated credit portfolio reached USD 37.2 billion, increasing 40% year-over-year, driven primarily by 36% growth in credit cards and 53% growth in unsecured lending. Management clarified that elevated credit provisioning during the quarter reflected seasonality, portfolio growth, and product mix changes rather than deterioration in underlying credit quality. While the 15–90 day NPL ratio increased seasonally to 5%, late-stage delinquencies improved sequentially to 6.5%, remaining below prior peak levels. The company also maintained strong balance sheet protection, with total coverage ratios at 16.2% of the portfolio and provisions materially exceeding new non-performing loan formation, reinforcing management’s disciplined approach toward risk-adjusted profitability and long-term portfolio resilience.
- International Expansion and Mexico Profitability Inflection: Management highlighted meaningful progress across international operations, particularly in Mexico, where the company achieved its first quarter of IFRS profitability ahead of internal expectations. Nu described Mexico as a structurally underpenetrated banking market with significant long-term opportunity, supported by low formal banking penetration and high cash usage. Over four years, the Mexican customer base expanded approximately sevenfold to 15 million users, while operational efficiency improved materially and ARPAC nearly doubled. The company noted that its market share in Mexico remains below 1%, indicating substantial future expansion potential. In parallel, Colombia continued to demonstrate healthy customer growth momentum. Management also reiterated that expansion into the United States will remain disciplined and measured, with investment levels capped to maintain efficiency ratio stability unless clear product-market fit is established.
- AI Transformation Driving Productivity and Competitive Advantage: Nu positioned artificial intelligence as a core strategic pillar underpinning its long-term competitive differentiation. Management explained that the company is transitioning beyond traditional productivity enhancement toward building an “AI-native bank,” integrating AI directly into underwriting, operations, customer experiences, and product development. Internal AI adoption has reached nearly full utilization across the organization, contributing to over 50% growth in engineering throughput and significantly faster testing cycles. Proprietary AI models are already being utilized for real-time credit card and unsecured lending decisions in Brazil and Mexico, enabling individualized pricing and approvals within seconds. Management believes Nu’s scale, proprietary technology infrastructure, and extensive customer data provide structural advantages that position the company favorably for continued AI-driven innovation and operational leverage.
- Efficiency, Profitability, and Long-Term Strategic Positioning: Nu continued to demonstrate strong operating leverage during the quarter, with reported efficiency ratios improving to 17.6%, while core efficiency ratios excluding strategic investments declined further to 16.6%. Management stated that approximately one-third of these improvements reflect durable structural gains driven by AI-enabled productivity, software consolidation, and disciplined hiring practices, while the remaining benefits were associated with temporary timing factors. Net interest income reached a record USD 3.25 billion, supported by balance sheet optimization and faster growth in earning assets relative to liabilities. The company also highlighted a structurally improved tax framework expected to support long-term earnings expansion. Looking ahead, management reiterated confidence in the company’s substantial addressable market opportunity, emphasizing that despite significant customer scale, market penetration across Latin America remains relatively low, providing a long runway for sustained profitable growth.
Key Risks for NU:
- Credit Quality and Consumer Lending Risk: Nu’s business model remains heavily exposed to unsecured consumer lending, particularly through credit cards and personal loans. Although management emphasized that recent increases in provisions were driven by seasonality and portfolio growth rather than deterioration in asset quality, the company’s rapid expansion in higher-yield unsecured products increases sensitivity to macroeconomic stress, unemployment trends, and consumer repayment behavior across Latin America. Rising delinquency levels, weaker household income conditions, or an economic slowdown in Brazil or Mexico could materially pressure profitability, provisioning requirements, and net interest margins.
- Regulatory and Expansion Execution Risk: Nu operates in highly regulated financial markets where evolving banking, fintech, consumer credit, and data privacy regulations could increase compliance costs or constrain growth initiatives. In addition, the company is pursuing international expansion, including further scaling in Mexico, Colombia, and early-stage entry into the United States. Failure to achieve product-market fit, unexpected regulatory hurdles, or operational execution challenges in these markets could reduce returns on investment and pressure efficiency metrics. Management specifically noted that future U.S. scaling remains contingent upon demonstrating profitable scalability.
- Margin Compression from Growth Investments and Competitive Pressure: While Nu currently benefits from strong operating leverage and industry-leading efficiency ratios, the company continues to invest aggressively in AI infrastructure, international expansion, product development, and customer acquisition. Sustained investment requirements, combined with increasing competition from incumbent banks, digital banks, and global fintech platforms, could compress margins over time. Furthermore, maintaining ARPAC growth and engagement levels at the current scale may become increasingly challenging as the company penetrates lower-income or less mature customer cohorts across newer markets.
Technical Observation (on the daily chart):
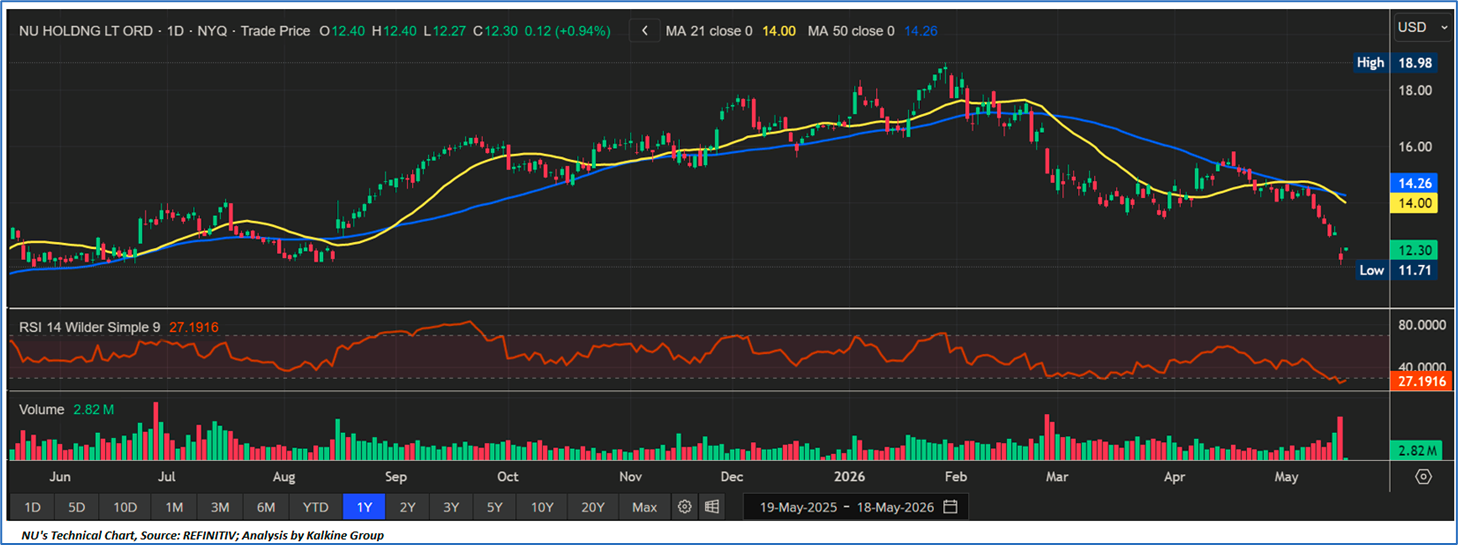
- Trend Structure and Moving Average Analysis: NU continues to exhibit a pronounced medium-term corrective structure following its failure to sustain momentum near the USD 19.00 resistance region earlier in the year. The stock is currently trading materially below both the 21-day moving average at approximately USD 14.00 and the 50-day moving average near USD 14.26, confirming a bearish crossover configuration and persistent downside momentum. Price action has also established a sequence of lower highs and lower lows over recent months, reflecting sustained institutional distribution pressure. The inability to reclaim the short-term moving averages indicates that rallies are currently being sold into rather than accumulated, while the recent breakdown below the USD 12.00–12.30 support region reinforces the continuation of the prevailing downtrend structure.
- Momentum Indicators and Volume Dynamics: The Relative Strength Index (RSI-14) is currently positioned near 27, entering deeply oversold territory and signaling accelerated bearish momentum. While such readings can occasionally precede technical relief rallies, the absence of bullish divergence suggests that downside pressure remains dominant in the near term. Importantly, the recent decline has been accompanied by elevated trading volumes, indicating conviction behind the selling activity rather than a low-liquidity pullback. Volume expansion during breakdown phases typically reflects institutional repositioning and increases the probability of extended weakness before a durable base formation emerges. Unless RSI stabilizes alongside price consolidation above key support levels, momentum conditions continue to favor sellers over buyers.
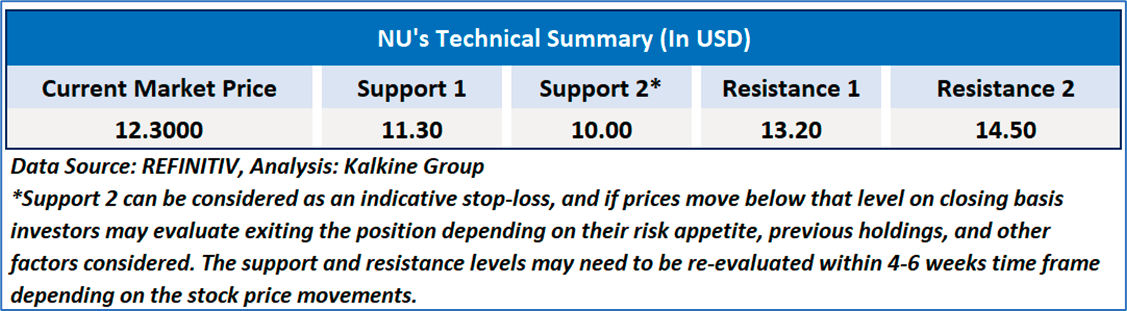
- Key Support, Resistance, and Forward Technical Outlook: From a structural perspective, immediate support is now positioned near the recent low around USD 11.70–11.80, which represents a critical short-term demand zone. A decisive breakdown below this level could expose further downside toward the psychological USD 10.00 region over the medium term. On the upside, the stock faces layered resistance near USD 14.00 and USD 14.25, corresponding to the 21-day and 50-day moving averages respectively. Any recovery attempt would likely require a sustained breakout above these dynamic resistance levels to confirm trend stabilization and invalidate the current bearish bias. Until price action demonstrates stronger accumulation characteristics and recaptures its moving average structure, the broader technical outlook for NU remains cautious with downside risks continuing to outweigh bullish reversal probabilities.
NU continues to strengthen its position as one of the fastest-scaling digital financial platforms globally, supported by robust customer growth, rising monetization, and improving operating leverage across its core Latin American markets. The company delivered record quarterly revenue and profitability while simultaneously expanding its credit portfolio, enhancing engagement levels, and maintaining resilient asset quality metrics. Strong momentum in Mexico, accelerating AI integration across underwriting and operations, and sustained efficiency improvements further reinforce Nu’s long-term structural growth story. Despite ongoing investments in international expansion and technology infrastructure, the company continues to demonstrate scalable earnings power, diversified revenue generation, and significant untapped market opportunity, positioning it favorably for sustained long-term growth within the global digital banking landscape.
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Buy’ rating has been Nu Holdings Ltd (NYSE: NU) at the current market price of USD 12.30, as of May 18, 2026, at 06:40 am PDT.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is May 18, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 AU
 IND

 US

 Please wait processing your request...