
 CA
 NZ
 UK
 AU
 IND

 US

Opendoor Technologies Inc
Opendoor Technologies Inc. is an e-commerce platform for residential real estate transactions. By leveraging software, data science, product design and operations, the Company is engaged in building a technology platform for residential real estate that offers buyers and sellers a digital, on-demand experience. Its product offerings include Sell to Opendoor, List with Opendoor and Opendoor Marketplace.

Key Business and Financial Updates:
Key Company specific risks for OPEN:
Technical Observation (on the daily chart):
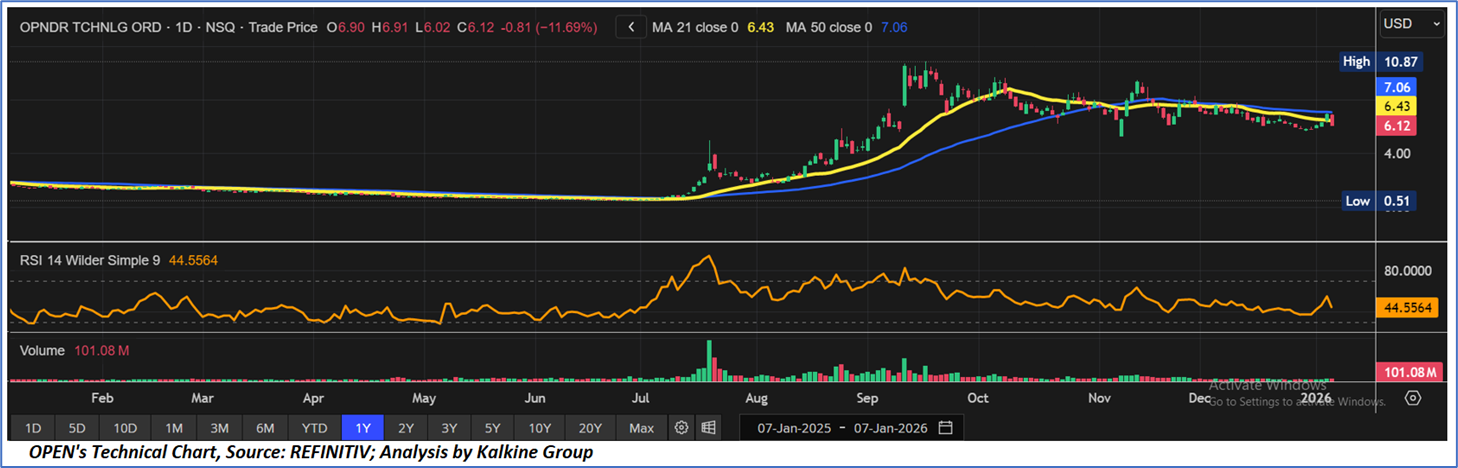
Opendoor Technologies Inc. is undergoing a broad strategic and operational transition as management repositions the company toward a software- and AI-led real estate platform, with a stated objective of achieving breakeven Adjusted Net Income by the end of 2026. The reset emphasizes disciplined execution through higher acquisition volumes, improved unit economics, and tighter cost control, supported by new AI-driven pricing and resale tools. Financially, Q3 2025 reflected a deliberate contraction phase, with revenue of USD 915 million, gross margin of 7.2%, and continued operating losses, alongside a materially reduced inventory base that lowers balance-sheet risk. Near-term performance is expected to remain pressured as legacy inventory is cleared and revenue declines sequentially, even as acquisition activity rebounds. Key risks remain tied to housing market cyclicality, execution on the profitability roadmap, and inventory-related liquidity exposure, while technically the stock is consolidating in the USD 6.0–6.5 range.
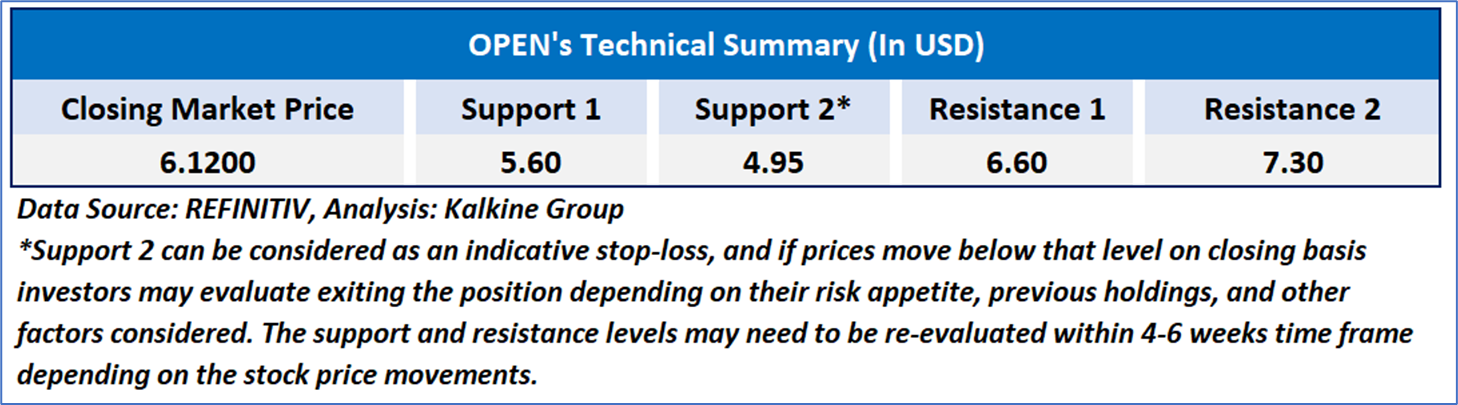
As per the above-mentioned price action, important resistance near USD 7.00- USD 7.30, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Opendoor Technologies Inc (NASDAQ: OPEN), at the closing price of USD 6.12, as of January 07, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is January 07, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.
Kalkine Equities LLC, with Delaware File Number 4697384, Foreign Qualification Registration in California File Number 202109211078, and Texas File Number 805521396, is authorized to provide general advice only. The information on https://kalkine.com/ does not take into account any of your investment objectives, financial situation or needs. You should consider the appropriateness of advice taking into account your own objectives, financial situation and needs and seek independent financial advice before making any financial decisions. The link to our Terms and Conditions and Privacy Policy has been provided for your reference. On the date of publishing the reports (mentioned on the website), employees and/or associates of Kalkine do not hold positions in any of the stocks covered on the website. These stocks can change any time and readers of the reports should not consider these stocks as advice or recommendations later.
Past performance is not a reliable indicator of future performance.
 Please wait processing your request...