
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
Chinese crude steel output fell 2.7% year-on-year to 84.35 million tons in May, and mill profitability has deteriorated to approximately 51%, reflecting the deep and persistent demand deficit created by the property sector's prolonged contraction.
Iron ore port inventories at Chinese terminals have reached a record seasonal high of 160 million tons, signalling that seaborne supply has been running materially ahead of domestic mill demand for an extended period, with no immediate catalyst for rebalancing in sight.
China's property sector contraction — now in its third year of significant downturn — continues to function as the dominant structural headwind for global steel, iron ore, and rebar markets, with cascading effects that are visible in multiple simultaneous market indicators.
May crude steel output declined 2.7% year-on-year to 84.35 million tons, continuing a trend of production restraint that reflects both weak downstream demand and deliberate capacity discipline by mills seeking to protect margins in a challenging pricing environment. The year-on-year decline is particularly meaningful given that 2025 comparisons were already subdued.
Steel mill profitability has deteriorated to approximately 51% in the latest industry survey — a level that represents a significant margin squeeze from historical norms and creates strong incentives for further production cuts. The margin pressure has been compounded by rising coke costs following the Shanxi mining accident, tightening the input cost squeeze at a time when finished steel prices are also under pressure.
The property sector's importance to Chinese steel demand cannot be overstated. Residential and commercial construction historically accounted for approximately 30-35% of Chinese steel consumption, encompassing demand for rebar, structural steel, flat products for appliances and fittings, and pipes. The prolonged suppression of construction activity has therefore created a demand deficit of significant scale.
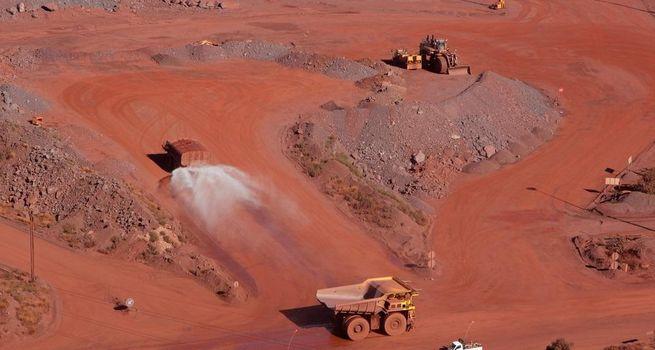
Iron ore inventories at Chinese ports have reached a record 160 million tons for this time of year, a stockpile level that effectively signals the market's assessment of the demand outlook. When mills anticipate soft forward demand, they delay purchases and allow port inventories to accumulate. Record seasonal stockpiles therefore act as both a symptom of current weakness and a headwind to near-term price recovery.
The path to recovery for Chinese steel-related commodities runs primarily through the property sector. While infrastructure investment, manufacturing output, and renewable energy construction provide partial demand offsets, none of these sectors individually or collectively approaches the scale impact of residential construction. Policy stimulus targeting property completions, mortgage financing, and developer liquidity would be the most direct potential catalyst for a market rebalancing.
Question: Why is China's property sector so important to global iron ore and steel markets?
Answer: China is the world's largest steel producer and consumer, accounting for roughly half of global steel output. Within China, the property and construction sector has historically been the single largest source of steel demand. Because iron ore is the primary raw material for steelmaking, Chinese property sector conditions have a direct and often dominant influence on global iron ore demand, prices, and trade flows, making Chinese real estate dynamics one of the most closely watched variables in commodities markets globally.
Question: What policy measures could revive Chinese construction steel demand?
Answer: Effective measures would likely include direct support for property developer liquidity to enable stalled project completions, mortgage rate reductions or subsidies to stimulate homebuyer demand, accelerated approval of urban renewal and social housing projects, and fiscal incentives for infrastructure investment in transportation and utilities. The challenge is that demand support measures take time to translate into actual construction activity and therefore steel demand, meaning the market impact of any policy shift would unfold over quarters rather than weeks.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 31, 2026
 Please wait processing your request...