
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
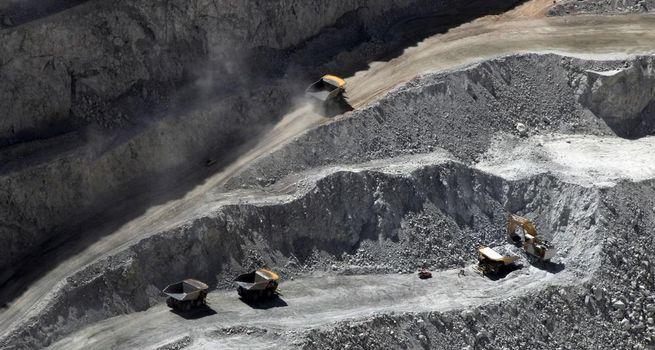
Steel rebar futures fell below CNY 3,060 per ton Friday, hitting a four-month low, as mill profitability dropped to approximately 51% — down 4.8 percentage points week-on-week — following coke price spikes triggered by a fatal Shanxi coal mine accident.
Chinese crude steel output fell 2.7% year-on-year to 84.35 million tons in May as the property sector slump continued to suppress construction steel demand, compounding an already difficult margin environment for mills.
Steel rebar futures declined below CNY 3,060 per ton on Friday, reaching their lowest level in four months as a deteriorating profit environment at Chinese steel mills combined with seasonally weak construction demand to exert sustained downward pressure on prices.
Industry data revealed that the profitability rate among Chinese steel mills fell to approximately 51% in the latest reporting week — a decline of 4.8 percentage points from the previous week and 8.2 percentage points below year-earlier levels — painting a picture of rapidly eroding margins across the sector.
The margin squeeze has been meaningfully exacerbated by a fatal coal-mining accident in Shanxi province last month. The tragedy disrupted coke supply from the region, driving up coke prices and forcing steel mills to adapt their raw material mix. Many mills responded by increasing the proportion of medium-to-high-grade iron ore used in their blast furnaces, seeking to offset efficiency losses caused by tighter coke availability — a strategy that adds to input costs.
Chinese crude steel production has continued to weaken against this difficult backdrop, with May output falling 2.7% year-on-year to 84.35 million tons. The decline reflects both demand-side weakness driven by the property sector's protracted contraction and capacity discipline among mills seeking to protect margins in a challenging price environment.
The property sector headwind is particularly significant for rebar, which is predominantly used in reinforced concrete construction. With residential property starts and completions remaining subdued and limited near-term catalyst for a sharp recovery in housing activity, the demand outlook for construction steel products remains structurally challenging.
For steel market observers, the convergence of higher input costs, weaker demand, and declining output represents a textbook margin squeeze scenario that historically precedes either significant production cuts or a period of extended price weakness. Unless Chinese policymakers deliver targeted stimulus to the property and infrastructure sectors, conditions for rebar prices are unlikely to improve materially in the near term.
Question: How did a coal mine accident in Shanxi affect steel rebar prices?
Answer: The fatal accident in Shanxi province disrupted coking coal supply from the region, pushing up coke prices — a key input cost for blast furnace steelmaking. With higher coke costs squeezing margins, some mills shifted to using higher-grade iron ore to improve efficiency, while others cut production, contributing to the adverse pricing dynamics in the rebar market.
Question: Will Chinese government stimulus help rebar prices recover?
Answer: Targeted infrastructure or property sector stimulus could provide meaningful support to Chinese construction steel demand and help stabilise rebar prices. However, the scale of stimulus required to offset the structural drag from the prolonged property sector downturn is significant, and near-term recovery appears unlikely without a clear policy catalyst or a sustained rebound in residential construction activity.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 29, 2026
 Please wait processing your request...