
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
With markets pricing an 80% probability of a December Fed rate hike and 63% odds of a September move, monetary policy expectations have overtaken geopolitical risk as the dominant force shaping commodity prices across energy, metals, and agricultural markets.
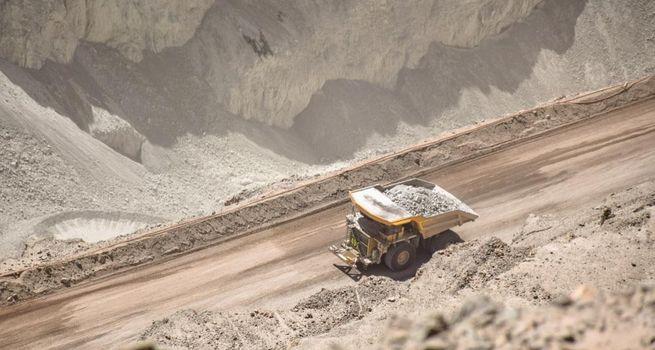
The pattern is visible simultaneously across gold (-5%), silver (-14%), copper (seven-week lows), and crude oil (-10%), illustrating how a single macro variable can dominate commodity market direction across otherwise unrelated sectors.
Federal Reserve monetary policy expectations have emerged as the single most powerful driver of commodity market direction in the current environment, overriding sector-specific supply and demand dynamics across energy, metals, and precious metals markets simultaneously.
Markets are now pricing an 80% probability of a Fed rate hike in December and approximately 63% odds of a September move, following last week's hawkish policy pause under Chair Kevin Warsh and the Fed's upward revision to its inflation projections. These expectations are reshaping commodity markets through three distinct channels: dollar appreciation, rising real yields, and growth concerns.
A hawkish Fed strengthens the US dollar, which makes dollar-priced commodities mechanically more expensive for buyers using other currencies. This currency channel simultaneously suppresses demand signals from major import markets including China, Europe, Japan, and emerging economies, creating a broad-based headwind that affects copper, oil, gold, silver, and other internationally traded commodities.
Rising real yields — the interest rate available on inflation-protected government bonds — increase the opportunity cost of holding non-yielding commodities such as gold and silver. When investors can earn positive real returns from safe government securities, the relative appeal of physical metal holdings diminishes, systematically reducing financial demand for precious metals.
The growth concern channel operates more indirectly: expectations of higher borrowing costs raise fears about global economic slowdown, reducing forward demand estimates for industrial commodities such as copper, steel, and oil. Even without an actual recession, the anticipation of slower growth can suppress commodity prices as market participants price in lower future consumption.
For commodity investors and industrial companies managing input costs, the current environment underscores the importance of monitoring Federal Reserve communication as carefully as any supply-demand fundamental. In a period where both geopolitical and monetary policy risks are evolving rapidly, the interaction between these two forces — one reducing supply risk, the other raising growth risk — creates a particularly complex navigation challenge.
Question: Why do Federal Reserve rate hikes affect commodity prices so broadly?
Answer: Fed rate hikes affect commodities through multiple simultaneous channels: they strengthen the US dollar (making dollar-priced commodities more expensive for foreign buyers), raise real yields (increasing the opportunity cost of holding non-yielding physical commodities), and signal tighter financial conditions (raising growth concerns that reduce demand forecasts for industrial commodities). The breadth of these transmission mechanisms explains why Fed policy shifts can dominate commodity market direction across otherwise unrelated sectors.
Question: Could commodity prices recover even if the Fed raises rates?
Answer: Yes — commodity prices can recover during Fed tightening cycles if supply-side factors or demand fundamentals are sufficiently powerful to overcome the macroeconomic headwinds. Historical examples include the 2004-2006 period when commodity prices rose strongly alongside multiple Fed rate hikes, driven by robust Chinese demand growth. The key question is whether supply or demand drivers are strong enough to reassert themselves once the initial market reaction to tighter monetary policy subsides.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 31, 2026
 Please wait processing your request...