
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Idaho Strategic Resources is a US-based gold producer operating principally in Idaho.
• The company pairs active gold production with extensive exploration ground.
• IDR also holds exploration interests in rare-earth elements, adding strategic-minerals optionality.
• Domestic production gives IDR current cash flow rather than purely speculative appeal.
Most junior gold stories ask investors to imagine future production from deposits still in the ground. Idaho Strategic Resources Inc. (NYSEAMERICAN:IDR) offers something less common: a company that already produces gold in the United States while simultaneously sitting on a large exploration land position and an intriguing rare-earth interest. That combination, current cash flow plus layered optionality, all within a stable domestic jurisdiction, has helped IDR build a reputation as a quietly compounding story rather than a binary speculation. The "quietly" matters. This is not a company that dominates headlines; it is one that has steadily expanded its footprint and output while keeping a foot in the strategic-minerals door. For investors, the appeal lies in a producer that controls its own destiny more than a pure explorer, balanced against the reality that scaling a small US gold operation profitably is its own demanding challenge.
Company Overview
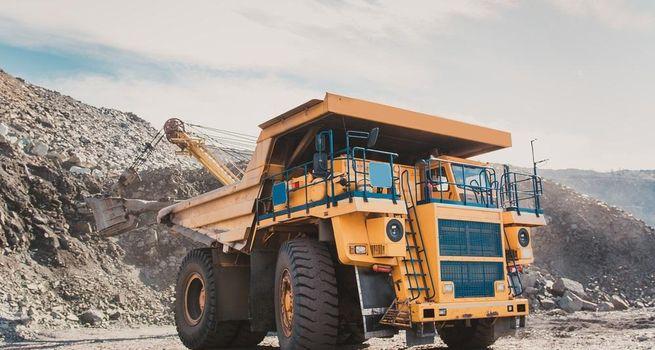
Idaho Strategic Resources is a domestically focused gold producer and exploration company centered in Idaho, a state with a deep mining heritage. Its business has two complementary dimensions. The first is active gold production, which generates revenue and distinguishes IDR from the many juniors that have yet to pour their first ounce. The second is exploration: the company holds a substantial land position across prospective ground, giving it room to expand resources and extend the life of its operations through the drill bit rather than through acquisitions alone. Layered on top is an exploration interest in rare-earth elements, minerals deemed strategically important for technology and defense supply chains, which adds a distinctive angle to an otherwise gold-centric profile. This blend positions Idaho Strategic Resources as both an operating gold company and a holder of longer-dated optionality.
The result is a profile that can appeal to investors seeking domestic production with embedded exploration and strategic-minerals upside.
Why the Stock Is in Focus
IDR attracts attention for reasons that set it apart from typical gold juniors. Its status as a US gold producer means it is not purely a story stock; it has revenue and a tangible operating base, which appeals to investors wary of perpetual pre-production names. Its domestic footprint resonates with a broader theme of reshoring critical and precious-metals supply, particularly given the rare-earth exploration angle that ties into national strategic-minerals priorities. The company's pattern of steadily expanding production and exploration, often without fanfare, has also drawn investors who prefer compounding fundamentals over hype cycles. At the same time, IDR's relatively small scale means each operational improvement, drill result or exploration milestone can move the needle meaningfully.
The combination of current cash flow, exploration optionality and a strategic-minerals kicker makes Idaho Strategic Resources a distinctive name in the US gold space, and that distinctiveness is much of why it stays in focus.
Gold, Silver and Precious-Metals Market Backdrop
Idaho Strategic Resources is fundamentally leveraged to gold, so the metals backdrop is central to its story. Gold's enduring role as a hedge against inflation, currency debasement and geopolitical risk supports demand, while its price responds to real interest rates, central-bank activity and the dollar's direction. For a producer like IDR, a firm gold price flows directly into margins and cash flow, since revenue rises against a largely fixed cost base, and it strengthens the case for expanding output and funding exploration. The rare-earth angle adds a second, distinct backdrop: strategic minerals are shaped less by traditional precious-metals dynamics and more by technology demand, supply-chain security concerns and government policy aimed at reducing reliance on foreign sources. This dual exposure means IDR can benefit from two separate but topical themes.
The flip side is that weaker gold would pressure the core producing business, and rare-earth economics remain early-stage and policy-dependent, so neither tailwind is guaranteed.
Key Catalysts Driving Investor Interest
Several catalyst categories shape the IDR story. Production performance is foremost: as an operating gold company, improvements in output, grades and operating efficiency translate directly into financial results and can re-rate the stock. Exploration success is another major lever, since IDR's large land position offers the chance to expand resources, extend mine life and uncover new zones through drilling. Progress on the rare-earth exploration interest provides a distinct catalyst with potential to capture attention given the strategic importance of those minerals. Capital-allocation decisions, how the company reinvests cash flow into growth versus exploration, also matter, because disciplined deployment can compound value over time. Finally, a supportive gold price magnifies the impact of production and exploration gains.
Because IDR combines a producing base with exploration and strategic-minerals optionality, its catalyst set spans both near-term operational results and longer-dated discovery potential, giving investors multiple avenues through which the story can advance.
Financial and Valuation Considerations
Valuing Idaho Strategic Resources requires blending the lenses used for producers and for explorers. As an operating gold company, IDR can be assessed on its production economics, margins and cash generation, which give it a more tangible financial footing than pre-revenue juniors. Investors often consider how efficiently the company converts gold output into cash flow and how that cash is reinvested. Layered on top is the option value of its exploration ground and rare-earth interest, which is inherently harder to quantify and tends to be valued on potential rather than current contribution. The interplay between these elements, steady production cash flow funding exploration that could expand the asset base, is central to the growth thesis. None of these considerations should be read as precise forecasts.
They are the conceptual frameworks through which the market weighs whether IDR's valuation appropriately balances its current producing business against the longer-dated optionality embedded in its land position and strategic-minerals exposure.
Growth Outlook and Project Pipeline
The growth outlook for IDR rests on a virtuous-circle concept: use cash flow from existing gold production to fund exploration that expands resources, extends mine life and potentially brings new ground into production. This self-funded growth model, if it works, can compound value without leaning heavily on dilutive financing, a meaningful distinction from many juniors. The exploration pipeline benefits from a sizable land position in a historically productive region, offering room for both near-mine expansion and greenfield discovery. The rare-earth interest adds a separate, longer-dated avenue of optionality tied to strategic-minerals demand. Realizing this outlook depends on continued operational execution, drilling success and disciplined capital allocation. For believers, the combination of production-funded exploration and strategic-minerals upside makes IDR a quietly compounding growth story; for skeptics, the question is whether a relatively small operation can scale efficiently while pursuing multiple avenues at once without overextending itself.
Major Risks Investors Should Watch
Idaho Strategic Resources carries the risks typical of a small producer alongside some unique to its profile. Operational risk is significant: smaller mines can be sensitive to grade variability, cost inflation and the challenges of scaling production efficiently. Commodity-price risk is central, since weaker gold would compress the margins that fund the company's growth model. Exploration risk is inherent, drilling may not deliver the resource expansion that underpins the long-term thesis. The rare-earth interest, while distinctive, is early-stage and depends on uncertain economics, technical hurdles and supportive policy, so it should be viewed as optionality rather than a guaranteed value driver. Capital-allocation risk also matters; pursuing production growth, exploration and strategic minerals simultaneously could stretch resources if not carefully managed. Permitting and regulatory considerations, though generally manageable in a domestic jurisdiction, still apply.
Investors weighing IDR should keep these interlocking risks in perspective against its current producing base.
What Could Drive the Stock Next
The next phase for Idaho Strategic Resources is likely to hinge on the interplay between production results and exploration momentum. Continued operational strength, steady or growing output with controlled costs, could reinforce the self-funded growth narrative and support sentiment. Encouraging drill results that expand resources or extend mine life would validate the exploration thesis and add to the long-term value case. Meaningful progress on the rare-earth interest could spotlight IDR's strategic-minerals optionality, particularly amid ongoing supply-chain and policy attention. A supportive gold price would amplify the impact of production gains on margins and cash flow. On the downside, operational setbacks, disappointing exploration, cost pressures or a softer gold environment could weigh on the stock.
Because IDR already produces gold, it is less dependent on a single binary event than many juniors, but its smaller scale means each operational and exploration result can carry outsized influence over the share price.
Conclusion
Idaho Strategic Resources makes a case that a US gold company can be more than a story stock. By pairing active domestic production with a large exploration land position and a strategic rare-earth interest, it offers a blend of current cash flow and layered optionality that distinguishes it from typical juniors. The phrase "quietly becoming a quality growth story" captures both its appeal and its character: steady, self-funded progress rather than headline-driven speculation. Yet the realities of operating a smaller mine, the uncertainty of exploration and the early-stage nature of its strategic-minerals exposure mean the path is far from guaranteed, and the gold price will remain a powerful swing factor.
For investors approaching it as an educational case study rather than a directive, IDR offers an instructive example of how domestic gold production, exploration upside and strategic minerals can combine in a single, differentiated US equity.

 Nov 04, 2026
 Please wait processing your request...