
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
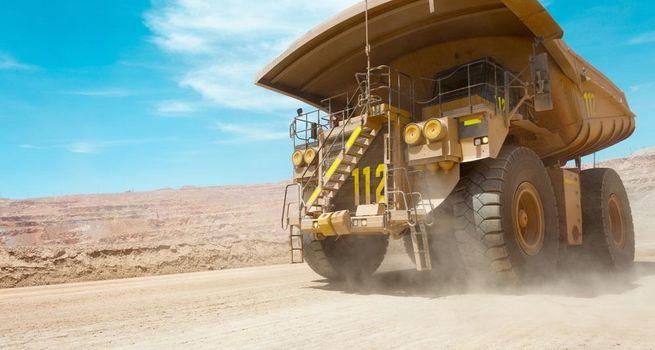
Iron ore futures declined below CNY 740 per ton, hovering near their lowest levels in almost a year as Chinese steel mill profitability fell to approximately 51% and port inventories at Chinese terminals hit a record seasonal high of 160 million tons.
A monthly price decline of 8.14% reflects the widening gap between expanding seaborne supply and subdued Chinese domestic demand, a structural imbalance driven by the ongoing property sector contraction.
Iron ore futures dropped below CNY 740 per ton Friday, hovering near twelve-month lows as a convergence of demand weakness, rising port inventories, and deteriorating steel mill margins continued to erode prices for the primary steelmaking raw material.
Chinese steel mill profitability — the key transmission mechanism between iron ore demand and steel production volumes — fell to approximately 51% in the latest reporting week, down 4.8 percentage points from the prior week and 8.2 percentage points below year-ago levels. As mills' ability to generate adequate returns on production deteriorates, their incentive to purchase iron ore at current prices diminishes, creating a natural demand ceiling for the raw material.
A fatal coal-mining accident in Shanxi province last month has compounded the margin pressure by driving up coke prices. In response, some mills have shifted toward using higher-grade iron ore to improve blast furnace efficiency, providing modest support for premium ore grades but insufficient to offset the broader demand weakness across the market.
Port inventories at Chinese terminals have climbed to a record 160 million tons for this time of year — a stockpile level that signals seaborne supply from Australian and Brazilian miners has been running materially ahead of domestic consumption requirements. Record port stocks effectively remove any sense of near-term supply urgency among buyers and give mills negotiating leverage over purchase timing and pricing.
The monthly price decline of 8.14% underscores the market's acute sensitivity to Chinese steel sector dynamics. Despite remaining 6.23% above year-ago levels, the accelerating monthly deterioration signals that the year-on-year premium is eroding rapidly as demand fundamentals weaken.
A durable iron ore price recovery would likely require either a meaningful revival in Chinese property sector construction activity — which has been the market's primary demand engine for decades — or significant voluntary production discipline from major mining groups. Neither development appears imminent, leaving iron ore prices vulnerable to further downside in the near term.
Question: Why are record Chinese port stockpiles bearish for iron ore prices?
Answer: Elevated port inventories signal that seaborne supply is exceeding domestic demand requirements, reducing Chinese steel mills' urgency to purchase additional material. High stockpiles give mills flexibility to delay purchases, increasing their negotiating leverage and reducing the upward price pressure that comes from genuine supply scarcity. At record levels for this time of year, the current inventory overhang is a significant structural headwind for near-term iron ore prices.
Question: How does China's property sector drive iron ore demand?
Answer: China's property sector has historically been the single largest driver of steel demand, which in turn drives iron ore consumption. Residential and commercial construction requires substantial quantities of steel reinforcement bar, structural steel, and flat steel products, all of which require iron ore as a primary input. The prolonged contraction in Chinese property construction has therefore created a persistent structural demand deficit for iron ore that has not been fully offset by growth in other steel-consuming sectors.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 29, 2026
 Please wait processing your request...