
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
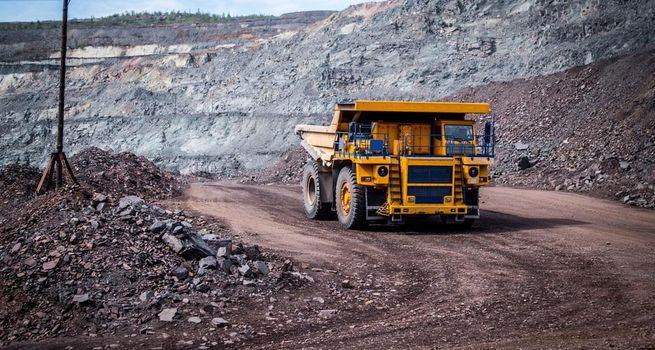
The Section 232 tariff on Canadian softwood lumber, scheduled to take effect in August 2026, represents a potential re-acceleration in import costs that buyers are already factoring into purchasing decisions, having contributed to lumber's recent rally toward eight-month highs.
US domestic production remains insufficient to substitute for Canadian imports in the near term, leaving the lumber market structurally exposed to tariff changes and creating a potential price catalyst in August that could reignite the recent rally from current consolidation levels.
The August 2026 implementation date for the Section 232 tariff on Canadian softwood lumber is increasingly functioning as a market calendar event of the first order, shaping inventory decisions, purchasing behaviour, and price expectations well ahead of the actual levy's activation.
Section 232 of the Trade Expansion Act allows import tariffs to be imposed on national security grounds, and its application to Canadian lumber adds a further cost layer on top of existing antidumping and countervailing duties that have already elevated the total tariff burden to historically high levels. While preliminary antidumping and countervailing rates were recently reduced, the net tariff package remains substantial, and the additional Section 232 levy will push landed import costs higher still.
The anticipation of this August cost step-up has been a material driver of recent lumber market behaviour. Buyers and distributors seeking to build inventory ahead of the higher-cost environment have accelerated purchases, pulling forward demand and contributing to lumber's recent rally toward near eight-month highs around $624 per thousand board feet. This front-loading dynamic creates a classic commodity price pattern: elevated near-term prices followed by potential demand weakness once the pre-buying inventory build is complete.
US domestic sawmill capacity remains insufficient to meaningfully substitute for Canadian imports in the short to medium term. The western North American forest products industry faces structural constraints including aging infrastructure, timber supply restrictions, and elevated operating costs that limit the domestic supply response to higher Canadian import prices. This structural dependency keeps the US lumber market sensitive to any changes in import cost dynamics.
On the demand side, residential construction continues to provide underlying support, but declining housing affordability — driven by elevated mortgage rates, higher construction labour costs, and expensive financing — is emerging as a growing constraint on new homebuilding activity. The balance between tariff-driven supply cost support and demand softening from affordability pressures will be the central tension in the lumber market through the second half of 2026.
For lumber traders and construction industry participants, August 2026 represents a pivotal date. The Section 232 tariff's activation could reignite price momentum if demand proves resilient, or it could prove insufficient to offset demand weakness if housing affordability deterioration accelerates. Monitoring building permit data and mortgage application trends in the coming weeks will be essential for assessing which scenario is more likely.
Question: What is the difference between antidumping, countervailing, and Section 232 tariffs on lumber?
Answer: Antidumping duties are imposed when foreign producers are found to be selling lumber below fair market value in the US. Countervailing duties are applied when foreign governments are found to be providing unfair subsidies to their lumber industries — in Canada's case, this relates to the system of government-owned timberlands. Section 232 is a separate national security provision that allows tariffs regardless of dumping or subsidy findings. All three can apply simultaneously, and Canada's lumber exports to the US currently face a combination of all three levies, making the total tariff burden among the highest in the bilateral trade relationship.
Question: How should homebuilders and construction companies plan for the August tariff change?
Answer: Companies with significant lumber purchasing requirements in the second half of 2026 may want to consider accelerating purchases ahead of August to build inventory at current prices, locking in forward price hedges where available, and evaluating alternative sourcing from domestic producers or non-Canadian international suppliers. However, the cost of carry for large inventory positions and the risk that demand weakens enough to offset the tariff impact should also be factored into procurement strategies.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 31, 2026
 Please wait processing your request...