
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
Platinum fell below $1,600 an ounce to its lowest level since November 2025 as the US dollar climbed to a multi-year high and Federal Reserve rate hike expectations intensified following Chair Kevin Warsh's hawkish guidance.
Despite the near-term macroeconomic headwinds, the platinum market remains structurally tight, with output from South Africa and Russia constrained by aging infrastructure, rising costs, and sanctions-related disruptions.
Platinum futures declined below $1,600 an ounce on Friday, marking the metal's weakest level since November 2025 and extending a broad-based sell-off across precious metals driven by a strengthening US dollar and intensifying Federal Reserve rate hike expectations.
The US dollar's rise to its highest level against a basket of major currencies in over a year has been a principal headwind for platinum, as dollar strength makes the metal structurally more expensive for buyers transacting in euros, yen, and other currencies. This currency-driven demand suppression is independent of the metal's fundamental supply-demand balance and can persist as long as dollar strength is sustained.
Chair Kevin Warsh's hawkish guidance last week, combined with the Fed's upward revisions to its inflation forecasts, has reinforced market expectations that US interest rates will rise further in 2026. Higher real yields increase the opportunity cost of holding non-yielding assets including platinum, applying systematic downward pressure to prices regardless of underlying supply fundamentals.
Progress in US-Iran peace talks has removed a significant inflation risk premium from broader commodity markets, further reducing platinum's appeal as an inflation or geopolitical hedge. With crude oil prices returning toward pre-conflict levels, the inflationary impulse that had been partially supporting precious metals demand has materially diminished.
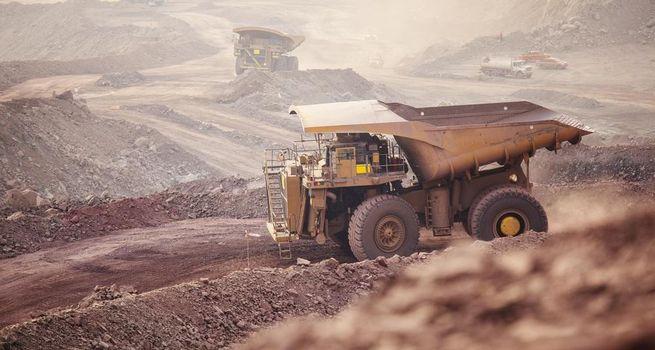
Notwithstanding the near-term macroeconomic pressures, platinum's structural supply picture remains tight. South Africa — which produces the majority of the world's platinum — continues to face challenges including aging mine infrastructure, escalating energy and labour costs, and persistent power supply disruptions. Russian supply, the second-largest contributor to global output, remains uncertain given ongoing sanctions-related disruptions.
For longer-term investors, the combination of cyclical price weakness and structural supply constraints — alongside growing demand from hydrogen fuel cell vehicle manufacturing and other clean energy applications — presents an investment case that warrants monitoring even if the near-term macroeconomic environment remains challenging.
Question: Why is platinum more sensitive to Federal Reserve policy than gold?
Answer: Platinum and gold both face headwinds from higher real yields and a stronger dollar during Fed tightening cycles. However, platinum is also an industrial metal used in automotive catalytic converters and fuel cells, meaning it faces the additional risk of weaker industrial demand in a slowing economy — a dual vulnerability that can amplify its sensitivity to tightening monetary conditions relative to gold.
Question: What is the long-term demand outlook for platinum?
Answer: Platinum's long-term demand outlook is supported by its critical role as a catalyst in hydrogen fuel cell vehicles and industrial hydrogen production, sectors that are expected to grow substantially over the next decade as part of the global energy transition. While near-term demand from traditional automotive catalytic converters has been affected by the shift to battery electric vehicles, hydrogen fuel cell growth is expected to create a significant new demand driver that could reshape the platinum market's long-term balance.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research or consult a qualified financial adviser before making any investment decisions.

 Oct 31, 2026
 Please wait processing your request...