
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
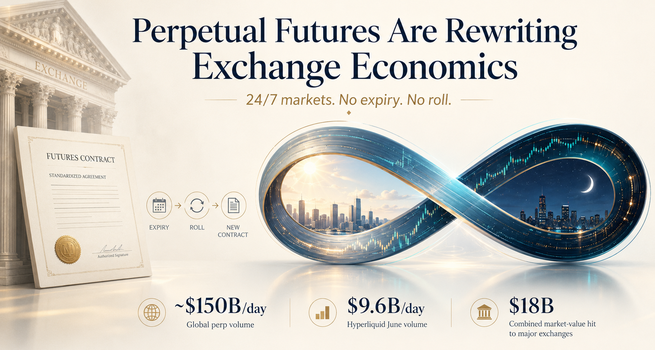
- Perpetual futures, blockchain-enabled Derivatives that never expire, generated roughly $150 billion in average daily notional Volume globally in 2026, challenging the Revenue model of traditional exchanges.
- Decentralized venue Hyperliquid averaged $9.6 billion in daily perpetual notional volume in June, and processed over $1.2 billion in SpaceX-linked perps on the day of the company's Nasdaq IPO.
- President Trump signalled a regulatory path for Hyperliquid under the CFTC, raising the prospect of perps on equities and commodities entering the regulated US market.
- CME Group has filed suit against the CFTC over its classification of Bitcoin perps as futures rather than swaps, a legal distinction with significant Capital and Margin implications for the industry.
- Incumbent exchanges including Cboe, ICE, and Deutsche Borse are responding through extended-hours trading, hybrid partnerships with crypto venues, and new long-duration derivative products.
A Structural Challenge, Not a Cyclical One
Traditional financial exchanges are built around a fundamental mechanic: contracts expire. That expiry is not incidental. It is the engine of a Recurring Revenue stream known as the roll, the process by which traders close a near-dated Futures Contract and open a longer-dated one, generating fee income for the exchange at each transition. Perpetual futures eliminate that mechanic entirely.
Perpetual futures, or perps, are blockchain-enabled derivatives with no expiry date and no delivery obligation. They can track virtually any underlying asset, are accessible around the clock including nights and weekends, and typically allow significant leverage. Their price stays anchored to the underlying through a funding rate mechanism, where long holders pay short holders, or vice versa, at regular intervals depending on whether the perp trades at a premium or discount to spot.
For the exchange industry, the threat is structural rather than cyclical. The roll, zero-day-to-expiry Options expansion, and extended trading hours have all emerged in recent years as the market has migrated toward continuous, low-friction access. Perps are the logical endpoint of that trajectory, and their roots in crypto, an Asset Class whose appeal was always bound to 24/7 availability, give them an established retail base that is beginning to attract institutional attention.
Hyperliquid and the Decentralised Wedge
The dominant force in the perpetual Futures Market is not a regulated exchange. Hyperliquid, a decentralised trading and settlement blockchain, processed close to $200 billion in notional perpetual volume in a single month in 2025. Average Daily Volume in June 2026 stood at $9.6 billion. The platform is operated alongside marketplace operator Trade[XYZ], forming what functions as a decentralised international exchange, and its native token HYPE has appreciated roughly 196% this year.
In March 2026, Trade[XYZ] secured an exclusive licence from S&P Dow Jones Indices to offer perpetual derivatives on the S&P 500. The commercial logic is direct: Hyperliquid's perps provide retail and increasingly institutional investors with around-the-clock exposure to major indices, equities, and commodities without the friction of contract expiry or the cost of the roll.
The SpaceX IPO in June illustrated the market's reach. More than seven million SpaceX perps with a notional value exceeding $1.2 billion traded on Hyperliquid the day of the listing. The perp price tracked within dollars of the stock's first official transaction at $150, demonstrating that decentralised perp venues can provide meaningful price discovery for Assets that have not yet reached public markets.
Regulated Entry and What It Signals
Perpetual futures entered the regulated US market in May 2026 when the CFTC approved bitcoin perps on prediction marketplace Kalshi, making it the first domestically regulated operator to offer the product. Within the first month, Kalshi traded over $20 billion in perpetual notional volume. The company has since filed applications to offer perps on gold, silver, and platinum.
The regulatory significance expanded further when President Trump indicated at a press conference in August 2026 that a CFTC regulatory framework for Hyperliquid may be forthcoming. The implication, that perps on equities and commodities could gain regulated status in the US, sent shares of incumbent exchanges lower. CME Group, Cboe Global Markets, the Intercontinental Exchange, and Miami International Holdings collectively lost approximately $18 billion in combined Market Value over two trading sessions.
CME's Legal Challenge and the Swap Classification Question
CME Group, through its CEO Terry Duffy, has been the most prominent institutional critic of perpetual futures. In June 2026, CME filed suit against the CFTC, arguing that bitcoin perps should be classified as swaps under the Commodity Exchange Act rather than futures. The legal distinction carries meaningful economic consequences.
The Commodities Exchange Act defines futures as contracts of sale of a commodity for future delivery. Perpetuals, which have no expiry and no delivery, do not fit that description in CME's interpretation. The Dodd-Frank Act prohibits an instrument from being classified simultaneously as a futures contract and a swap. If perpetuals are categorised as swaps, operators such as Kalshi and Polymarket, which run their own clearinghouses, would face considerably more onerous capital and margin requirements.
The CFTC has characterised the lawsuit as frivolous. Kalshi has argued that the suit is motivated by competitive concern rather than legal principle, noting that perps represent a structurally cheaper and simpler product for end users given the single-fee, open-exit structure. The resolution of this litigation will set the definitional parameters of the asset class and determine which regulatory regime governs the capital requirements of those listing and trading them.
Incumbent Responses: Adaptation Over Resistance
The strategic calculus at incumbent exchanges has been shifting. While CME pursues litigation, it has also acknowledged internally that contract specifications for perpetual-style products exist and could be brought to market if Demand conditions warrant. Cboe launched 120-month-to-expiry continuous futures late last year. Robinhood Markets offers crypto perpetuals to European customers.
More structurally significant are the Partnership arrangements emerging between traditional exchange infrastructure and crypto venues. ICE, the parent of the New York Stock Exchange, announced a $200 million Investment in international crypto exchange OKX in March 2026, establishing a 50-50 joint venture to offer tokenised equities and crypto futures. Deutsche Borse's Eurex division similarly acquired a $200 million stake in Kraken operator Payward, following an earlier partnership with the exchange.
These arrangements reflect a recognition that the technology, liquidity, and user base that perps have assembled cannot be easily replicated by incumbents from within their existing regulatory and product frameworks. Hybridisation, combining the compliance infrastructure of traditional exchanges with the 24/7 accessibility and product flexibility of crypto venues, may represent the most practical competitive path.
Institutional Demand and the Leverage Question
Perpetual futures remain predominantly a retail product, but institutional interest is building. Market-makers active in global derivatives have noted that institutional activity in perps is already present across multiple underlying assets, with crypto perps being issued in London. Firms operating in this space have indicated willingness to extend such offerings to US-regulated venues as regulation clarifies.
The leverage embedded in perps remains a point of concern for observers and some incumbent operators. Cboe's global head of derivatives has noted that perps as a substitute for options breaks down analytically because options offer asymmetric payouts with defined maximum loss, while perps expose the holder to open-ended leverage without the structural risk cap that options provide. In zero-day-to-expiry options, more than 90% of trades carry capped downside, a characteristic that perps do not replicate.
Outlook
The perpetual futures market is not yet large relative to established derivatives venues. Average daily notional volume of approximately $150 billion globally compares with $2 to $3 trillion in daily S&P 500 options notional value. But the trajectory, the product's structural appeal, the entry of regulated operators, and the likelihood of broader CFTC authorisation suggest that comparison will narrow.
The deeper question is not whether perps disrupt exchange revenues, but through which mechanism and over what time horizon. The roll, the IPO and listings business, the swap dealer revenue embedded in leveraged ETF structures, and the data fees tied to price discovery are all potentially affected as perps extend their reach into traditional asset classes. Traditional exchange economics, built over decades on the friction of expiry and the architecture of the contract cycle, now face a product designed from inception to eliminate that friction entirely.

 Nov 13, 2026
 Please wait processing your request...