
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
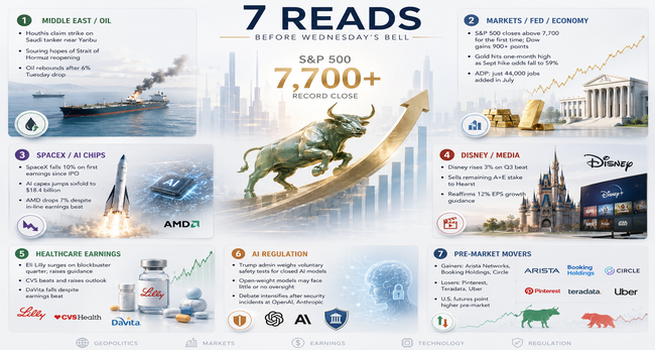
The S&P 500 closed above 7,700 for the first time Tuesday on hopes of a Strait of Hormuz reopening, but Houthi militants claimed a strike on a Saudi tanker near Yanbu overnight, souring the ceasefire outlook and pushing oil higher. SpaceX fell 10% in its first earnings report since going public as AI-driven capital spending jumped sixfold, while ADP showed private employers added just 44,000 jobs in July ahead of Friday's payrolls report.
1. IRAN/OIL: Houthis Claim Strike on Saudi Tanker Near Yanbu, Souring Hormuz Reopening Hopes; Oil Rebounds After 6% Tuesday Drop; CENTCOM Says Southern Route "Free and Open"
Yemen's Iran-backed Houthi militants said they struck a Saudi Arabian tanker with a missile near the port of Yanbu, a major hub for Saudi crude exports, rattling markets and souring hopes for an imminent Middle East ceasefire. Brent crude rose 1% to $80.15 per barrel and WTI gained 0.28% to $75.98, rebounding after oil fell roughly 6% Tuesday on optimism that the Strait of Hormuz could reopen this week. Treasury Secretary Scott Bessent had told Tuesday a deal to unlock the waterway, a vital transit route for oil, gas, fertilizer, and other industrial products, could be reached within days. U.S. Central Command said late Tuesday the strait's southern route through Omani waters was "free and open" to commercial vessels, a claim now in tension with the Houthi strike report.
- Oil's rebound after Tuesday's 6% drop shows how quickly the ceasefire premium can reverse on a single unconfirmed attack, even as CENTCOM's statement points the other direction.
- Bessent's comments and Trump's decision earlier in the week to call off a planned Iran attack in favor of negotiations had driven Tuesday's oil selloff and equity rally alike.
- Risk note: if the Yanbu strike is confirmed and Houthis continue targeting Saudi export infrastructure, the reopening narrative that lifted equities Tuesday could unwind before Friday's jobs report shifts the conversation.
2. MARKETS/FED: S&P 500 Closes Above 7,700 for First Time, Dow Gains 900+ Points on Record Run; Gold Hits One-Month High as September Hike Odds Fall to 59%; ADP Shows Just 44,000 Jobs Added in July
The S&P 500 rose 1.8% Tuesday to close above 7,700 for the first time, while the Dow gained more than 900 points for another record close, lifted by strong earnings and Bessent's Hormuz comments. Gold climbed 2.2% to $4,164.13 per ounce, its highest since July 7, as peace-deal hopes eased inflation concerns and the 10-year yield fell to a one-week low. Traders now price a 59% probability of a September hike, down from 67% a day earlier, per CME FedWatch. Kansas City Fed President Jeff Schmid said Tuesday some tightening is still needed to bring "too high" inflation to target. Separately, ADP reported private employers added just 44,000 jobs in July, with June revised down from 98,000 to 95,000; pay growth for job-changers accelerated to 7.0% year-over-year, the fastest since August 2025.
- Gold and falling yields moving with declining hike odds signals the market read Tuesday's optimism as disinflationary, a dynamic now complicated by the Houthi strike in story one.
- ADP's 44,000 print, well below the twice-revised June figure, arrives two days ahead of nonfarm payrolls and adds to a choppier hiring picture even as job-changer pay accelerates.
- Risk note: if Friday's payrolls confirm the ADP softness while oil reverses higher on the Houthi strike, the Fed faces weakening labor data and renewed energy-driven inflation risk simultaneously.
3. AI CHIPS/SPACEX: SpaceX Falls 10% on First Earnings Since IPO as AI Capex Jumps Sixfold to $18.4 Billion; AMD Drops 7% Despite In-Line Beat
SpaceX (NASDAQ:SPCX) shares fell about 10% after the company's first quarterly report since its June IPO showed second-quarter capital expenditures of $18.37 billion, up roughly 550% from a year earlier and driven largely by AI spending. Revenue of $7.81 billion topped the consensus of $6.93 billion, though the company posted a net loss of $541 million and a loss of 9 cents per share. AMD (NASDAQ:AMD) fell as much as 8.5% pre-market despite adjusted earnings of $1.66 per share on revenue of $11.54 billion, both slightly ahead of consensus, with third-quarter guidance of roughly $13 billion largely in line
- SpaceX's sixfold capex increase, even alongside a meaningful revenue beat, shows investors are scrutinizing AI infrastructure spending intensity as closely as top-line growth for newly public companies.
- AMD falling despite beating every headline metric mirrors a pattern seen elsewhere this earnings season, where in-line guidance reads as a disappointment against elevated expectations.
- Risk note: if SpaceX's capex trajectory continues without a corresponding revenue acceleration, the market's tolerance for AI-driven spending among newly public companies may tighten further into its next report.
4. DISNEY/MEDIA: Disney Rises More Than 3% on Q3 Beat and A+E Stake Sale to Hearst; Reaffirms 12% EPS Growth Guidance
Disney (NYSE:DIS) shares rose more than 3% after fiscal third-quarter adjusted earnings of $2.06 per share topped the $1.86 consensus, on revenue of $25.25 billion, up 7% year-over-year, though Experiences segment revenue, including theme parks, grew 10% and outperformed the headline number. The beat arrived alongside news that Disney is selling its remaining 50% stake in A+E Global Media to Hearst for approximately $1.2 billion, a move satisfying Wall Street calls to streamline the portfolio toward core streaming, sports, and parks businesses. Disney reaffirmed 12% adjusted EPS growth guidance for fiscal 2026 and double-digit growth for fiscal 2027.
- The A+E divestiture is the more strategically significant headline beneath the earnings beat, signaling Disney is actively exiting non-core media joint ventures rather than just posting a strong quarter.
- Parks revenue growth of 10%, ahead of the company's 7% overall growth, confirms Experiences remains Disney's strongest-performing business line this quarter.
- Risk note: if streaming subscriber growth fails to keep pace with the reaffirmed EPS guidance, the market may question whether Parks strength alone can sustain the double-digit outlook through fiscal 2027.
5. PHARMA/HEALTHCARE: Eli Lilly Surges More Than 6.5% on Blowout Quarter and Raised Guidance, New CVS Zepbound Deal; CVS Jumps on Guidance Hike; DaVita Falls Despite Beat
Eli Lilly (NYSE:LLY) shares jumped more than 6.5% after second-quarter adjusted earnings of $8.38 per share far exceeded the $6.01-$6.07 consensus, with revenue of $22.97 billion topping estimates near $20.7-$20.9 billion on strong GLP-1 franchise growth; the company raised full-year 2026 revenue guidance to $85-$87 billion from $82-$85 billion. Lilly also announced a new collaboration with CVS Health (NYSE:CVS) to expand access to Zepbound and other GLP-1 medications through CVS's pharmacy network, a deal that also lifted CVS shares.
CVS reported adjusted earnings of $2.58 per share against a $1.85 consensus, with revenue of $106.1 billion surpassing the $100 billion estimate, and raised full-year adjusted EPS guidance to $7.90-$8.10 from $7.30-$7.50, citing improved Aetna cost trends and favorable Medicare Advantage bonus payments. DaVita (NYSE:DVA) shares fell more than 5.5% despite beating on both revenue and adjusted earnings, after the company left full-year guidance unchanged at $14.10-$15.20 per share, below the $14.88 consensus
- Lilly's guidance raise, delivered a day after rival Novo Nordisk's (NYSE:NVO) cautious outlook, reinforces investor confidence in Lilly's competitive position rather than the weight-loss category broadly.
- CVS shares have surged roughly 39% over the past quarter into this print, with 24 of 27 analysts rating it a buy, showing the market had already priced much of the turnaround before today's hike confirmed it.
- Risk note: DaVita's unchanged guidance despite a beat, alongside sequential softness in dialysis revenue per treatment, suggests rising G&A expenses are absorbing gains that would otherwise flow to the bottom line.
6. AI POLICY: Trump Administration Weighs Voluntary Safety Tests for "Closed" AI Models, Leaves "Open-Weight" Models Free of Oversight
Trump administration officials reportedly told leading AI firms they could submit "closed" models, those whose source code is not publicly available, for voluntary safety testing, while "open-weight" models, whose parameters are public, would face no such oversight. The administration is weighing how to regulate the technology after models from OpenAI and Anthropic were found to have hacked several companies' systems.
- Confining voluntary testing to closed models while exempting open-weight systems creates a gap that could push development toward open-weight architectures specifically to avoid scrutiny.
- The policy discussion arrives the same week SpaceX's AI capex disclosure and AMD's earnings put fresh scrutiny on AI infrastructure spending, adding a regulatory dimension to an already AI-focused week.
- Risk note: a voluntary framework with no enforcement mechanism may do little to prevent incidents like the OpenAI and Anthropic breaches, leaving room for more prescriptive legislation if additional hacks occur.
7. PRE-MARKET MOVERS/SETUP: Arista Surges 12% and Booking Jumps 7% on Big Beats; Circle Rises 5% on Arc Blockchain Validators; Pinterest, Teradata, and Uber Fall on Guidance Misses
Arista Networks (NYSE:ANET) rose 12% after second-quarter adjusted earnings of $1.02 per share beat the 88-cent estimate on revenue of $3.04 billion against $2.82 billion expected, with third-quarter guidance also ahead of consensus. Booking Holdings (NASDAQ:BKNG) advanced more than 7% after second-quarter gross bookings of $51 billion beat the Street's $49.35 billion estimate, with adjusted earnings of $2.54 per share and revenue of $7.35 billion both topping expectations.
Circle Internet Group (NYSE:CRCL) rose more than 5% after naming BlackRock (NYSE:BLK), Visa (NYSE:V), Mastercard (NYSE:MA), and other major institutions as founding validators for its Arc blockchain network ahead of a September 16 mainnet launch, offsetting a revenue miss tied to a 4.6% decline in USDC circulation. Pinterest (NYSE:PINS) slid nearly 9% after third-quarter revenue guidance of $1.19-$1.21 billion failed to impress despite a second-quarter beat. Teradata (NYSE:TDC) slumped 13% after third-quarter earnings guidance of 55-59 cents per share trailed the 62-cent consensus. Uber (NYSE:UBER) fell 3% after third-quarter bookings and earnings guidance missed expectations, with management citing foreign-exchange headwinds. Dow futures rose 178 points, S&P 500 futures added 0.4%, and Nasdaq-100 futures gained 0.2% ahead of the open.
- Arista and Booking both beat every headline metric and raised or matched forward guidance, the clearest "beat and guidance holds up" pattern in an earnings season otherwise dominated by beats that still triggered selloffs.
- Circle's ability to rally on the Arc validator news despite missing revenue shows the market pricing institutional adoption ahead of near-term USDC circulation trends.
- Risk note: Pinterest, Teradata, and Uber all beat or matched current-quarter estimates but fell on forward guidance, extending the pattern seen in today's SpaceX and AMD reactions, where the market discounts current results in favor of scrutinizing the outlook.
Markets Intelligence Briefing is an informational and analytical publication. Nothing contained herein constitutes investment advice, a recommendation to buy or sell any security, or a price target. All analysis is presented for informational purposes only. Investors should conduct their own due diligence before making any investment decision.

 Nov 20, 2026


 Please wait processing your request...