
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Health Care (XLV) and Utilities (XLU) remain the market's primary leaders, continuing to occupy the Leading quadrant with superior relative strength and positive momentum.
- Communication Services (XLC) and Consumer Discretionary (XLY) are now firmly positioned in the Improving quadrant, signalling strengthening momentum and growing investor interest.
- Industrials (XLI), Financials (XLF), Consumer Staples (XLP), Real Estate (XLRE), and Materials (XLB) remain in Weakening, reflecting fading momentum despite maintaining positive relative strength.
- Technology (XLK) and Energy (XLE) continue to reside in the Lagging quadrant, although Energy is showing signs of recovery in relative momentum.
- Market leadership remains defensive in nature, while selected growth-oriented sectors are beginning to emerge as potential future leaders.
The latest Relative Rotation Graph (RRG) for July 8, 2026, indicates that defensive sectors continue to dominate market leadership. Health Care and Utilities remain firmly entrenched within the Leading quadrant, reflecting persistent institutional demand for sectors offering stability and earnings resilience. At the same time, Communication Services and Consumer Discretionary have strengthened their positions within the Improving quadrant, suggesting investor confidence is gradually expanding beyond purely defensive areas of the market.
US Sector Relative Momentum Summary
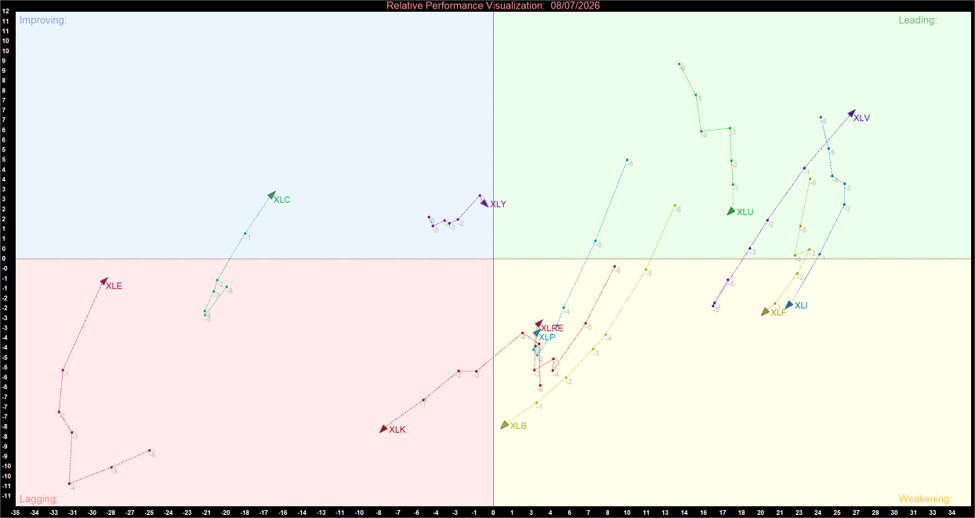
US Sector Relative Momentum Chart (at the closing price of 08/07/2026). Powered by: amibroker.com
Key Market Theme
The Leading Quadrant (The Market Leaders)
- Health Care (XLV) remains one of the strongest sectors on the RRG and continues to advance within the Leading quadrant. The sector's position reflects a combination of strong relative strength and positive momentum, reinforcing its status as a preferred destination for investors seeking defensive growth opportunities. Its continued leadership suggests institutional capital remains concentrated in businesses offering stable earnings visibility and resilient fundamentals.
- Utilities (XLU) also remain firmly established within the Leading quadrant. Although the sector has experienced some moderation in momentum compared with previous peaks, it continues to demonstrate superior relative strength versus the broader market. The sector's ability to maintain leadership highlights investors' ongoing preference for predictable cash flows and defensive characteristics amid an increasingly selective investment environment.
The Improving Quadrant (Emerging Leaders)
- Consumer Discretionary (XLY) remains positioned within the Improving quadrant and continues to display constructive rotational behaviour. The sector's trajectory indicates strengthening momentum and improving relative performance, suggesting that investor appetite for selected cyclical growth opportunities is gradually recovering. If current trends persist, Consumer Discretionary could be among the next sectors to challenge for market leadership.
- Communication Services (XLC) has strengthened further within the Improving quadrant after successfully recovering from a prolonged period of relative weakness. The sector's improving momentum profile suggests institutional demand is returning, while its north-eastern rotation points to the potential for continued relative outperformance. A sustained improvement could eventually support a transition into the Leading quadrant.
The Weakening Quadrant (Losing Momentum)
- Industrials (XLI) remain within the Weakening quadrant and continue to exhibit declining momentum despite maintaining positive relative strength. The sector's position suggests that leadership has faded in recent weeks as investors become more selective toward economically sensitive industries.
- Financials (XLF) also remain in Weakening, reflecting ongoing deterioration in momentum. Although the sector still possesses respectable relative strength, a meaningful recovery in momentum will likely be required before Financials can re-establish themselves as market leaders.
- Consumer Staples (XLP) remain in Weakening and continue to lose momentum. Despite retaining defensive characteristics, the sector appears to be attracting less capital than stronger defensive alternatives such as Health Care and Utilities.
- Real Estate (XLRE) remains positioned within Weakening, indicating that relative strength remains positive but momentum continues to deteriorate. The sector will need renewed buying interest before its relative outlook can improve meaningfully.
- Materials (XLB) continue to occupy the Weakening quadrant and remain one of the more vulnerable cyclical sectors on the chart. Although some stabilisation has emerged in recent periods, momentum remains insufficient to support a rotation back toward leadership.
The Lagging Quadrant (Underperformers)
- Information Technology (XLK) remains firmly positioned within the Lagging quadrant. While Technology delivered a strong daily performance during the latest session, the RRG continues to indicate that the sector is underperforming the broader market on a relative basis. Additional evidence of improving momentum will be required before a sustainable recovery can be confirmed.
- Energy (XLE) also remains within the Lagging quadrant. However, unlike Technology, the sector is beginning to display signs of improving momentum as its trajectory moves higher within the quadrant. This suggests that relative performance may be stabilising, although further improvement is necessary before Energy can transition into Improving.
Strategic Summary
The latest RRG profile continues to favour defensive leadership, with Health Care and Utilities maintaining their positions as the market's strongest sectors on both a relative strength and momentum basis. Meanwhile, Communication Services and Consumer Discretionary have emerged as the most promising improving sectors, signalling that investor confidence may gradually be broadening beyond traditional defensive industries.
The concentration of Industrials, Financials, Consumer Staples, Real Estate, and Materials within the Weakening quadrant suggests that momentum remains under pressure across a large portion of the market. At the same time, Technology and Energy continue to lag on a relative basis, although Energy's improving trajectory warrants close monitoring.
Overall, the sector rotation landscape remains defensive but is showing early signs of selective improvement. If current trends continue, Communication Services and Consumer Discretionary may become the next sectors to challenge for leadership, potentially broadening participation within the ongoing market advance.

 Nov 20, 2026


 Please wait processing your request...