
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Materials Take Market Leadership: Materials (XLB) surged 1.25%, making it the strongest-performing sector as investors increased exposure to commodity and manufacturing-related companies.
- Consumer Staples Deliver Unexpected Strength: Consumer Staples (XLP) gained 1.11%, reflecting renewed demand for defensive sectors despite broader market optimism.
- Communication Services Continue Higher: Communication Services (XLC) advanced 1.02%, supported by strength across media, internet, and digital advertising businesses.
- Broad-Based Market Participation: Ten of eleven sectors finished in positive territory, highlighting widespread investor confidence across the market.
- Defensive and Cyclical Sectors Advance Together: Utilities (XLU), Real Estate (XLRE), Industrials (XLI), and Energy (XLE) all posted gains, indicating balanced market participation.
- Health Care Underperforms: Health Care (XLV) fell 0.82%, making it the weakest-performing sector as investors rotated toward sectors offering stronger near-term growth opportunities.
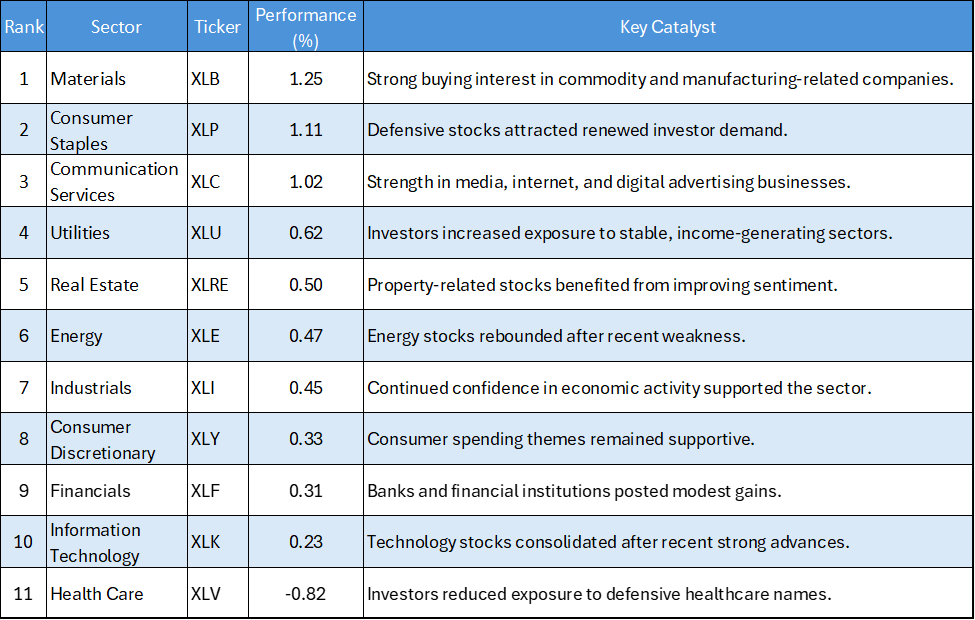
The US equity market delivered another constructive session on July 10, 2026, with most sectors recording gains. Materials, Consumer Staples, and Communication Services led the advance, while Utilities, Real Estate, Industrials, and Energy also participated. The broad nature of the rally suggests investor confidence remains firm, with capital flowing into both defensive and cyclical sectors. Health Care was the only sector to record a notable decline, reflecting a shift in investor preferences toward areas offering stronger momentum.
Daily US Sector Performance Summary
Key Market Themes
Materials Lead the Market
- Materials (XLB) delivered the strongest performance of the session, gaining 1.25%. The advance suggests investors remain optimistic about demand for commodities, industrial inputs, and manufacturing activity. Strong buying interest in resource and materials-related companies highlights confidence in the broader economic outlook.
Communication Services Extend Their Advance
- Communication Services (XLC) rose 1.02%, continuing the sector's recent positive momentum. Strength across digital advertising, media, and internet-related businesses reflects ongoing investor interest in growth opportunities beyond the traditional technology sector. The sector's performance reinforces confidence in earnings growth across the broader communication ecosystem.
Defensive Sectors Return to Favour
- Consumer Staples (XLP) gained 1.11%, while Utilities (XLU) climbed 0.62%. The strong performance of these traditionally defensive sectors suggests investors continue to seek balance within portfolios despite the market's positive tone. Stable earnings profiles and reliable cash flows remain attractive in an environment of ongoing economic uncertainty.
Real Estate and Energy Recover
- Real Estate (XLRE) advanced 0.50%, while Energy (XLE) gained 0.47%. Both sectors recovered following recent periods of weakness. The gains indicate improving investor confidence toward interest-rate-sensitive assets and energy-related opportunities. Although advances were modest, the positive performance contributes to the broader market's constructive tone.
Consumer and Financial Sectors Hold Firm
- Consumer Discretionary (XLY) rose 0.33%, while Financials (XLF) added 0.31%. The gains suggest investors remain comfortable maintaining exposure to economically sensitive sectors. Continued participation from consumers and financial institutions supports the view that market sentiment remains broadly positive.
Technology Consolidates While Health Care Weakens
- Information Technology (XLK) edged 0.23% higher, underperforming the broader market after leading recent rallies. The modest gain likely reflects consolidation rather than a deterioration in sentiment toward technology stocks. Meanwhile, Health Care (XLV) declined 0.82%, making it the weakest-performing sector as investors rotated toward sectors offering stronger momentum and cyclical exposure.
Bottom Line
The July 10 session reflected broad-based strength across the US equity market, with ten of eleven sectors finishing higher. Materials, Consumer Staples, and Communication Services led the advance, while participation from Utilities, Real Estate, Energy, Industrials, and Financials highlighted improving market breadth.
Unlike the previous session, where growth-oriented sectors dominated, the latest performance suggests investors are adopting a more balanced approach by allocating capital across both defensive and cyclical sectors. If this broad participation continues, the market's underlying trend could remain well-supported, with Materials and Communication Services emerging as important drivers of near-term performance.

 Nov 10, 2026
 Please wait processing your request...