
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks rallied on Wednesday, with the S&P 500 rising 1.6%, the Dow gaining 1,569 points to a two-month high and the Nasdaq advancing 0.9%. Democratic gains in Congress fuelled expectations of political gridlock and reduced tensions with Iran, driving oil prices lower and supporting stocks and bonds. Financials led gains, with JPMorgan rising 4.2% and Berkshire Hathaway adding 3.9%, while Microsoft surged 6.7%. Chipmakers declined amid concerns over tighter AI-sector regulation.
Market Movers
Among the top-performing stocks of the session Ohmyhome Limited surged 432.53%, while Cricut, Inc. rallied 48.74%. On the losing side, Ping An Biomedical Co., Ltd. fell 40.93%, while Nurix Therapeutics, Inc. declined 38.23%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded near USD 88 per barrel and Brent around USD 95 on Thursday after both plunged nearly 9% to two-month lows in the previous session. A Democratic sweep in the US midterm elections raised expectations of greater pressure on the Trump administration to end the Iran conflict and potential restrictions on military funding. Recovering Persian Gulf exports and Supply exceeding near-term Demand added to downward pressure, leaving both benchmarks approximately 16% lower for the week.
Gold rose toward USD 4,150 per ounce, reaching two-week highs, while silver approached USD 53 on Thursday, supported by a weaker US dollar and declining Treasury yields. Democratic victories in the US midterm elections strengthened hopes for an end to the US–Iran conflict, driving oil prices sharply lower and easing Inflation concerns. Investors awaited Friday’s US employment report for clues on Federal Reserve policy, with markets pricing in a 79% probability of a December rate hike.
Macro Updates
US Job Cuts Remain Subdued Despite Modest Monthly Increase
US employers announced 43,994 job cuts in October 2026, up 2% from September but down 71% year-on-year, marking the lowest October total since 2023. Food companies led monthly reductions, followed by technology and services. Year-to-date cuts fell 44% to 617,189, the lowest comparable total since 2022, although technology-sector cuts rose 21% to 171,501. Employers continued retaining existing workers while favouring temporary seasonal hiring to meet holiday demand.
Dollar Weakens as Election Outcome Eases Uncertainty
The US dollar index fell to around 101.3 on Thursday as Democratic gains in the midterm elections eased political uncertainty and supported global equities. Expectations of political gridlock and a reduced likelihood of renewed US strikes on Iran pushed oil prices lower and weakened safe-haven demand for the dollar. Investors awaited Friday’s US employment report, with markets pricing in a 79% probability of a December Federal Reserve rate hike.
Bonds Commentary
The US 10-year Treasury Yield fell to around 4.85% on Thursday, its lowest in nearly two months, as the Democrats’ midterm election victory eased political uncertainty and supported bond demand. Expectations of political gridlock and reduced prospects of further US strikes on Iran drove oil prices lower, easing inflation concerns and expectations of aggressive monetary tightening. Investors awaited Friday’s US employment report, with markets pricing in a 79% probability of a December Fed rate hike.
Futures Update
US stock futures were mixed on Thursday, with Dow futures rising 0.5% and Nasdaq 100 futures falling 0.8% as concerns over tighter data centre regulation following the Democrats’ election victory weighed on technology stocks. AppLovin surged 20% after hours on strong Earnings and upbeat guidance. This followed Wednesday’s rally, when the Dow gained 3.03%, the S&P 500 rose 1.58% and the Nasdaq advanced 1.44%. Investors awaited earnings from ConocoPhillips, Kimberly-Clark and Airbnb.
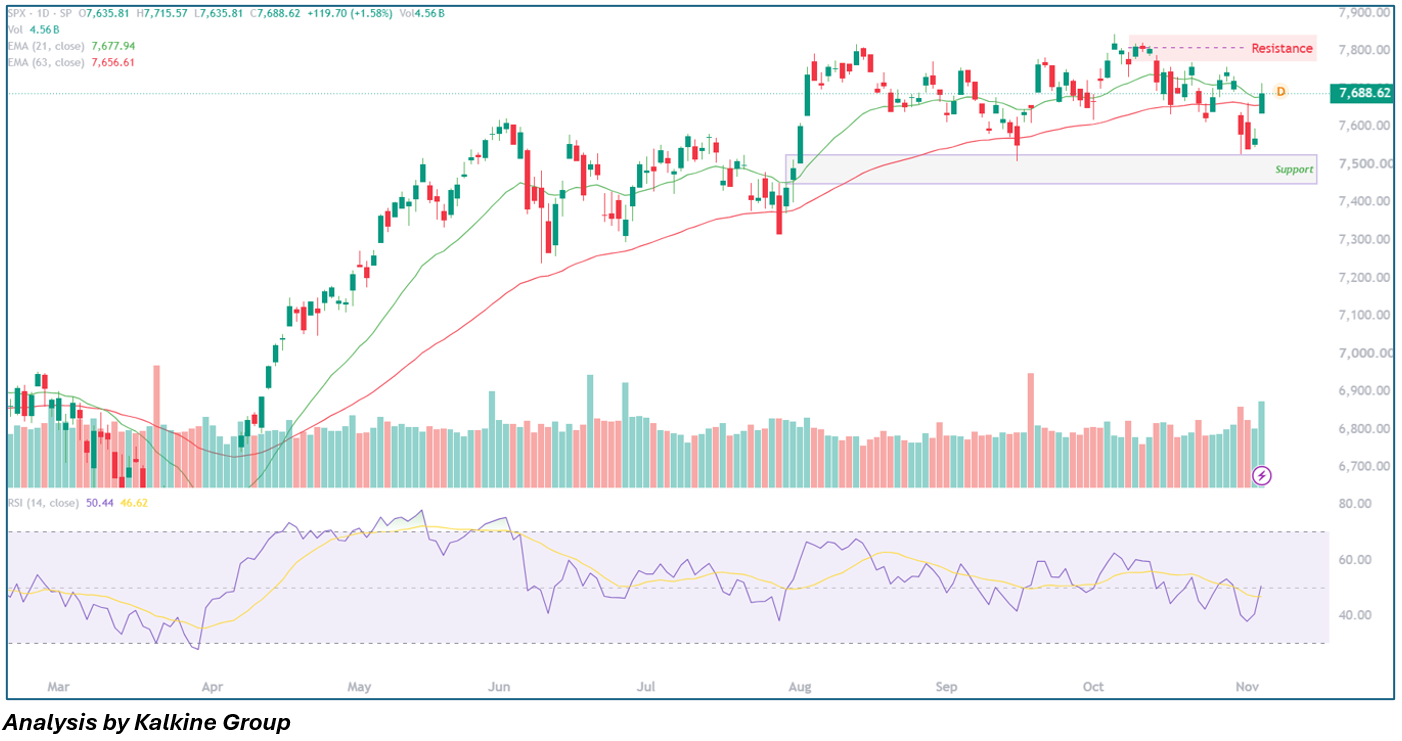
U.S. equities rebounded sharply on broad-based buying, with the Dow hitting a two-month high and major averages holding substantial gains despite a late-session pullback. The S&P 500 Index (SPX) confirmed an intraday bullish reversal, surging +1.58% (+119.70 pts) to 7,688.62 on an elevated Volume spike of 4.56B shares after defending key structural support at 7,450–7,500. By slicing back above both its 63-day EMA (7,656.61) and 21-day EMA (7,677.94) alongside the 14-day RSI crossing above its signal line to 50.44, technical posture favors further upside; sustaining above 7,677.94 keeps the focus on retesting the 7,715.57 session peak and primary overhead resistance at 7,800.00–7,820.00.

 Nov 11, 2026
 Please wait processing your request...