
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks rebounded on Monday as investors bought chipmakers after last week’s selloff. The Nasdaq led with a 2.7% gain, the S&P 500 rose 2.3% and the Dow added 1,104 points. AMD surged 13.3% after Oppenheimer upgraded the stock to outperform, while Applied Materials climbed 11.4% ahead of earnings. Nvidia bucked the sector rally, falling 4.3%. Among major technology companies, Meta gained 5.1%, Amazon rose 2.9% and Microsoft advanced 2.7%
Market Movers
Among the top-performing stocks of the session Ohmyhome Limited. surged 251.09%, while Wellchange Holdings Company Limited. rallied 92.18%. On the losing side, Onconetix, Inc. fell 48.49%, while Faeth Therapeutics, Inc. declined 42.49%, making them the weakest performers during the trading day.
Commodities Update
US crude fell below USD 86 per barrel and Brent slipped below USD 91 on Tuesday, both reaching their lowest levels since late August after Monday’s declines of 4.4% and 5.9%, respectively. Prospects for a diplomatic resolution improved after President Trump signalled that further US strikes on Iran may be unnecessary. Recovering exports also weighed on prices, as increased tanker traffic through the Strait of Hormuz brought Middle Eastern oil shipments close to pre-war levels despite continued attacks on shipping.
Gold eased to around USD 4,120 per ounce and silver slipped towards USD 53 on Tuesday ahead of a key US Inflation report. Markets priced in an 84% chance of a December Federal Reserve rate hike, up from roughly 74% a week earlier, weighing on both metals. Gold and silver had gained nearly 2% and 3%, respectively, on Monday as hopes of a US–Iran peace agreement drove oil prices lower, easing concerns about inflation and the need for further rate hikes.
Macro Updates
US Small Business Optimism Edges Lower in October as Tax Concerns Rise
The NFIB Small Business Optimism index slipped to 97.8 in October 2026 from 97.9 in September, its lowest reading since June but slightly above the 97.7 forecast. Labour quality or availability remained the top concern for the fourth consecutive month, cited by 25% of owners. Taxes ranked second at 21%, the highest share since May 2021. The six-month outlook improved after two months of decline, with a net 8% of owners expecting better business conditions, up 2 percentage points from September.
US Inflation Expected to Slow in October as Gasoline Prices Ease
US consumer prices are forecast to rise 0.3% in October 2026, half September’s 0.6% monthly increase, as gasoline prices are expected to fall 0.9%. Core CPI growth is also projected to slow to 0.2% from 0.3%. The Bureau of Labor Statistics will likely omit annual headline and Core Inflation rates because the federal shutdown disrupted data collection in October 2025. The Cleveland Fed’s model estimates annual headline inflation at 3.7% and core inflation at 2.5%.
US Dollar Index Holds Near 101.7 Ahead of October Inflation Data
The US Dollar Index held near 101.7 on Tuesday after Monday’s decline, as investors awaited October CPI data expected to show slower monthly increases in both headline and core prices. Stronger-than-expected jobs data lifted the market-implied probability of a December Fed rate hike to 84% from around 74% a week earlier. Meanwhile, hopes for a US–Iran peace agreement weighed on oil prices and reduced Demand for the dollar as a safe haven.
Bonds Commentary
The US 10-year Treasury Yield held near 4.88% on Tuesday, close to a two-month low, as investors awaited October CPI data expected to show slower monthly increases in both headline and core prices. Stronger-than-expected jobs data lifted the market-implied probability of a December Fed rate hike to 84% from about 74% a week earlier. Meanwhile, falling oil prices amid hopes for a US–Iran peace agreement eased inflation concerns.
Futures Update
US Equity futures were mixed on Tuesday after Monday’s rebound. S&P 500 futures were flat, Dow futures rose 0.4% and Nasdaq 100 futures edged lower. Anthropic’s planned IPO, which could raise up to USD 90 billion at a valuation of around USD 1 trillion, kept AI stocks in focus. Investors awaited October inflation data, with consumer prices expected to rise 0.3% month over month. Falling energy prices tempered expectations for further Fed rate hikes next year, while JPMorgan and Citigroup each gained 1% in premarket trading.
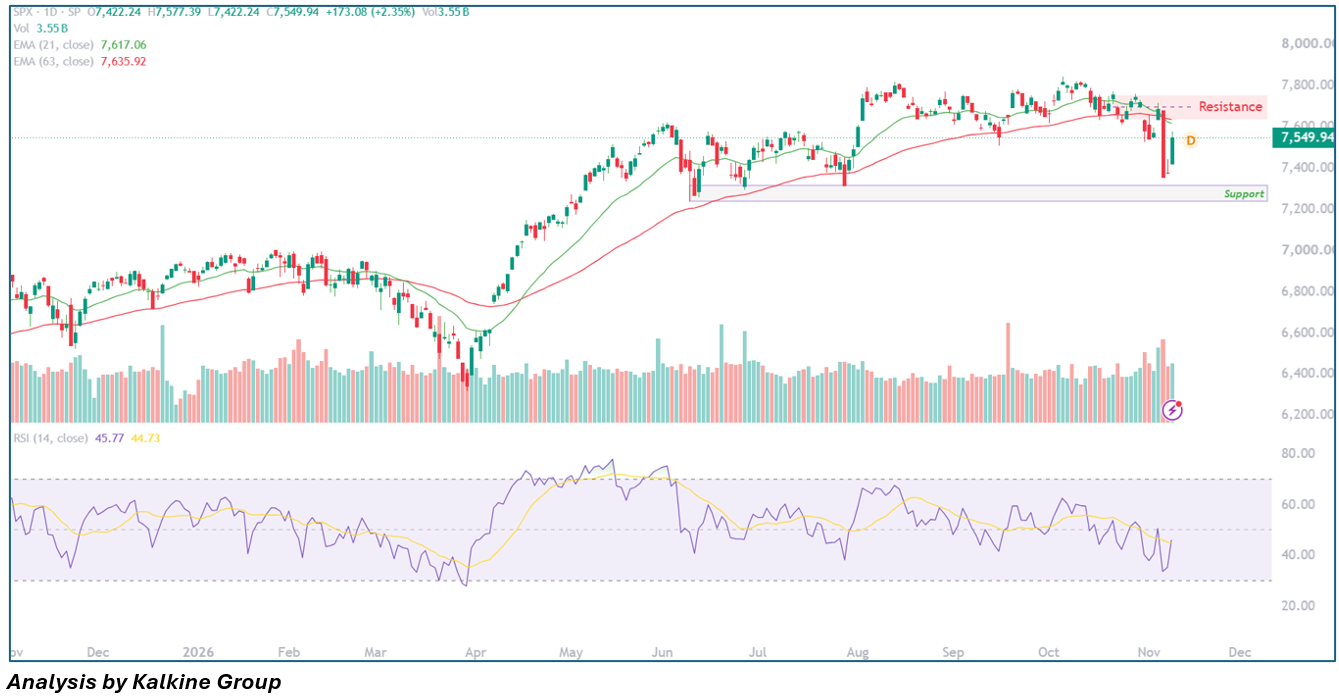
The S&P 500 Index (SPX) is transitioning into a broader consolidation regime, trading at 7,549.94 (+2.35% / +173.08 pts) as price action remains bounded within a well-defined macro bracket between the multi-month structural support shelf (7,240.00–7,320.00) and established overhead resistance (7,680.00–7,730.00). While today’s session low of 7,422.24 successfully defended the lower boundary, the index remains capped beneath dynamic resistance at the converging 21-day EMA (7,617.06) and 63-day EMA (7,635.92). The 14-day RSI is hovering in neutral territory at 45.77 (crossing its 44.73 signal line), and daily Volume of 3.55B shares reflects orderly range rotation rather than an aggressive directional expansion. As long as price remains boxed within 7,320.00 and 7,635.00, choppy two-way trading and mean-reversion swings are likely to persist, with a decisive daily close outside this corridor required to confirm either a fresh bullish leg or renewed distribution.

 Nov 13, 2026
 Please wait processing your request...