
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Thursday as Nvidia’s Leadership turmoil and rising oil prices weighed on sentiment. The S&P 500 and Nasdaq each slipped 0.3%, while the Dow lost 189 points. Nvidia fell 4.3% after reports of CEO Jensen Huang’s departure. Chip stocks were mixed, with Micron and Intel declining while AMD rose 5.9% and Broadcom gained 5.5%. Higher oil prices revived Inflation concerns and lifted Treasury yields as investors anticipated faster Fed rate hikes.
Market Movers
Among the top-performing stocks of the session Phaos Technology Holdings (Cayman) Limited. surged 234.18%, while Exascale Labs Holdings Inc. rallied 118.27%. On the losing side, Cardinal Infrastructure Group Inc. fell 62.37%, while SMX (Security Matters) Public Limited Company. declined 56.75%, making them the weakest performers during the trading day.
Commodities Update
US crude held above USD 88 per barrel and Brent traded near USD 96 on Friday after both rose in the previous session. President Trump dampened hopes for a diplomatic breakthrough by saying the US no longer needed a deal with Iran and directing Vice President JD Vance to focus on domestic issues. Tehran reiterated that Washington must lift its naval blockade and sanctions before direct talks can begin. Both benchmarks remained on track for a second consecutive weekly decline as Middle Eastern crude exports recovered and the Democratic midterm victory sustained hopes for a quicker resolution.
Gold rebounded above USD 3,900 per ounce on Friday after three sessions of losses, while silver recovered above USD 50 per ounce. Both remained on track for weekly declines as hotter-than-expected US inflation and hawkish Federal Reserve comments lifted the dollar and Treasury yields. Markets priced in an 85% chance of a 25-basis-point rate hike in December and a 15% chance of a 50-basis-point increase, with traders increasingly expecting further hikes next year. A recovery in oil prices after President Trump said the US no longer needed a deal with Iran added pressure on gold.
Macro Updates
US Producer Inflation Expected to Ease Monthly but Accelerate Annually
US producer prices are forecast to rise 0.4% in October 2026, down from 1.3% in September as energy price pressures ease. Core producer prices, which exclude food and energy, are expected to rise 0.3%, down from 0.7%. On an annual basis, headline inflation is projected to reach 6.6%, its highest level since November 2022, while Core Inflation is forecast to hold at 5%.
US Dollar index Holds Above 103 as Fed Rate Hike Expectations Rise
The US Dollar Index held above 103 on Friday after three consecutive gains took it to its highest level since April 2025. Stronger-than-expected US inflation and hawkish Fed comments led markets to price in an 85% chance of a 25-basis-point hike in December and a 15% chance of a 50-basis-point increase. Investors awaited US producer price data, while renewed uncertainty over US-Iran negotiations supported safe-haven Demand for the dollar.
Bonds Commentary
The 10-year US Treasury Yield held above 5.1% on Friday, near a three-week high, as stronger-than-expected US inflation and hawkish Fed remarks raised expectations for faster rate hikes. Markets priced in an 85% chance of a 25-basis-point hike in December and a 15% chance of a 50-basis-point increase. Higher oil prices added upward pressure on yields as investors awaited US producer price data.
Futures Update
US stock futures rose 0.2% to 0.6% on Friday after Wall Street’s major indexes fell on Thursday. Nvidia shares rebounded more than 1% in after-hours trading following the reported resignation of CEO Jensen Huang, with CFO Colette Kress named interim CEO. Investors awaited October’s US producer price report after stronger-than-expected consumer inflation and hawkish Fed remarks raised expectations for more aggressive rate hikes.
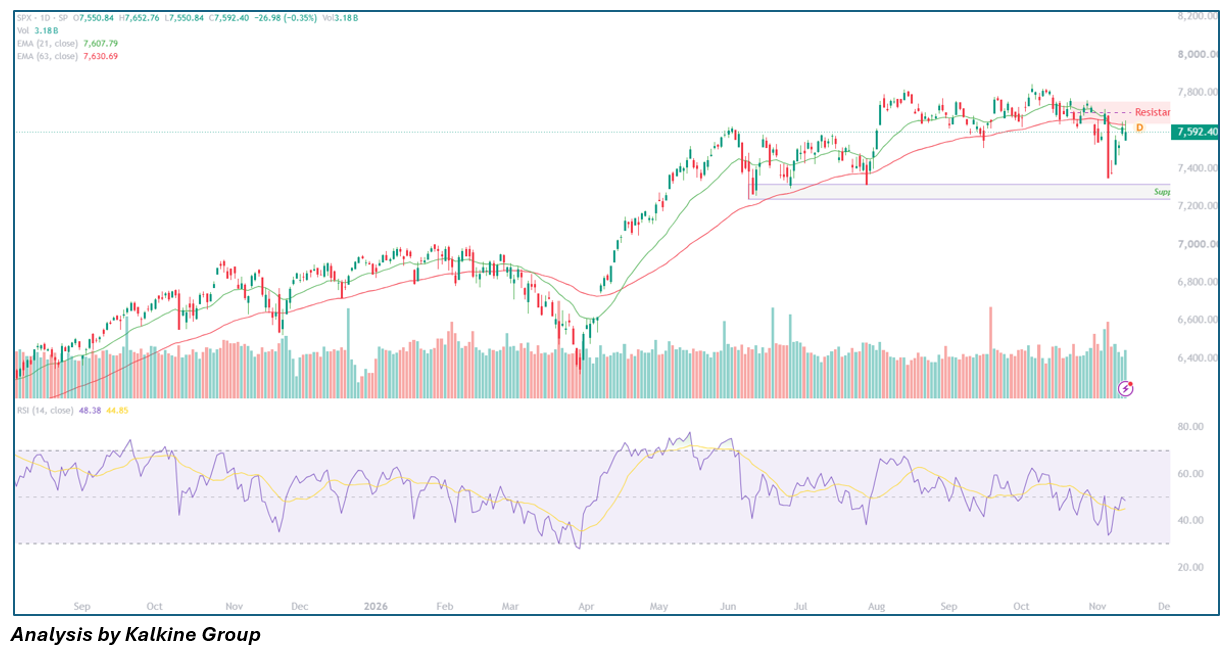
The S&P 500 Index (SPX) displays an intraday bearish rejection setup, slipping -0.35% (-26.98 pts) to trade at 7,592.40 after opening at 7,550.84 (also the session low) and facing sharp overhead rejection at an intraday peak of 7,652.76 on steady Volume of 3.18B shares. The upper wick rejection off 7,652.76 confirms sellers defending the heavy confluence of dynamic resistance at the 63-day EMA (7,630.69) and the multi-month Supply ceiling pegged between 7,650.00 and 7,730.00, pushing spot back below the 21-day EMA (7,607.79). Upward recovery momentum is stalling beneath the neutral threshold as the 14-day RSI rolls over slightly to 48.38 (above its 44.85 signal line), signaling fading buyer follow-through. While price remains capped below the 7,630.69–7,652.76 resistance cluster, the intraday path of least resistance favors a corrective pullback toward the 7,550.84 session low and psychological support at 7,500.00, with a decisive breakdown exposing a deeper retest of the primary demand zone near 7,240.00–7,320.00.

 Nov 18, 2026
 Please wait processing your request...