
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Monday as chipmakers led the selloff. The Nasdaq fell 2.7%, the S&P 500 declined 1.9% and the Dow lost 740 points. Nvidia fell 4.1% amid uncertainty over its Leadership ahead of Tuesday’s earnings, which investors will scrutinize for details on its AI investments and financing commitments. Micron dropped 7.6%, Intel fell 7.1% and AMD lost 5.6%. Anthropic’s IPO was reportedly six times oversubscribed ahead of its expected Thursday debut. Treasury prices rose as investors sought safety, while oil prices declined.
Market Movers
Among the top-performing stocks of the session Global Mofy AI Limited. surged 97.06%, while Akanda Corp. rallied 62.50%. On the losing side, Mannatech, Incorporated. fell 40.32%, while Focus Universal Inc. declined 33.33%, making them the weakest performers during the trading day.
Commodities Update
WTI and Brent Crude pared earlier losses on Tuesday to trade near USD 86 and USD 93 per barrel, respectively, as a second tanker strike off Oman and an Iranian drone attack on a US radar installation in Bahrain raised concerns about regional oil flows. Recovering Middle Eastern exports and Washington’s decision to hold off on further strikes against Iran limited the rebound. The International Energy Agency expects global Supply to exceed Demand by around 2 million barrels per day this quarter, while Goldman Sachs warned of a potential glut next year.
Gold traded near USD 3,850 per ounce on Tuesday, close to its lowest level since September 2025, while silver hovered near a one-year low of USD 47 per ounce. A stronger US dollar and elevated Treasury yields weighed on both metals after October Inflation exceeded expectations. Cleveland Fed President Beth Hammack backed gradual rate increases but said stronger inflation could Warrant larger hikes. Markets priced in a greater than 95% chance of a 25-basis-point hike in December as investors awaited Wednesday’s release of the October Fed meeting minutes.
Macro Updates
US Dollar Hits Highest Level Since April 2025 as Rate Hike Expectations Rise
The US dollar index climbed above 103.5 on Tuesday after stronger-than-expected October inflation and hawkish Federal Reserve comments reinforced expectations of further tightening. Markets priced in a greater than 95% chance of a 25-basis-point hike in December and anticipated four additional increases by September 2027. The dollar gained most against the euro and the Australian and New Zealand dollars, with the New Zealand dollar approaching levels last seen in 2009.
Bonds Commentary
The US 10-year Treasury Yield eased to 5.1% on Tuesday, extending Monday’s decline as investors sought safety ahead of Nvidia’s earnings. Markets priced in a nearly 95% chance of a 25-basis-point Fed rate hike in December and anticipated further increases in January and April. Cleveland Fed President Beth Hammack favored gradual hikes but said stronger inflation could warrant larger moves. Investors awaited Wednesday’s release of the October Fed meeting minutes for further guidance.
Futures Update
US stock futures were mixed on Tuesday, with Nasdaq 100 futures rising while Dow and S&P 500 futures slipped ahead of Nvidia’s Earnings and Anthropic’s market debut. On Monday, the Nasdaq Composite fell 2.49%, the S&P 500 lost 1.92%, and the Dow declined 1.41%. Nvidia dropped 4.1% following CEO Jensen Huang’s departure, while SanDisk, Micron and AMD fell 8.6%, 7.6% and 5.6%, respectively. Reports that the US and its allies had agreed to limit China’s remote access to advanced AI chips and servers added pressure on the sector.
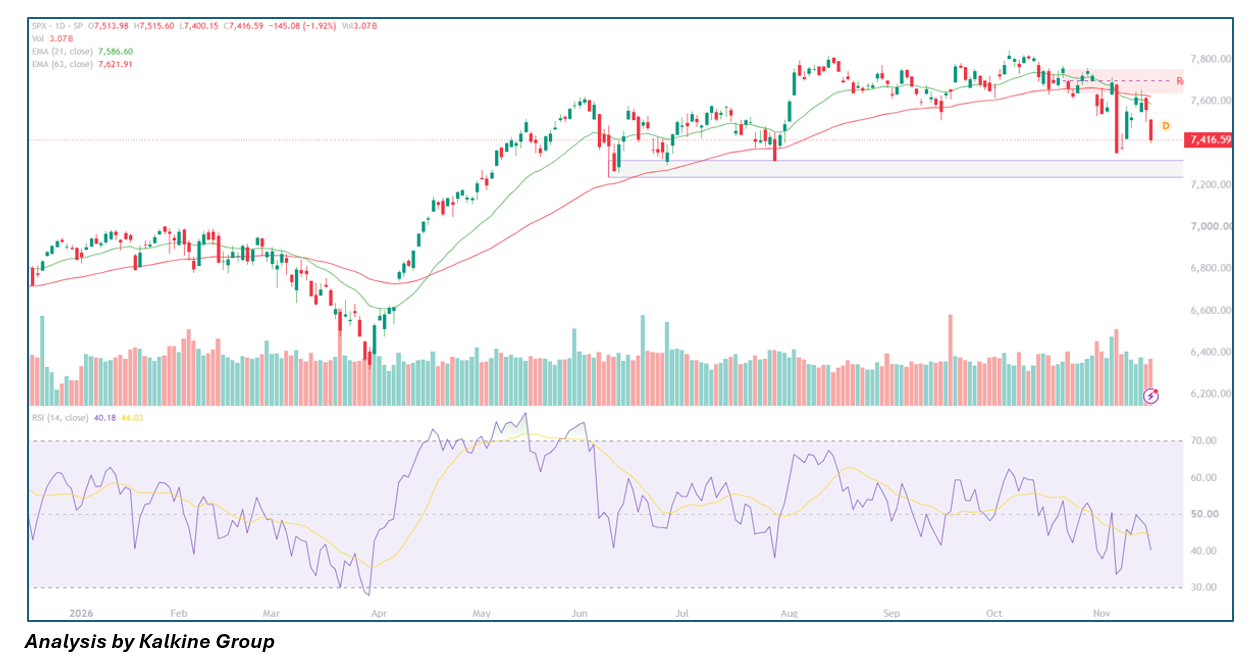
The S&P 500 Index (SPX) exhibits a sharp intraday bearish breakdown bias, tumbling -1.92% (-145.08 pts) to trade at 7,416.59 after Gapping down at the open to 7,513.98, stalling immediately at a session peak of 7,515.60, and sliding toward an intraday low of 7,400.15 on elevated distribution Volume of 3.07B shares. The decisive wide-range red candle confirms a clean rejection from the overhead Moving Average cluster—leaving spot well below both its 21-day EMA (7,586.60) and 63-day EMA (7,621.91)—and slicing straight through the 7,500.00 psychological support pivot. Downward momentum has accelerated noticeably as the 14-day RSI drops to 40.18 (crossing below its 44.03 signal line), reflecting intensifying selling pressure with room before reaching oversold extremes. While price remains capped below the broken 7,500.00–7,515.60 resistance zone, the intraday path of least resistance favors further downside continuation to test the primary multi-month demand shelf pegged between 7,240.00 and 7,320.00.

 Nov 15, 2026
 Please wait processing your request...