
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
A rebound in chipmakers lifted the Nasdaq 1.3% and the S&P 500 0.3% on Friday, while the Dow fell 237 points. AMD jumped 11%, Micron gained 5.1% and Nvidia rose 2.8% after concerns over tighter AI regulation following Democratic midterm gains pushed the Nasdaq into correction territory in the previous session. US Payroll growth exceeded forecasts and Unemployment edged lower. For the week, the Nasdaq fell 5.5%, the S&P 500 lost 3.2% and the Dow declined 1.7%.
Market Movers
Among the top-performing stocks of the session STAK Inc. surged 82.12%, while Gogo Inc. rallied 71.52%. On the losing side, Biodesix, Inc. Ltd. fell 57.01%, while Starling Oncology, Inc. declined 45.97%, making them the weakest performers during the trading day.
Commodities Update
US crude fell below USD 89 per barrel and Brent slipped towards USD 95 on Monday, extending the previous week’s declines of 12.8% and 13.3%, respectively. President Trump said a strong deal with Iran could avert extensive US strikes, though Secretary of State Marco Rubio tempered expectations for a breakthrough. Persian Gulf crude exports began to recover despite a reported US strike on Iran’s Qeshm Island, a reported tanker strike near the Strait of Hormuz and a Houthi attack on Saudi Aramco offices in Riyadh.
Gold rose above USD 4,100 per ounce and silver climbed above USD 53 on Monday, extending last week’s gains as lower oil prices eased Inflation concerns. Stronger US Job Growth in October and a drop in unemployment to 4.1% limited further gains by raising expectations of a Federal Reserve rate hike. Markets priced in an 81% chance of a quarter-point increase by year-end, up from 71% before the jobs report, as investors awaited this week’s US inflation data.
Macro Updates
US Dollar index Slips Below 102 Ahead of Inflation Data
The US Dollar Index fell below 102 on Monday, giving back some of the previous session’s gains. US payrolls rose by 165,000 against a forecast of 65,000, and unemployment fell to 4.1%, lifting the market-implied probability of a December Fed rate hike from 71% to 81%. San Francisco Fed President Mary Daly said further hikes may be needed. Investors now await Tuesday’s consumer price data and Friday’s producer price figures.
US Consumer Credit Rises More Than Twice as Much as Forecast in September
US consumer credit rose by USD 27.84 billion in September 2025, exceeding the USD 12 billion forecast and accelerating from August’s upwardly revised USD 8.28 billion increase. Revolving credit, including credit card debt, reached USD 1.37 trillion, while nonrevolving credit, including auto and student loans, reached USD 3.86 trillion. Total consumer credit rose 6.4% year on year.
Bonds Commentary
The US 10-year Treasury Yield steadied near 4.85% on Monday after payrolls rose by 165,000 against a forecast of 65,000 and unemployment fell to 4.1%. The market-implied probability of a December Fed rate hike rose to 81% from 71%, while a rebound in global equities reduced Demand for safe-haven bonds. Investors now await Tuesday’s consumer price data and Friday’s producer price figures.
Futures Update
Dow futures rose 0.3% on Monday, while S&P 500 futures slipped 0.1% and Nasdaq 100 futures fell 1%. Investors awaited Tuesday’s consumer price report and Friday’s producer price data for clues on the Fed’s next move. Earnings from CoreWeave, Cisco and Applied Materials could shed light on demand for AI infrastructure after concerns over tighter regulation and slower data centre expansion weighed on tech stocks last week.
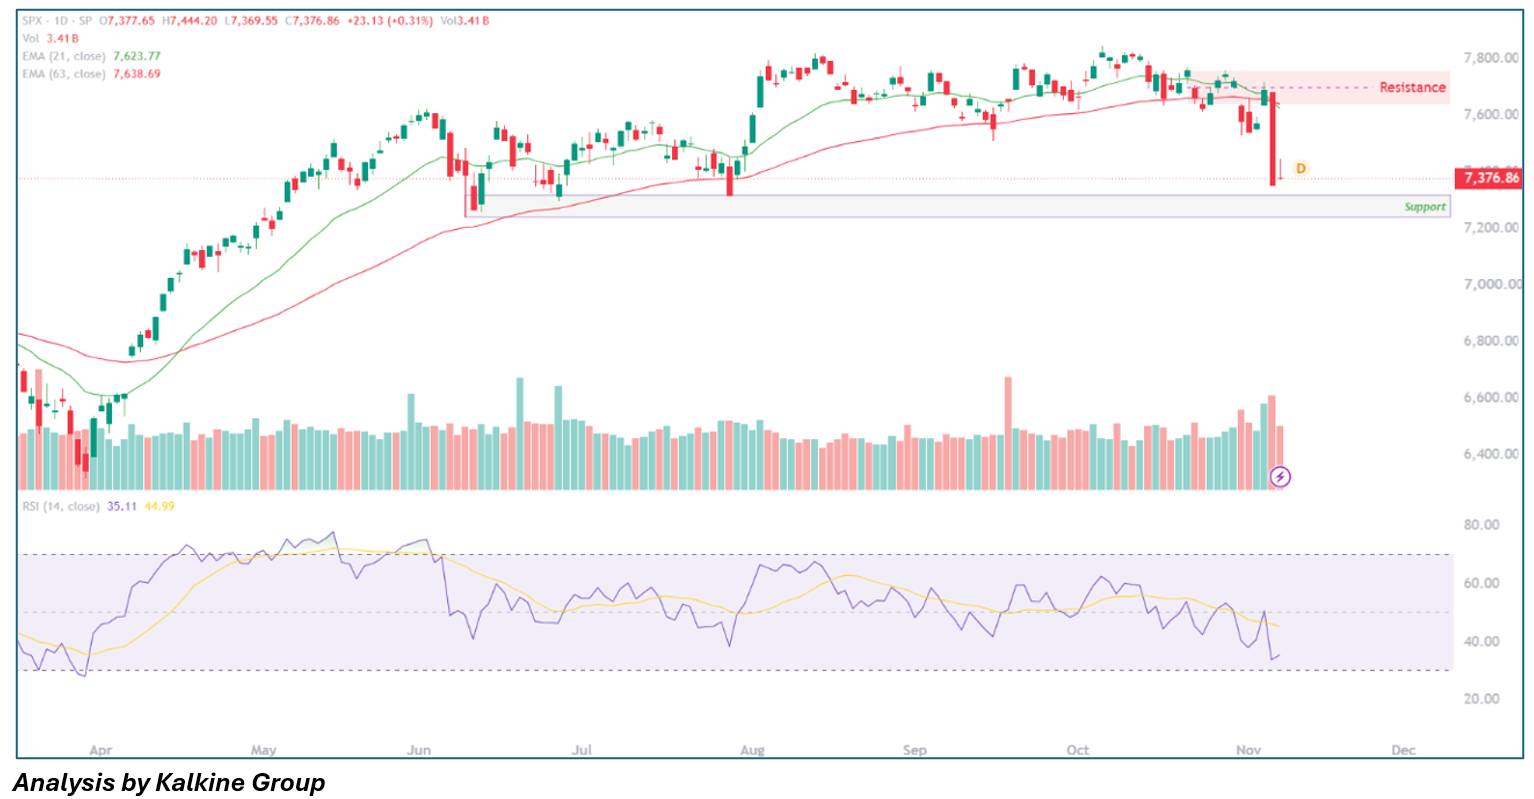
The S&P 500 Index (SPX) displays tentative signs of intraday stabilization and an emerging oversold mean-reversion setup, edging higher by +0.31% (+23.13 pts) to trade at 7,376.86 after opening at 7,377.65, testing an intraday high of 7,444.20, and defending a session low of 7,369.55 on moderate Volume of 3.41B shares. The price action marks an initial pause following the previous session's steep liquidation, with buyers stepping in just above the multi-month primary horizontal support shelf pegged at 7,240.00–7,320.00. While spot remains pinned well below its descending 21-day EMA (7,623.77) and 63-day EMA (7,638.69), downward momentum is showing early signs of exhaustion as the 14-day RSI begins to flatten at 35.11 near oversold boundaries. Sustaining above the session trough at 7,369.55 and the 7,320.00 structural base favors an oversold relief bounce toward the session high of 7,444.20, with an extension opening the door to challenge intermediate resistance near 7,500.00–7,550.00; conversely, a decisive breakdown below the 7,240.00–7,300.00 demand zone would invalidate this stabilization attempt and expose deeper downside continuation.

 Nov 16, 2026
 Please wait processing your request...