
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks fell on Tuesday as technology weakness and caution ahead of Nvidia’s Earnings weighed on sentiment. The S&P 500 declined 1% to its lowest since July, the Nasdaq slipped 0.7%, and the Dow lost 849 points. Nvidia fell 0.4% amid uncertainty following former CEO Jensen Huang’s ouster, while tighter US restrictions on remote access to advanced AI chips and widespread technical disruptions added pressure. Investors also monitored Anthropic’s IPO, reportedly expected to price at or above the upper end of its range.
Market Movers
Among the top-performing stocks of the session SELLAS Life Sciences Group, Inc. surged 156.36%, while GreenPower Motor Company Inc. rallied 85.82%. On the losing side, Cue Biopharma, Inc. fell 79.93%, while PS International Group Ltd. declined 31.93%, making them the weakest performers during the trading day.
Commodities Update
Crude oil and Brent fell below USD 84 and USD 92 per barrel, respectively, on Wednesday, as concerns over rising global Supply outweighed escalating Middle East tensions. US strikes on an Iranian missile site, heightened Iranian threats and reported mine attacks on four tankers in the Strait of Hormuz increased supply disruption risks. However, the IEA’s projected surplus of around 2 million barrels per day this quarter, Goldman Sachs’ warning of a potential glut next year and a 5.3-million-barrel increase in US crude inventories maintained downward pressure on prices.
Gold fell below USD 3,800 per ounce and silver approached USD 46 on Wednesday, reaching their weakest levels in over a year and a year, respectively, as a stronger US dollar and expectations of further Federal Reserve tightening weighed on precious metals. Markets priced in a nearly 96% probability of a 25-basis-point December rate hike, with investors awaiting FOMC minutes for further guidance. Copper also dropped below USD 5.90 per pound, its lowest since May, pressured by dollar strength, uncertainty surrounding AI infrastructure Investment and rising London Metal Exchange inventories, which reached approximately 320,000 tonnes by mid-November from an August low of 205,000 tonnes.
Macro Updates
Elevated Rates Weigh on US Mortgage Applications
US mortgage applications fell 2.3% in the second week of November, marking their ninth decline in 11 weeks as elevated borrowing costs restrained demand. Persistent Inflation and low Unemployment reinforced expectations of further Federal Reserve rate hikes, putting pressure on bonds and keeping mortgage rates high. Refinancing applications declined 1.5%, while applications to purchase a home dropped 2.5%.
US Dollar Holds Firm on Fed Rate Hike Expectations
The US Dollar index traded near 103.6 on Wednesday, around its strongest level since April 2025, as hawkish Federal Reserve comments reinforced expectations of further rate increases to contain inflation. Markets priced in a nearly 96% probability of a 25-basis-point December hike and a 4% chance of a larger 50-basis-point increase. Investors awaited further Fed remarks and FOMC meeting minutes for policy guidance.
US Crude Inventories Rise Unexpectedly as Production Hits Record
US crude inventories increased by 5.3 million barrels in the week ended November 13, against expectations of a 0.5-million-barrel draw, following a 9-million-barrel build the previous week. Gasoline and distillate stocks rose by 5.1 million and 0.4 million barrels, respectively, while Cushing inventories declined by 1.691 million barrels. Separately, crude production reached a third consecutive weekly record of 14.013 million barrels per day in the week ended November 6, up from 14.003 million.
Bonds Commentary
The US 10-year Treasury Yield eased to around 5.09% on Wednesday but remained near a five-week high as hawkish Federal Reserve comments reinforced expectations of further tightening to curb inflation. Markets priced in a nearly 96% probability of a 25-basis-point December rate hike and a 4% chance of a 50-basis-point increase, while investors awaited further Fed commentary and FOMC minutes for policy guidance.
Futures Update
US stock futures rose on Wednesday as Nvidia’s stronger-than-expected third-quarter earnings and upgraded Revenue outlook lifted confidence in AI demand. Nasdaq 100 futures gained over 1%, while S&P 500 and Dow futures rose 0.7% and 0.3%, respectively. Nvidia climbed more than 4% in after-hours trading, alongside gains exceeding 7% for CoreWeave and 10% for Nebius Group. The rebound followed Tuesday’s declines of 1.65% in the Dow, 1.03% in the S&P 500 and 0.74% in the Nasdaq Composite.
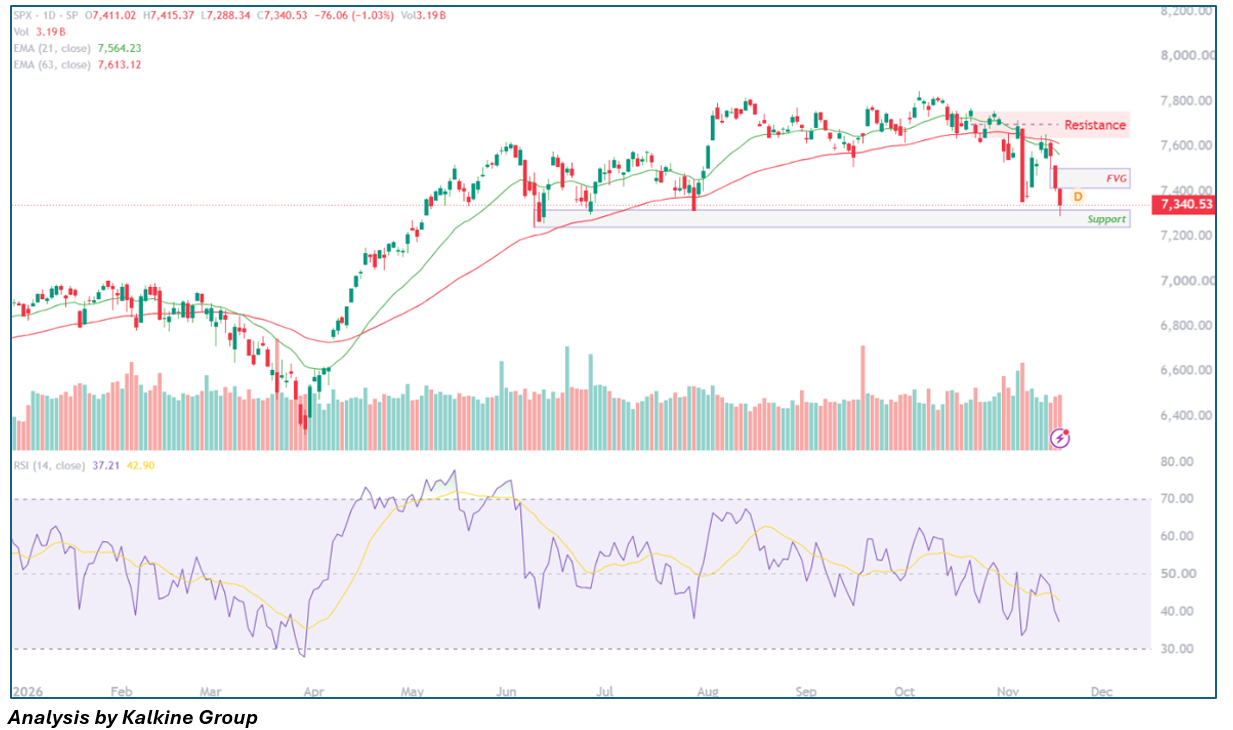
SPX exhibits a volatile intraday bearish-to-stabilization setup, declining -1.03% (-76.06 pts) to trade at 7,340.53 after opening at 7,411.02, stalling immediately near a session high of 7,415.37, and probing a deep intraday low of 7,288.34 on elevated turnover of 3.19B shares. The sharp downward sweep sliced into the primary multi-month Demand shelf (7,240.00–7,320.00), where responsive dip-buying produced a notable lower wick off 7,288.34, though spot remains structurally suppressed beneath a freshly formed overhead Fair Value Gap (FVG near 7,430.00–7,500.00) as well as the descending 21-day EMA (7,564.23) and 63-day EMA (7,613.12). Downside momentum remains heavy as the 14-day RSI slips further into sub-neutral territory at 37.21 (well below its 42.90 signal line), approaching oversold thresholds. While bulls are attempting a tactical defense of the 7,288.34 session low and the broader 7,240.00–7,320.00 support zone, any intraday relief bounce faces stiff supply at the 7,415.37–7,500.00 FVG resistance cluster, whereas a decisive breakdown below 7,240.00 opens deeper downside exposure toward 7,100.00.

 Nov 16, 2026
 Please wait processing your request...