
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
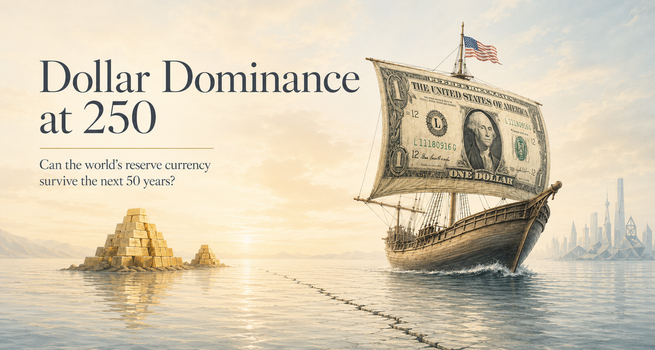
Key Highlights
- The US dollar's share of global foreign exchange reserves stood at 56.8% in late 2025, down from a peak above 70% in 2000, according to IMF data.
- Federal debt held by the public is projected to reach 101% of GDP in 2026, on course to surpass the post-World War Two record by the mid-2030s, per the Congressional Budget Office.
- Central banks bought 863 tonnes of gold in 2025, the fourth-largest annual total on record, and gold has overtaken US Treasuries as the world's largest reserve asset by value.
- BRICS economies are building parallel settlement infrastructure, including the mBridge platform, though local-currency trade settlement remains distinct from displacing the dollar as the primary reserve asset.
- Dollar-pegged stablecoins, now backing over $300 billion in circulation and increasingly used for AI agent-to-agent payments, have made issuers such as Tether structurally significant buyers of US Treasury bills.
Two hundred and fifty years after declaring independence, the United States issues the currency that underwrites the global financial system. That status was not part of the founding design. It emerged in stages, was contested at each transition, and is being tested again. The question worth asking at this anniversary is not whether the dollar will collapse, a framing that overstates the risk, but whether the structural conditions that built its dominance are still being renewed or are quietly eroding.
The Currency That Failed First
The earliest American monetary experiment was a failure. The Continental Congress issued paper currency to finance the Revolutionary War, and by 1781 it had depreciated so completely that the phrase "not worth a Continental" entered the language. The new republic's first lesson in monetary credibility was a negative one.
Alexander Hamilton's response, the assumption of state war debts into federally issued bonds and the chartering of the First Bank of the United States, addressed the credibility gap directly. It created a functioning sovereign credit market where none had existed. This is the same institutional foundation that produced the Buttonwood Agreement in 1792 and the equity markets that financed America's industrial rise. Currency credibility and capital market depth were never separate stories. They built on each other from the outset.
From Gold Standard to Sterling's Shadow
For most of the nineteenth and early twentieth centuries, the dollar was a domestic and regional currency, not a global one. The pound sterling held that position, backed by Britain's trade network and the Bank of England's centrality to international finance. The United States operated under successive gold standard arrangements through the National Banking Acts, but global reserve status required something the country had not yet built: a financial system large and trusted enough for foreign central banks to hold dollar assets at scale.
That changed only after two world wars hollowed out European financial capacity and concentrated gold reserves in American vaults.
Bretton Woods and the Founding of Reserve Status
The dollar's reserve currency status was formally established in July 1944, not 1776. Delegates from 44 countries meeting at Bretton Woods, New Hampshire, agreed to peg their currencies to the dollar, which was in turn convertible to gold at $35 an ounce. This arrangement, combined with the creation of the International Monetary Fund and the World Bank, made the dollar the operating currency of postwar reconstruction.
French finance minister Valéry Giscard d'Estaing later described the result as an "exorbitant privilege": the United States could borrow internationally in its own currency, run external deficits without immediate balance-of-payments pressure, and export dollar liquidity that the rest of the world needed to function. No earlier American institution, not the Buttonwood Agreement, not the SEC, had this kind of structural reach.
The Petrodollar System and the Fiat Era
Bretton Woods could not survive the fiscal demands of the 1960s. In August 1971, President Richard Nixon suspended dollar-gold convertibility, ending the system without immediately ending the dollar's centrality. What replaced commodity backing was a new arrangement built on energy markets. Saudi Arabia and other OPEC members agreed to price oil exports in dollars and recycle proceeds into US Treasury securities, a system that gave the dollar a transactional anchor even after its gold link was severed.
Paul Volcker's disinflation campaign in the early 1980s, though painful domestically, reinforced confidence in the dollar's long-term purchasing power at a moment when that confidence was genuinely in doubt.
Quantitative Expansion and the Post-2008 Order
The 2008 financial crisis originated in dollar-denominated mortgage markets, yet the dollar emerged from it stronger as a safe-haven asset. Federal Reserve balance sheet expansion and a network of central bank swap lines extended dollar liquidity globally during the crisis and again during the 2020 pandemic shock. These episodes demonstrated something structurally important: in moments of acute global stress, demand for dollars rises rather than falls, a pattern that has so far held through every major test since Bretton Woods.
The 2026 Pressure Points
Three structural pressures are now converging, and each is measurable rather than speculative.
The first is reserve composition. IMF data show the dollar's share of global allocated foreign exchange reserves at 56.8% in the fourth quarter of 2025, down from above 70% at the start of this century. The decline has been gradual rather than sudden, and research from the Centre for Economic Policy Research cautions that headline share changes conflate portfolio preference shifts with valuation effects from exchange rate movements. Still, the multi-decade trend line is consistent and has not reversed.
The second is fiscal trajectory. The Congressional Budget Office projects federal debt held by the public will rise from 101% of GDP in 2026 to 120% by 2036, exceeding the prior record of 106% set just after the Second World War. Net interest costs are now the fastest-growing line item in the federal budget. This matters for reserve currency status because confidence in a currency is ultimately confidence in the fiscal capacity standing behind it.
The third is the accelerating return of gold as a reserve asset. Central banks purchased 863 tonnes of gold in 2025, and by late in the year gold had overtaken US Treasuries to become the world's largest reserve asset by value, according to Morgan Stanley Research, the first time that has happened since 1996. Poland, Kazakhstan, and a broadening group of emerging-market central banks have been the largest buyers, a pattern that accelerated after Russia's roughly $300 billion in dollar reserves were frozen following sanctions in 2022. For investors, this dynamic has been visible in the performance of gold mining equities such as Newmont (NYSE:NEM) and in gold-backed exchange-traded products, both of which have benefited from sustained official-sector demand alongside record price levels.
Parallel to this, BRICS economies are building alternative settlement infrastructure. The mBridge platform, a multi-central-bank digital currency system involving China, the UAE, Saudi Arabia, Thailand, and Hong Kong, has moved from pilot to operational transaction volumes. The New Development Bank has targeted 30% of its lending in local currencies. These developments are real, but they should be read precisely: local-currency trade settlement between bilateral partners is a different undertaking from displacing the dollar as the world's primary store of reserve value. No alternative currency currently offers the combination of liquidity, legal predictability, and open capital markets that reserve status requires. The euro carries its own fiscal fragmentation issues, and the renminbi remains subject to capital controls that limit its convertibility.
AI, Stablecoins, and a New Extension of Dollar Dominance
A separate force is moving in the opposite direction from BRICS settlement infrastructure, and it deserves equal weight in any assessment of dollar durability. The rise of AI-driven payments is, so far, reinforcing the dollar's centrality rather than challenging it.
Under the GENIUS Act, signed into law in July 2025, US-regulated stablecoin issuers must back their tokens almost entirely with dollar-denominated reserves, primarily Treasury bills and Treasury-collateralized repurchase agreements. The dollar stablecoin market crossed $300 billion by mid-2026, and the two largest issuers, Tether and Circle, have become structurally significant holders of short-term US government debt. Tether's Treasury exposure alone, at roughly $141 billion, places it among the twenty largest holders of US government debt globally, ahead of several sovereign nations. Research from the Bank for International Settlements has found that stablecoin reserve flows measurably compress short-term Treasury bill yields, a transmission channel that did not exist a decade ago.
This matters because of where the demand is increasingly originating. A growing share of stablecoin volume is now machine-to-machine: autonomous AI agents settling payments for compute, data, and services with minimal human initiation. Industry executives have described this as agentic commerce requiring a programmable medium of exchange, and several platforms now allow AI agents to hold, trade, and settle transactions directly in stablecoins. Because the dominant stablecoins remain dollar-pegged, this emerging layer of AI-driven economic activity is, for the moment, denominated in dollars by default.
A separate line of argument from policy researchers frames US compute access itself as a new lever of dollar-linked influence, comparable to how oil-for-dollars functioned after 1971. Under this framing, nations seeking reliable access to advanced AI infrastructure increasingly transact through dollar-denominated settlement rails, while China's competing strategy pairs its own AI exports with renminbi-settled alternatives. This remains a contested and still-developing argument rather than settled consensus, but it identifies a genuine structural fact: infrastructure choices being made in AI right now are also currency choices, whether or not they are framed that way at the time.
None of this guarantees the pattern holds. Stablecoin regulation remains in its early implementation phase, and a shift toward non-dollar-denominated settlement rails, including renminbi-linked AI payment corridors, remains plausible if Chinese AI exports scale faster than expected. The empirical record through mid-2026, however, points toward AI infrastructure deepening dollar demand through a new channel rather than displacing it, a dynamic that complicates any simple narrative of dollar decline.
The Investment Lens
For investors, the practical implications sit in three places rather than one dramatic outcome. Dollar index movements, tracked through instruments referencing the DXY, remain the most direct read on relative currency strength against a basket of developed-market peers. US Treasury yields increasingly price in fiscal risk alongside monetary policy, meaning foreign holding patterns at note and bond auctions are now a genuine macro indicator rather than a technical footnote. And companies with substantial non-dollar revenue exposure face a structurally different earnings translation environment than they did a decade ago, a dynamic that cuts both ways depending on whether the dollar trends weaker or stronger from current levels.
None of this implies an imminent rupture. Triffin's dilemma, the structural tension first identified by economist Robert Triffin in 1960, holds that a reserve currency issuer must run persistent deficits to supply the world with liquidity, while those same deficits eventually undermine confidence in the currency itself. The dollar has managed this tension for eight decades through the depth and openness of US capital markets, advantages that remain largely intact even as their margin narrows.
The Structural Question at 250
The pattern across 250 years is that the dollar's dominance has never been static. It was built in stages, defended through crises, and renegotiated at each major economic transition, from gold standard to Bretton Woods, from petrodollar recycling to quantitative expansion. What is different in 2026 is that, for the first time since the 1970s, multiple structural pressures, fiscal, geopolitical, and monetary, are moving in the same direction simultaneously rather than in isolation. Whether US institutional depth can absorb that convergence the way it has absorbed prior ones is the open question of the next half-century. History suggests the dollar's advantages erode slowly, if at all. It also suggests that slow erosion, left unaddressed, is how reserve currencies have changed hands before.
This article has been produced for informational purposes only and does not constitute financial advice, investment recommendations, or an offer or solicitation to buy or sell any securities. Readers should conduct their own due diligence and consult a licensed financial adviser before making any investment decisions.

 Nov 18, 2026


 Please wait processing your request...