
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
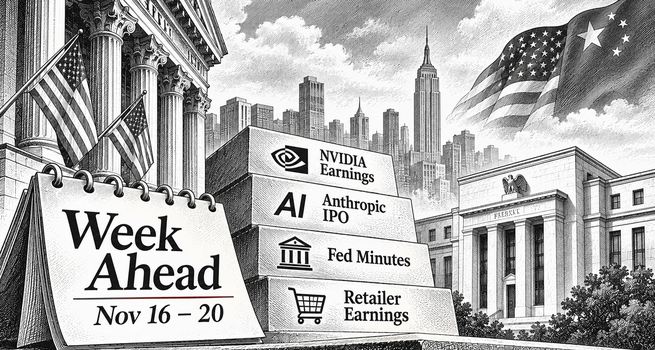
Wall Street begins a pivotal week with the AI trade on the defensive. Futures pointed lower early on Monday, led by technology shares, ahead of two events that could set the tone for the sector: Nvidia's quarterly results after the close on Tuesday, its first since Jensen Huang's resignation as chief executive last week, and Anthropic's initial public offering, which is expected to price on Wednesday evening and begin trading on Nasdaq on Thursday. Analysts expect Nvidia to report Earnings of about $2.47 a share on Revenue of roughly $109 billion, growth of about 90% on a year earlier, but investors will focus on guidance and on whether interim chief executive Colette Kress can steady a company whose Market Value has fallen from about $5.8 trillion in early October to about $3.9 trillion.
The Federal Reserve supplies the macro backdrop: minutes of the October meeting, due on Wednesday, and a long list of Fed speakers, beginning with Chair Kevin Warsh on Monday, will be parsed for clues on a December rate rise that markets now fully price after hotter-than-expected October Inflation data. Tuesday's retail sales report and results from Home Depot, Target, Lowe's, TJX and Walmart will show whether consumers are coping with higher borrowing costs and fuel prices. The war in the Middle East, and a meeting between President Donald Trump and China's Xi Jinping at the APEC summit in Shenzhen, remain the backdrop variables most capable of shifting sentiment.
Major Ex-Dividend Dates This Week
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Monday, Nov 16 |
United Parcel Service |
$1.64 |
5.84% |
|
|
Monday, Nov 16 |
Hershey |
$1.45 |
3.33% |
|
|
Tuesday, Nov 17 |
Phillips 66 |
$1.33 |
2.01% |
|
|
Tuesday, Nov 17 |
Bunge |
$0.72 |
2.83% |
|
|
Wednesday, Nov 18 |
Chevron |
$1.78 |
3.24% |
|
|
Wednesday, Nov 18 |
Consolidated Edison |
$0.89 |
2.93% |
|
|
Wednesday, Nov 18 |
Archer-Daniels-Midland |
$0.52 |
2.85% |
|
|
Thursday, Nov 19 |
Microsoft |
$0.98 |
0.75% |
|
|
Thursday, Nov 19 |
Applied Materials |
$0.53 |
0.57% |
|
|
Friday, Nov 20 |
Amgen |
$2.52 |
2.16% |
|
|
Friday, Nov 20 |
Cummins |
$2.20 |
1.95% |
|
|
Friday, Nov 20 |
RTX |
$0.73 |
1.47% |
Monday, November 16
Earnings
Tyson Foods (NYSE:TSN) reports before the open, with analysts expecting earnings of $1.21 a share on revenue of $14.73 billion. Aramark (NYSE:ARMK) has already reported: earnings of $0.71 a share fell short of the $0.76 forecast, while revenue of $5.29 billion edged past estimates.
Economic Data
The Empire State Manufacturing Survey for November, prior at 25.6 and forecast at 16.7, lands at 8:30 am ET. A reading in line with forecasts would mark a sharp cooling from October's strength, though it would still point to expansion in New York-area factory activity.
Federal Reserve
Fed Chair Kevin Warsh speaks in San Francisco at 12:00 pm ET, and Cleveland Fed President Beth Hammack is also scheduled to speak. Markets will listen for any sign that the Fed intends to deliver the December rise that is now fully priced, or whether the size of the move, where a half-point increase is priced at roughly 8%, is still open to debate.
Tuesday, November 17
Earnings
Home Depot (NYSE:HD), expected to earn $3.83 a share on revenue of $42.77 billion, and Walt Disney (NYSE:DIS), expected to earn $1.78 on revenue of $25.30 billion, report before the open. Home Depot offers the first of the week's consumer reads, with housing turnover constrained by elevated Mortgage rates and big-ticket spending under pressure.
Nvidia (NASDAQ:NVDA) reports after the close and is the week's defining corporate event. Consensus calls for earnings of $2.47 a share, against $1.30 a year earlier, on revenue of about $108.8 billion, against $57 billion, but the numbers matter less than the commentary. Shares fell about 13% last week, their steepest weekly decline since April 2025, after Huang stepped down amid revelations about extramarital relationships, including one with a woman U.S. officials suspect of spying for China. Treasury Secretary Scott Bessent has urged the board to look outside the company for its next chief executive, and the Financial Times reported on Monday that Huang is considering a return. Investors will look for guidance, evidence that Demand has kept accelerating, and any clarity on succession.
Economic Data
Retail sales for October, prior at 0.8% and forecast at 0.2%, lead the morning at 8:30 am ET, alongside Import prices, prior at 1.1% and forecast at 0.7%. The retail sales figure is the week's most important consumer read, because it will show how households are responding to higher gasoline prices and borrowing costs and whether inflation is still building. Industrial production for October, prior at 0.7% and forecast at 0.1%, follows at 9:15 am ET, with capacity utilisation, prior at 76.9%, forecast at 76.9%. Business inventories for September, prior at 0.4% and forecast at 0.5%, and the NAHB Housing Market Index for November, prior at 29 and forecast at 29, arrive at 10:00 am ET.
Federal Reserve
Fed Governor Christopher Waller speaks at 9:10 am ET, followed by Cleveland Fed President Beth Hammack at the Brookings Institution at 9:30 am ET. New York Fed President John Williams, a permanent voter on the rate-setting committee, speaks at 2:25 pm ET, and the Cleveland Fed also holds a conversation on central banking, with timing to be announced.
Wednesday, November 18
Earnings
The retail season hits full stride before the open, with TJX Companies (NYSE:TJX), expected to earn $1.34 a share on revenue of $15.86 billion, Lowe's (NYSE:LOW), at $2.87 on $22.38 billion, and Target (NYSE:TGT), at $2.05 on $26.39 billion, all reporting. Target and Lowe's will be read for the health of discretionary and home-improvement spending, while TJX tests whether trade-down demand is lifting off-price retailers. Palo Alto Networks (NASDAQ:PANW), Copart (NASDAQ:CPRT) and Woodward (NASDAQ:WWD) report after the close. Palo Alto, expected to earn $0.97 a share on revenue of $3.31 billion, will give a read on enterprise software and cyber-security demand.
Economic Data
Housing starts for October, forecast at an annualised 1.23 million after September's four-month low of 1.22 million, are released at 8:30 am ET, with building permits due alongside. Pending home sales for October, prior at -7.3% and forecast at -1.4%, follow at 10:00 am ET, a reading that will show whether contract signings are stabilising after a steep fall.
Federal Reserve
The Federal Open Market Committee publishes minutes of its October meeting at 2:00 pm ET. The Fed held rates at that meeting, a month after raising them for the first time in three years, with two officials dissenting in favour of a hike. Economists at Bank of America expect the minutes to reveal a deeper divide over the hold than the 10-2 vote suggested, which would add weight to hawkish expectations for December. Fed Governor Michael Barr speaks at 1:35 pm ET, Williams again at 2:30 pm ET, and Minneapolis Fed President Neel Kashkari at 4:15 pm ET.
Market
Anthropic is expected to price its initial public offering after the close. The company and some of its investors are offering 825 million shares at a range of $70 to $78, which would raise up to about $64.4 billion and value the maker of the Claude chatbot at up to about $1.4 trillion, with trading due to begin on Nasdaq under the ticker ANT. Reports have pointed to heavy oversubscription, so where the offering prices relative to the range will be read as an early verdict on investor appetite for AI.
Thursday, November 19
Earnings
Walmart (NASDAQ:WMT) reports before the open, expected to earn $0.64 a share on revenue of $187.3 billion, and is the week's most important consumer read, given its reach across income groups. PDD Holdings (NASDAQ:PDD) reports alongside it. After the close, Intuit (NASDAQ:INTU), expected to earn $2.46 a share on revenue of $4.31 billion, Ross Stores (NASDAQ:ROST), at $1.84 on $6.21 billion, and Keysight Technologies (NYSE:KEYS), at $3.37 on $1.95 billion, round out the day. Investors are particularly eager for clues on whether consumer spending is holding up as households face higher gasoline prices and borrowing costs than earlier in the year.
Market
Anthropic shares are expected to begin trading on Nasdaq under the ticker ANT. The debut will serve as a real-time barometer of sentiment on the AI trade, coming days after Nvidia's turmoil and several weeks of heavy selling in AI-linked shares. Some strategists caution that a strong first day would not necessarily lift the rest of the sector, since investors buying the new shares may sell other technology holdings to make room.
Economic Data
The Philadelphia Fed Business Outlook Survey for November, prior at 20.9 and forecast at 18, and weekly jobless claims for the week ending November 14, prior at 200,000 and forecast at 200,000, land at 8:30 am ET. The Conference Board's Leading Economic Index, prior at 0.0% and forecast at 0.1%, follows at 10:00 am ET, and the Kansas City Fed Survey for November, prior at 16, at 11:00 am ET.
Federal Reserve
Chicago Fed President Austan Goolsbee takes part in a moderated discussion at the Economic Club of Indiana at 12:30 pm ET. Fed Governor Michael Barr speaks again at 2:15 pm ET, and Philadelphia Fed President Anna Paulson speaks at a Money Marketeers dinner at 5:30 pm ET.
Friday, November 20
Earnings
BJ's Wholesale Club (NYSE:BJ), expected to earn $1.24 a share on revenue of $5.93 billion, reports before the open, offering a warehouse-club read on household spending a day after Walmart. The rest of the corporate calendar is thin.
Economic Data
The University of Michigan's final consumer sentiment index for November is released at 10:00 am ET. The preliminary reading rose to 51.0 from 48.0 in October, its highest since August, so the final figure will show whether the early-month improvement held as inflation pressures built.
Federal Reserve
Fed Governor Christopher Waller speaks at 8:25 am ET, Fed Governor Lisa Cook at 12:16 pm ET, and Waller again at the National College Fed Challenge finals, with timing to be announced.
Geopolitical Backdrop
The war in the Middle East continues to shape energy prices and, through them, global borrowing costs, as signs of rising Supply from the region compete with the lingering risk of escalation. Elevated fuel prices are weighing on household budgets, and rate-sensitive two-year Treasury yields recorded their largest weekly increase in more than two years last week before easing on Monday. On the diplomatic front, Trump and Xi are due to meet at the APEC summit in Shenzhen on November 18 and 19, though observers expect few concrete deliverables at that meeting, with larger agreements more likely to wait for the G20 summit in December. Analysts say the Nvidia controversy, which involves an alleged Chinese intelligence link, could cast a shadow over the talks.
Asia traded weakly on Monday after Japan's economy unexpectedly stalled in the third quarter, with GDP flat on the quarter against forecasts of 0.1% growth and exports falling for the first time in a year. Japan's Nikkei 225 fell 2.4%, South Korea's Kospi dropped 3.6%, and mainland China's CSI 300 slid 0.9% after downbeat economic data, while European markets were broadly steady. The UK publishes labour-market data on Tuesday, October inflation on Wednesday and retail sales on Friday, all at 7:00 am London time. Canada releases inflation, retail sales and housing data, Mexico reports retail trade, and Argentina publishes its trade balance.
The Week in Context
Two threads will determine how the week is ultimately read. First, whether Nvidia's results and Anthropic's debut steady an AI trade that has been shaken by higher borrowing costs, fears of tougher regulation of data centers after the midterm elections, and now turmoil at the top of its most important company. Nvidia's slide last week dragged down other chipmakers, neocloud providers such as CoreWeave and Nebius, and server makers, and strategists warn that a disappointing report from a company already under a cloud would be punished heavily. Strong guidance and a credible plan for Leadership would help, while pricing for Anthropic at or above the top of its range would signal that appetite for AI remains intact. Wells Fargo's analyst argues that investors have been looking at risks, including inflation and the war in the Middle East, through rose-coloured glasses, and that a disappointment this week could change that.
Second, whether the Fed's messaging and the consumer data push the December rate rise from expectation to certainty. Hotter-than-expected October inflation has left a quarter-point increase fully priced for the December 8 to 9 meeting, so the minutes, Warsh's remarks and Tuesday's retail sales will be judged on whether they point to a larger move or more tightening to come. A resilient consumer in Walmart's and Target's numbers would reinforce that case, while signs of strain would revive worries about growth. With the S&P 500 still up about 10.5% for 2026 after a weekly gain that snapped four straight declines, this week's mix of earnings, a landmark listing and central-bank signals will go a long way toward deciding whether the recent wobble proves a pause or the start of something deeper.

 Nov 20, 2026


 Please wait processing your request...