
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
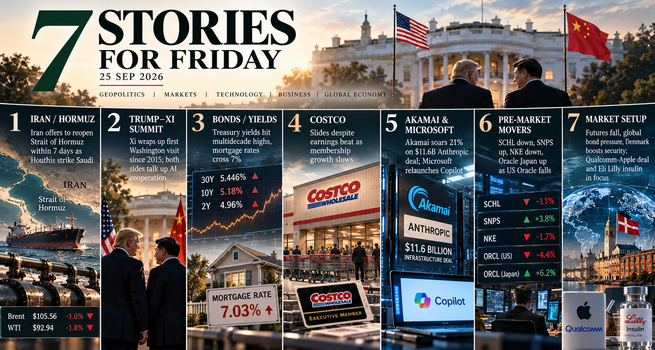
Iran offered to reopen the Strait of Hormuz within 7 days as Xi Jinping wrapped up his Washington visit with tea at the White House, while Treasury yields hit their highest levels since 2004 and 2007. Costco slid despite topping Earnings estimates, Akamai jumped more than 21% on an $11.6 billion Anthropic deal, and Microsoft relaunched Copilot to compete with Anthropic's Claude.
1. IRAN/HORMUZ: Iran Offers to Reopen the Strait of Hormuz Within 7 Days as Houthis Fire on Saudi Arabia and Oil Slides
Iran's Foreign Minister Abbas Araghchi proposed reopening the Strait of Hormuz and resuming nuclear talks with the US within 7 days if Washington accepts conditions he said mirror the June ceasefire memorandum, a deal the administration has said it will not revert to. The offer follows President Masoud Pezeshkian's defiant UN response to Trump's earlier "annihilation" threat and comes nearly 7 months into the US-Israel war against Iran. It landed hours after Houthi rebels in Yemen fired dozens of missiles and drones at Saudi targets, prompting emergency alerts in Mecca, Jeddah and Yanbu; Saudi Arabia said it intercepted 6 ballistic missiles and, with Turkey and Pakistan, planned an urgent chiefs-of-staff meeting under their mutual-defense pact. Pezeshkian distanced Tehran from the strikes, saying "the Houthis are responsible for their own actions," while Saudi Arabia's Grand Mufti told troops to be ready "to lay down their lives" against the group. Brent Crude fell about 1% to $105.56 a barrel and WTI dropped 1.8% to $92.94, as vessel transits through Hormuz, normally the route for about a fifth of global oil supply, fell to just 9; China's special envoy for the Middle East called the war "a big issue" in this week's Trump-Xi talks.
- A 7-day reopening offer landing the same morning Saudi Arabia is fending off Houthi missiles shows Iran pursuing diplomacy and its regional allies escalating simultaneously, leaving Washington to weigh a good-faith gesture against fresh instability on its doorstep.
- Risk note: with the offer's conditions echoing a June memorandum the US has already rejected once and Hormuz transits still near historic lows, a second US refusal could harden Tehran's position just as China is pressing both sides toward a resolution.
2. TRUMP-XI SUMMIT: Xi Wraps Up First Washington Visit Since 2015 With Tea at the White House as Both Sides Talk Up AI Cooperation
Xi Jinping's first state visit to Washington since 2015 concluded Friday with tea at the White House, a day after Trump called their talks "great" even as the formal agenda proved lighter than the ceremonial banquet suggested. Xi told Trump the countries "stand to gain from co-operation and will both lose in confrontation," and a Chinese state media readout said he added the 2 sides "can continue their dialogue on AI" and "jointly prevent the misuse and abuse of AI"; the US had not issued its own readout. The overture follows Bessent's discussion of a "US-China AI dialogue" with counterpart He Lifeng, including a national-security-incident channel compared to the Cold War-era "red phone," and China's Commerce Ministry confirmed Thursday its negotiators held their first-ever AI talks with the US. Both governments had already rejected calls from OpenAI's Sam Altman and Anthropic's Dario Amodei for guardrails on AI development.
- Both leaders using cooperative language on AI while their governments have already dismissed calls for guardrails shows the rhetoric outrunning any substantive commitment, consistent with Trump's own framing of the summit as heavier on pomp than agenda.
- Risk note: with no joint US readout and the AI dialogue still limited to incident notification rather than binding rules, the Goodwill from Xi's visit could prove as thin as the "red phone" comparison suggests once negotiators return to competing chip and export-control fights.
3. BONDS/YIELDS: 10-Year Treasury Yield Hits Its Highest Since 2007 as 30-Year Mortgage Rates Cross 7% for the First Time in 2 Years
The 10-year Treasury yield rose to 5.183%, its highest since June 2007, while the 30-year climbed to 5.476%, a level last seen in 2004, extending a Global Bond selloff that pushed Japanese, UK and German yields to fresh highs. The move has been driven by hawkish comments from Fed Governor Michael Barr, who said Wednesday "further policy adjustments" can be expected to bring Inflation to target, alongside persistently high oil prices tied to the Iran war and a purchasing managers' index reading at its highest in more than 4 years; traders now price a 66% chance of an October rate hike, per the CME FedWatch tool. The 10-year saw its fastest one-day increase since April 2025 on Wednesday, a level that stood below 4.8% just 2 weeks ago. The rise pushed the 30-year fixed mortgage rate to 7.45%, its highest since 2024, exceeding 7% for the first time in almost 2 years per Freddie Mac, a shift likely to weigh on the stagnant housing market and on Republicans ahead of November's midterms. Separately, durable goods orders were flat in August, better than the 0.3% decline economists expected, with orders up 7.7% year-over-year.
- Yields climbing on genuine economic strength and hawkish Fed commentary, rather than Deficit concerns alone, suggests less room for a dovish surprise than markets had priced 2 weeks ago, when the 10-year sat nearly 40 basis points lower.
- Risk note: with mortgage rates now above 7% heading into the midterms, a further hawkish surprise from October's Fed decision could accelerate the housing-market and consumption slowdown already showing up in the data.
4. COSTCO: Shares Slide Despite a Fiscal Fourth-Quarter Beat as Membership Growth Slows for an 8th Straight Quarter
Costco Wholesale (NASDAQ:COST) shares fell about 0.9% to $896.48 at Thursday's close and were down a further 0.8% pre-market Friday, even after fiscal fourth-quarter results topped estimates on both lines: Diluted Earnings per Share of $6.75 beat the roughly $6.53 consensus, aided by a $0.15-per-share benefit from IEEPA Tariff refunds, while Revenue rose 11.2% year-over-year to $95.72 billion against expectations near $94.9 billion. Adjusted comparable sales growth of 9.4% came in just under the roughly 9% analysts modeled, and digitally-enabled sales jumped 19.5%, but investors focused on membership growth decelerating for an 8th consecutive quarter even as renewal rates hit a record. At least 8 brokerages trimmed price targets while largely maintaining ratings, reflecting concern that membership growth needs to reaccelerate to justify a valuation near 45 times trailing earnings. Shares remain roughly 18% below their May highs even as management outlined plans to open 33 new warehouses in fiscal 2027.
- A double beat followed by trimmed price targets from 8 or more brokerages shows analysts treating Costco's premium valuation, not the quarter itself, as the constraint, with membership growth rather than sales or earnings now the metric the market is trading on.
- Risk note: with the stock already down about 18% from its May highs and priced near 45 times trailing earnings, an 8th straight quarter of decelerating membership growth leaves little room for a 9th before the valuation debate outweighs the retailer's otherwise resilient comparable-sales performance.
5. AI/BIG TECH: Akamai Jumps 21% on an $11.6 Billion Anthropic Deal as Microsoft Relaunches Copilot to Compete With Claude
Akamai Technologies (NASDAQ:AKAM) shares jumped more than 21% after the cloud-computing company announced a 7-year, $11.6 billion power and infrastructure deal with Anthropic on Thursday, alongside a Warrant giving Anthropic the right to buy up to roughly 5% of Akamai's shares at $111.33 each. Separately, Microsoft (NASDAQ:MSFT) introduced an updated Copilot app Friday combining coding capabilities with a tool for building autonomous agents, a bid to challenge Anthropic's traction in enterprise AI after fewer than 7% of Microsoft's more than 450 million commercial Office 365 seats have upgraded to its existing AI add-on. Rather than flat subscription fees, Microsoft will charge usage-based pricing for the new app's Cowork, Code and Autopilot components. Microsoft shares are up just 3% this year through Thursday's close, underperforming the Nasdaq and most megacap peers, as the company faces a crowded agent market that includes Meta's newly launched Muse app, which has risen to the top of Apple's App Store.
- Akamai's 21% jump on a named $11.6 billion contract, against Microsoft's more incremental product repackaging, shows the market rewarding concrete Anthropic-linked infrastructure spending far more than an enterprise-software rebundling aimed at competing with the same company.
- Risk note: with fewer than 7% of Office 365 seats currently paying for AI tools and Meta's Muse already leading app-store rankings, Microsoft's usage-based pricing shift will need to succeed where 3 years of subscription pricing has not.
6. PRE-MARKET MOVERS: Scholastic Slides 10% on a Loss as Synopsys Rises on an Upgrade and Oracle Japan Surges Opposite Its US Parent
Scholastic (NASDAQ:SCHL) shares slid more than 10% after the children's-book publisher posted a fiscal first-quarter adjusted loss of $3.63 per share, wider than the $2.52 per share loss a year earlier, on revenue of $216.8 million, down 4% year-over-year. Synopsys (NASDAQ:SNPS) gained more than 3% after HSBC upgraded the software company to buy from hold, calling its new Business model a "high-growth AI beneficiary." Nike (NYSE:NKE) fell nearly 2% after Bank of America downgraded the athletic-apparel maker to underperform, citing expected sales declines through fiscal 2027. Oracle Corp Japan shares surged more than 7% to a record fiscal first-quarter performance, with sales up 13% year-over-year to 74.86 billion yen and cloud revenue up 31.7%, a rally in sharp contrast to the more than 3% overnight drop in US-listed Oracle (NYSE:ORCL) shares tied to its New Mexico Data Center Force Majeure notice.
- Oracle's Japanese arm posting record results the same day its US parent extends a force majeure-driven selloff shows the AI infrastructure buildout's execution risk concentrated in specific US projects rather than in the company's global cloud business broadly.
- Risk note: Scholastic's widening loss and Nike's guidance-driven downgrade both point to consumer-facing weakness building beneath a market otherwise focused on AI infrastructure and rate-driven names, a divergence that could broaden if yields keep climbing.
7. MARKET SETUP: Futures Rise as Yields Steady, Denmark Warns Russia Could Strike a NATO Country and Asia Trades Mixed
US Equity futures rose Friday as Wall Street set to close out a volatile week, with S&P 500 futures up 0.4%, Nasdaq-100 futures up 0.7% and Dow futures up 199 points; the Dow was on track for a 4th consecutive losing week, down 0.6% through Thursday, while the S&P 500 was set for a 0.7% weekly advance and the Nasdaq for a 1.6% gain. Danish intelligence warned of a "low but growing risk" that Russia could launch limited strikes or deploy troops into a NATO country in the coming months, saying Moscow is expected to intensify hybrid attacks, including cyberattacks and sabotage with a "high risk of casualties"; the warning followed a fire at a Starlink ground station in Poland that officials called sabotage aligned with "Russia's new doctrine of attack." Finland and Sweden scrambled fighter jets Thursday to intercept Russian military aircraft over the Gulf of Finland, the first such interception since the 2 countries agreed last month to coordinate more closely on regional defense. Separately, Qualcomm (NASDAQ:QCOM) said Apple (NASDAQ:AAPL) has extended its patent-licensing agreement through March 2027 even as Apple works to reduce reliance on Qualcomm's modem chips, with licensing revenue making up about 15% of Qualcomm's total revenue in the June quarter.
- Denmark's warning landing alongside confirmed Russian air incursions over Finland and Sweden and a Poland sabotage incident shows European security officials treating hybrid escalation as an active pattern rather than a hypothetical risk.
- Risk note: with futures rising on hopes the week's yield surge is stabilizing, any escalation matching Denmark's warning could unsettle European markets already absorbing record bond yields across Japan, the UK and Germany.

 Oct 30, 2026





 Please wait processing your request...