
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
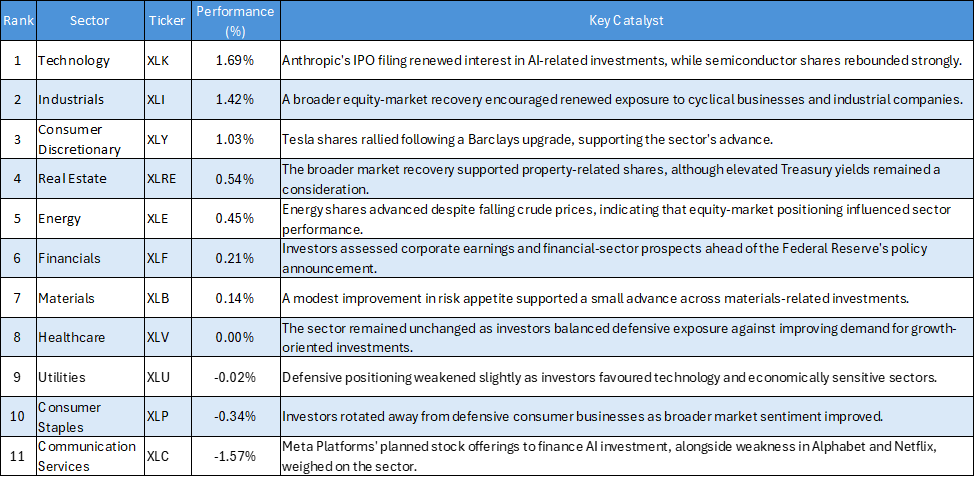
- Technology (XLK) led all eleven sectors, gaining 1.69%, as semiconductor shares rebounded and Anthropic's initial public offering filing renewed investor interest in artificial intelligence.
- Industrials (XLI) advanced 1.42%, while Consumer Discretionary (XLY) rose 1.03%, indicating renewed Demand for economically sensitive and growth-oriented investments.
- Real Estate (XLRE) gained 0.54%, while Energy (XLE) increased 0.45%, extending the advance beyond the strongest-performing growth sectors.
- Financials (XLF) and Materials (XLB) recorded smaller gains of 0.21% and 0.14%, respectively, while Healthcare (XLV) finished unchanged.
- Utilities (XLU) slipped 0.02%, Consumer Staples (XLP) declined 0.34%, and Communication Services (XLC) was the weakest sector, falling 1.57%.
- The 3.26-percentage-point gap between Technology and Communication Services highlighted a significant divergence between sectors with different exposure to artificial intelligence Investment and corporate spending expectations.
US sector performance on 26 October 2026 reflected a recovery in growth-oriented investments, led by Technology, Industrials and Consumer Discretionary. The S&P 500 advanced 0.70%, while the Nasdaq Composite gained 0.82%, as investors responded to developments in the artificial intelligence industry and anticipated earnings announcements from major technology companies. Anthropic's filing for an initial public offering supported renewed interest in AI-related investments, while semiconductor shares rebounded following recent weakness. However, Communication Services declined sharply as concerns about the financing requirements of artificial intelligence infrastructure weighed on major companies. The session demonstrated improving risk appetite, although sector performance remained uneven.
Performance Breakdown by Sector
Technology Leads as Artificial Intelligence Optimism Returns
Technology gained 1.69%, making it the strongest-performing sector on 26 October. The advance followed renewed interest in artificial intelligence after Anthropic filed for an initial public offering, strengthening attention on the commercial opportunities associated with AI development. Semiconductor shares also rebounded, with Nvidia, Broadcom, Micron Technology and AMD among the notable beneficiaries of improving sentiment.
The recovery was significant because investors had recently questioned whether substantial AI infrastructure spending could generate sufficient financial returns. Anthropic's filing provided a fresh development for investors assessing the commercial potential of the industry, although it did not eliminate concerns about valuations and Capital requirements.
Microsoft also advanced, while Apple declined, illustrating that the technology recovery was not uniform. Investors will need to assess upcoming earnings announcements, Capital Expenditure plans and evidence of AI-related Revenue growth to determine whether the rebound can develop into sustained sector leadership.
Industrials and Consumer Discretionary Strengthen
Industrials advanced 1.42%, ranking second among the eleven sectors. The gain reflected improving market sentiment and renewed interest in economically sensitive businesses. However, a single session of positive performance does not establish that industrial activity or corporate earnings expectations have strengthened across the sector.
Consumer Discretionary rose 1.03%, supported by a substantial advance in Tesla shares following a Barclays upgrade. The sector's performance suggested that investors were willing to increase exposure to companies associated with economic growth and consumer demand.
Nevertheless, the outlook remains sensitive to household purchasing power, borrowing costs and employment conditions. Sustained gains will depend on whether corporate earnings support current valuations and whether consumer demand remains resilient.
Mixed Performance Across Financials, Materials and Energy
Real Estate gained 0.54%, while Energy increased 0.45%. Financials and Materials also advanced, although their gains were more modest at 0.21% and 0.14%, respectively. These results indicated that the recovery extended beyond technology, but participation varied considerably across the market.
Financial stocks remained in focus ahead of the Federal Reserve's policy announcement and major corporate earnings releases. Interest rates and Credit conditions will remain important influences on bank profitability, lending activity and financial-market valuations.
Energy shares advanced despite a decline in Crude Oil prices. This divergence highlights how equity-market positioning and company-specific expectations can influence sector returns independently of commodity-price movements. Investors should continue monitoring oil prices, Inflation expectations and global economic conditions when assessing the sector's prospects.
Communication Services Weakens as AI Financing Concerns Persist
Communication Services declined 1.57%, making it the weakest sector. Meta Platforms fell after announcing plans for substantial stock offerings to support artificial intelligence investments and other corporate purposes. The financing plan included an initial offering of approximately $35 billion and a separate programme that could raise another $60 billion through at-the-market share sales in 2027.
The announcement intensified scrutiny of the relationship between AI infrastructure expenditure, financing requirements and future returns. Alphabet and Netflix also declined, contributing to weakness across the sector.
The divergence between Technology's 1.69% gain and Communication Services' 1.57% decline demonstrates that exposure to artificial intelligence does not automatically translate into uniform share-price performance. Investors are increasingly distinguishing between companies expected to benefit from AI investment and businesses whose spending commitments may place pressure on Cash Flow or Shareholder returns.
Consumer Staples declined 0.34%, while Utilities slipped 0.02%. Healthcare finished unchanged. These relatively weak performances suggested that investors favoured growth-oriented investments over traditionally defensive sectors during the session.
Strategic Summary
The 26 October session demonstrated a recovery in growth-oriented market leadership, with Technology, Industrials and Consumer Discretionary recording the strongest gains. Anthropic's IPO filing and a rebound in semiconductor shares supported Technology, while improving risk appetite benefited industrial and consumer-related investments. Conversely, Communication Services suffered the largest decline as investors assessed the financial implications of substantial AI infrastructure spending.
Investors should monitor upcoming technology earnings, semiconductor performance, AI capital expenditure plans, Treasury yields and the Federal Reserve's policy announcement. The session provides evidence of improving risk appetite, but one day's performance cannot confirm a durable sector rotation. Sustained Leadership will depend on whether earnings growth justifies valuations and whether companies can demonstrate that their investments are generating adequate financial returns.


 Oct 26, 2026
 Please wait processing your request...