
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
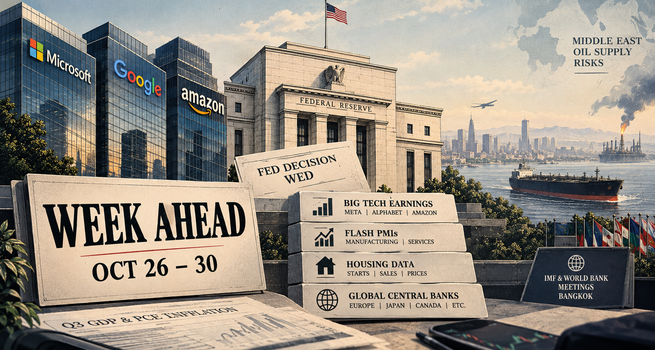
The busiest week of third-quarter Earnings season arrives with roughly a third of S&P 500 companies reporting, led by hyperscalers Alphabet and Microsoft on Wednesday and Amazon on Thursday, alongside Visa, Coca-Cola, Boeing, Eli Lilly, Mastercard, Caterpillar, Intel, ExxonMobil and Chevron. The week's defining moment comes on Wednesday afternoon, when the Federal Reserve announces its policy decision hours before Alphabet and Microsoft report, with markets assigning only a single-digit probability to a rate rise this month but around 80% odds of one in December, a path that Fed Chair Kevin Warsh's press conference could either confirm or complicate.
Thursday then brings the advance estimate of third-quarter GDP, forecast to accelerate to an annualised 3.2% from 2.2%, together with September PCE inflation, where the headline measure is expected to rise 0.5% month-on-month, its largest increase since March, lifting the annual rate to 3.7% from 3.4%, and the core measure 0.3%; Friday's Employment Cost Index, forecast to ease to 0.8% from 0.9%, then offers a final read on wage pressure. Central banks in Europe, Japan, Canada, New Zealand, Thailand and Chile also set policy, adding a global dimension to a week already crowded with domestic catalysts. Developments in the Middle East, where disruption to oil Supply continues to drive energy costs higher, remain the backdrop variable most capable of moving Inflation expectations, while the US midterm elections on November 3 loom just beyond the week's horizon.
Major Ex-Dividend Dates This Week
|
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Monday, Oct 26 |
Caterpillar |
$1.63 |
0.93% |
|
|
Monday, Oct 26 |
Paychex |
$1.19 |
4.01% |
|
|
Tuesday, Oct 27 |
Alcoa |
$0.10 |
1.03% |
|
|
Tuesday, Oct 27 |
GE Vernova |
$0.50 |
0.24% |
|
|
Tuesday, Oct 27 |
Thor Industries |
$0.54 |
3.05% |
|
|
Wednesday, Oct 28 |
Clorox |
$1.25 |
5.64% |
|
|
Wednesday, Oct 28 |
Fastenal |
$0.26 |
1.97% |
|
|
Wednesday, Oct 28 |
Commercial Metals |
$0.20 |
1.25% |
|
|
Thursday, Oct 29 |
Carrier Global |
$0.24 |
1.70% |
|
|
Friday, Oct 30 |
AES Corporation |
$0.18 |
4.70% |
|
|
Friday, Oct 30 |
Alliant Energy |
$0.54 |
3.04% |
|
|
Friday, Oct 30 |
Agree Realty |
$0.27 |
4.85% |
Monday, October 26
Earnings
Verizon Communications (NYSE:VZ) opens the week before the bell. After the close, Cadence Design Systems (NASDAQ:CDNS), Amkor Technology (NASDAQ:AMKR) and Rambus (NASDAQ:RMBS) offer an early semiconductor read ahead of the hyperscalers, while Welltower (NYSE:WELL), Nucor (NYSE:NUE), Public Storage (NYSE:PSA), The Hartford (NYSE:HIG), Cincinnati Financial (NASDAQ:CINF) and Principal Financial Group (NASDAQ:PFG) span healthcare real estate, steel and insurance. Investors will look to the chip designers and packagers for signs of whether last week's disappointment from Lam Research reflected company-specific issues or a broader cooling in AI-related demand.
Economic Data
No major U.S. economic releases are scheduled. The Treasury's sale of $69 billion in two-year notes at 1:00 pm ET will instead test Demand for short-dated Debt two days before a Fed decision, with yields already elevated.
Tuesday, October 27
Earnings
A broad slate of consumer, industrial and materials names reports before the open: Coca-Cola (NYSE:KO), Boeing (NYSE:BA), United Parcel Service (NYSE:UPS), S&P Global (NYSE:SPGI), Corning (NYSE:GLW), HCA Healthcare (NYSE:HCA), Freeport-McMoRan (NYSE:FCX), American Tower (NYSE:AMT), Johnson Controls (NYSE:JCI) and Sherwin-Williams (NYSE:SHW). Boeing will be read for production and delivery progress, UPS for parcel volumes as a proxy for goods demand, and Coca-Cola for how far pricing power still holds up against squeezed household budgets. Visa (NYSE:V), Seagate Technology (NASDAQ:STX), Waste Management (NYSE:WM) and Robinhood Markets (NASDAQ:HOOD) follow after the close, with Visa's payment volumes offering a timely read on consumer spending and Seagate's results a gauge of AI-driven data storage demand.
Economic Data
Durable goods orders for September, prior at 0.0% and forecast to rebound 1.2%, land at 8:30 am ET, offering a read on Business Investment at a time when AI-related spending is propping up Capital Goods demand. The S&P Cotality Case-Shiller Home Price index for August, prior at 0.0%, follows at 9:00 am ET. New home sales for September, prior at 684,000 and forecast at 666,000, and the Conference Board's Consumer Confidence Index for October, prior at 81.9 and forecast at 81.2, are both released at 10:00 am ET, a pairing that will show how elevated Mortgage rates and energy costs are weighing on households.
Federal Reserve
The Federal Open Market Committee begins its two-day policy meeting.
Wednesday, October 28
Earnings
The AI infrastructure trade takes centre stage before the open, with GE Vernova (NYSE:GEV), Amphenol (NYSE:APH) and Vertiv (NYSE:VRT) reporting alongside Automatic Data Processing (NASDAQ:ADP) and Phillips 66 (NYSE:PSX). The heavyweights arrive after the close: Alphabet (NASDAQ:GOOGL) and Microsoft (NASDAQ:MSFT), each valued at roughly $3.9 trillion, report together with KLA (NASDAQ:KLAC), ServiceNow (NYSE:NOW), T-Mobile US (NASDAQ:TMUS), Fortinet (NASDAQ:FTNT), Equinix (NASDAQ:EQIX) and O'Reilly Automotive (NASDAQ:ORLY). Capital spending guidance, and evidence that the outlays are generating returns, will matter more than the headline numbers, particularly after Meta's results failed to reassure investors last week.
Economic Data
The advance U.S. trade balance in goods for September, prior at -$132.6 billion, is released at 8:30 am ET alongside wholesale inventories, prior at 0.7%, and retail inventories, prior at 0.3%. All three feed directly into Thursday's GDP estimate.
Federal Reserve
The Federal Open Market Committee announces its decision at 2:00 pm ET, with the federal funds target range currently at 3.75% to 4.00%, followed by Fed Chair Kevin Warsh's press conference. Having raised rates in September for the first time since 2023, the Fed is widely expected to hold this month, in part because investors doubt it would tighten a week before the midterm elections. Markets will parse Warsh's remarks for any signal on December, where futures are pricing a hike with roughly 80% probability. The Bank of Canada announces its own decision earlier in the day at 9:45 am ET, amid concerns over inflation.
Thursday, October 29
Earnings
Thursday is the week's heaviest day for market-moving earnings. Eli Lilly (NYSE:LLY), valued at about $1.2 trillion, reports before the open alongside Mastercard (NYSE:MA), Merck (NYSE:MRK), Caterpillar (NYSE:CAT), Linde (NASDAQ:LIN), Bristol-Myers Squibb (NYSE:BMY), Altria (NYSE:MO), Trane Technologies (NYSE:TT) and Intercontinental Exchange (NYSE:ICE). Amazon (NASDAQ:AMZN) headlines the evening session, where cloud growth at AWS and the scale of its capital spending will be scrutinised, joined by Intel (NASDAQ:INTC), Sandisk (NASDAQ:SNDK), Gilead Sciences (NASDAQ:GILD), Stryker (NYSE:SYK) and Starbucks (NASDAQ:SBUX). Intel and Sandisk give two further reads on the semiconductor cycle, closing out a week in which chip demand will be tested from several angles.
Economic Data
Thursday morning is the week's data peak, with every major release landing at 8:30 am ET. The advance estimate of third-quarter GDP, prior at 2.2%, is forecast to accelerate to an annualised 3.2%, supported by AI-related investment and resilient consumer spending. September personal income, prior at 0.2%, is forecast to rise 0.3%, while consumer spending, prior at 0.9%, is forecast to slow to 0.6%. The PCE price index is forecast at 0.5% month-on-month, up from 0.3%, and 3.7% year-on-year, up from 3.4%. Core PCE, the Fed's preferred gauge, is forecast at 0.3% month-on-month, up from 0.2%, and 3.1% year-on-year, up from 3.0%. Because the data arrive the morning after the Fed's decision, a hotter-than-expected core reading would quickly reinforce December hike bets rather than shape this week's outcome. Weekly jobless claims for the week ending October 24, prior at 194,000 and forecast at 200,000, round out the morning.
Friday, October 30
Earnings
Energy and healthcare dominate the final session, with ExxonMobil (NYSE:XOM) and Chevron (NYSE:CVX) reporting before the open alongside AbbVie (NYSE:ABBV), General Dynamics (NYSE:GD), Regeneron Pharmaceuticals (NASDAQ:REGN), Colgate-Palmolive (NYSE:CL), Dominion Energy (NYSE:D), Exelon (NASDAQ:EXC), Kenvue (NYSE:KVUE), Church & Dwight (NYSE:CHD) and LyondellBasell (NYSE:LYB). The oil majors will reveal how much of the Middle East-driven rise in crude prices is flowing through to profits, and how they plan to allocate the windfall between investment and Shareholder returns.
Economic Data
The Employment Cost Index for the third quarter, prior at 0.9% and forecast to ease to 0.8%, lands at 8:30 am ET, a reading the Fed will weigh for signs that wage growth is cooling even as energy keeps headline inflation elevated. The Chicago Business Barometer for October, prior at 58.8, follows at 9:45 am ET. Overseas, the Bank of Japan's decision lands late on Thursday evening, U.S. time, and Friday brings preliminary third-quarter GDP for the Eurozone and Germany alongside Germany's flash inflation reading for October.
Geopolitical Backdrop
Investors will continue to watch the Middle East for any further disruption to oil supplies, after Houthi attacks and ongoing disruption around the Strait of Hormuz added a fresh geopolitical risk premium to energy prices. Higher energy costs have pushed headline inflation well above its core counterpart and kept the 10-year Treasury Yield hovering around 5%, leaving expensive Growth Stocks especially exposed to any shift in the rate outlook. Closer to home, the US midterm elections on November 3, with bets growing that Democrats will take control of Congress, add a political layer to an already volatile fortnight for markets.
The global policy calendar is unusually dense. The European Central Bank decides on Thursday and the Bank of Japan on Friday, while the Reserve Bank of New Zealand, the Bank of Thailand and Chile's central bank also set rates. The UK delivers its Autumn Budget on Wednesday, China's Communist Party holds its fifth plenum, Israel holds a legislative election on Tuesday and Brazil's presidential runoff, in which polls pointed to a narrowing lead for Flávio Bolsonaro over President Luiz Inácio Lula da Silva, adds to the political backdrop. Inflation readings from Tokyo, Australia and Germany, Canada's monthly GDP and Mexico's third-quarter GDP complete a week in which global growth and price data will be weighed as closely as any domestic release.
The Week in Context
Two threads will determine how the week is ultimately read. First, whether Alphabet, Microsoft and Amazon can steady an AI trade that has turned decidedly fragile: the Nasdaq Composite suffered its steepest one-day fall since June on Thursday after Meta and Lam Research disappointed, and investors have shown little patience for companies spending heavily on AI infrastructure without clear evidence of returns. With hyperscaler capital spending expected to reach around $800 billion this year, guidance on future outlays will matter as much as the quarter itself, and third-quarter S&P 500 earnings, on pace for growth of more than 32%, will need to stay strong to keep the S&P 500's roughly 12% gain for 2026 intact.
Second, whether Wednesday's Fed decision and Thursday's inflation data confirm the market's expectation of a pause now and a hike in December. A hawkish tone from Warsh followed by a hot core PCE print would harden December bets and add pressure to long-duration growth stocks, while a measured message and a softer reading would support a more patient path. With the midterms a week away and a third of the index reporting, this week carries outsized influence over whether the recent tech pullback proves a buying opportunity or the start of a deeper correction.


 Oct 27, 2026


 Please wait processing your request...