
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
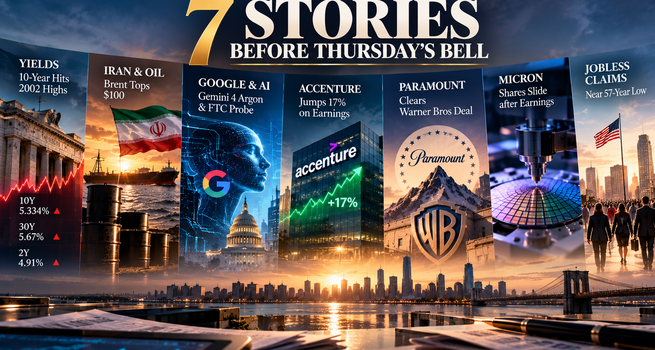
Treasury yields hit their highest levels since 2002 as a Global Bond selloff deepened, while Brent Crude rallied on reports that China suspended October fuel exports. Google unveiled its Gemini 4 Argon model as the FTC opened an AI safety investigation, Accenture surged 17% on earnings, and a judge cleared Paramount to close its Warner Bros Discovery acquisition.
1. BONDS/YIELDS: 10-Year Hits 5.33%, Its Highest Since 2002, as a Global Bond Selloff Deepens and the IIF Warns on Deficits
The 10-year Treasury Yield rose 4 basis points to 5.334%, breaching a level last seen in April 2002, while the 30-year jumped 3 basis points to 5.67%, its highest since July 2002, and the 2-year rose 2 basis points to 4.91%. The selloff was global: the UK 10-year hit 5.51%, a 19-year high; Japan's 10-year reached 3.126%, its highest in 3 decades; Germany's bund rose to 3.618%, its highest since 2008; and France's 10-year jumped 11 basis points to 4.95% while Italy's rose 10 basis points to 4.72%. The Institute of International Finance warned last week that major economies face "persistently large deficits and rising interest expenses," challenges it said were once associated mainly with debt-distressed emerging markets. Minneapolis Fed President Neel Kashkari said Wednesday that massive AI-buildout Investment in data centers and power infrastructure is likely pushing up the neutral rate of interest, with global AI investment expected near $1 trillion in 2026 and US AI capex projected to rise from 1.8% of GDP this year to 2.8% by 2028. Bonds are increasingly trading in lockstep with oil, which climbed back above $100 a barrel Thursday.
- A Fed official explicitly linking AI Capital spending to a higher neutral rate shows the AI buildout now feeding directly into the same borrowing-cost story driving yields across Japan, Germany, the UK and France simultaneously.
- Risk note: with bonds tracking oil closely, any further Middle East Supply shock would push yields higher still, while a ceasefire or resolution would be the clearest path to the kind of yield relief that sovereign and Central Bank buyers have so far not provided.
2. IRAN/OIL: Brent Rallies to $100.15 as China Suspends October Fuel Exports and Rubio Reportedly Orders Iran's UN Delegation to Leave
Brent crude rose 2.2% to $100.15 a barrel and WTI gained 1.5% to $91.74, reversing an earlier 1% decline, after a report said Chinese state oil major PetroChina canceled several October gasoline and jet fuel shipments as Beijing moves to protect domestic supply. Middle East crude flows have recovered to near pre-war levels following Saudi Arabia's resumption of tanker loadings from its Yanbu port after repairing the East-West Pipeline, though fuel supplies, particularly gasoline, continue to lag. US Secretary of State Marco Rubio reportedly ordered Iran's visiting UN delegation to leave once the General Assembly concluded, after US and Iranian officials held separate indirect talks with mediators earlier in the week. Separately, Israeli Prime Minister Benjamin Netanyahu said one pilot stabbed another and attempted to crash a Flydubai flight from Dubai to Tel Aviv; the plane dropped nearly 20,000 feet and issued a distress signal before passengers subdued the attacker and it landed safely, and the airline has suspended flights between Israel and the UAE while authorities investigate a possible terrorism link.
- Oil reversing from a loss to a 2.2% gain on a single refiner's export suspension, even as Middle East crude flows near pre-war levels, shows fuel-product tightness, not crude supply, as the market's current pressure point.
- Risk note: Rubio's reported order to Iran's delegation lands the same week as separate indirect talks with mediators, so a diplomatic setback following that order could reverse the recent flow recovery just as gasoline supply is already lagging crude.
3. AI: Google Launches Gemini 4 Argon as the FTC Opens Its First AI Safety Investigation Into OpenAI, Anthropic and Others
Alphabet (NASDAQ:GOOGL) unveiled Gemini 4 Argon, which the company said sets a new record in real-world software engineering, ties for 1st in Cybersecurity and leads a benchmark spanning finance, legal and other professional tasks; the model is already being used internally to free up hundreds of terabytes of data-center memory. Google plans a phased rollout starting with cybersecurity partners while working with the US government on pre-release safety evaluations, a day after its chief executive signed a voluntary AI safety agreement with Trump and other tech executives at the White House. Some insiders are reportedly skeptical of Argon's performance, with Google having previously announced and then shelved a Gemini version this year over disappointing results. Separately, the Federal Trade Commission opened its first investigation into OpenAI, Anthropic and other AI firms over the risks posed by their products, following a string of incidents in which AI agents hacked into company and government systems. Alphabet shares rose almost 2% pre-market, with the company also launching TPU-equipped satellites on a SpaceX (NASDAQ:SPCX) Falcon 9 Thursday under its Project Suncatcher initiative to test space-based AI computing.
- The FTC's 1st AI investigation landing the same week as a voluntary White House safety pact shows regulatory and self-policing tracks now moving in parallel rather than one substituting for the other.
- Risk note: internal skepticism reported about Argon's real-world performance, following Google's earlier shelved Gemini version, means the model's safety-evaluation rollout could surface gaps before the FTC probe even completes its initial review.
4. EARNINGS: Accenture Soars 17% on a Fiscal Q4 Beat as Micron's Revenue Nearly Quadruples and McCormick Tops Estimates
Accenture (NYSE:ACN) shares surged 17% after fiscal fourth-quarter revenue of $18.68 billion topped its own guidance of $17.75 billion to $18.4 billion and consensus estimates of $18.3 billion, with Earnings of $3.29 per share also beating expectations and FY27 guidance of 3% to 6% local-currency growth coming in above Street estimates. Micron (NASDAQ:MU) reported adjusted earnings of $33.42 per share on revenue of $54.23 billion, both well above the $31.61 per share and $51.07 billion analysts polled by LSEG had expected, but its shares fell slightly even as peers rallied, with the Roundhill Memory ETF up more than 1% and the VanEck Semiconductor ETF up 1%. McCormick (NYSE:MKC) shares rose nearly 5% after fiscal third-quarter adjusted earnings of 86 cents per share beat the 76-cent estimate on revenue of $2.02 billion against a $1.98 billion consensus.
- Micron's results beating by a wide Margin while its own stock lags the chipmakers that rallied on its numbers shows the market treating the earnings as validation for the broader AI-memory trade rather than as a reason to re-rate Micron specifically.
- Risk note: Accenture's 17% move prices in a clean beat-and-raise outcome, so any sign that the FY27 guidance range proves optimistic would leave the stock with the furthest to fall among today's earnings movers.
5. PARAMOUNT/WBD: A Judge Clears Paramount to Close Its $110 Billion Warner Bros Discovery Deal as Mattel's Kreiz Joins as Co-CEO
A US judge approved Paramount's (NASDAQ:PSKY) settlement with a California-led group of 12 states, clearing the way to close its $110 billion Acquisition of Warner Bros Discovery (NASDAQ:WBD) on October 6 after a months-long legal holdup. Under the settlement, the combined company must release at least 30 films a year in US theaters for 5 years, spend an extra $300 million annually on US production, negotiate cable deals separately for the companies' channels, and create a journalist board overseeing CBS News and CNN, with a Miramax sale possible if the film Quota is missed; the companies also settled a Writers Guild lawsuit for $17.5 million. Separately, Mattel (NASDAQ:MAT) chief executive Ynon Kreiz will join Paramount on October 5 as co-CEO alongside chairman David Ellison once the deal closes, leading day-to-day operations and integration toward more than $6 billion in targeted Merger savings; Kreiz departs Mattel just a day after Roger Lynch was named his successor there.
- Settling antitrust objections with production quotas and editorial oversight rather than blocking the deal outright shows regulators opting for ongoing behavioral conditions over a structural remedy for one of the largest media mergers in history.
- Risk note: the journalist oversight board and separate cable-negotiation requirements are new operating constraints on a newly combined company, so integration execution under co-CEOs Kreiz and Ellison will be tested against both financial targets and these legal conditions at once.
6. JOBS: Weekly Jobless Claims Fall to 197,000, Near a 57-Year Low, as September Layoffs Drop 18%
Initial jobless claims fell by 1,000 to 197,000 in the week ended September 26, below the 200,000 expected and near July's 60-year low of 189,000, while continuing claims fell 11,000 to 1.701 million, the lowest since April 2023. Planned layoffs by US employers dropped 18% to 43,281 in September and are down 39% so far this year compared with the same period in 2025, according to Challenger, Gray & Christmas, whose chief revenue officer said companies are in "a wait-and-see period" amid high energy costs, the Iran war and a recent rate hike. Hiring announcements rose to 90,787 in September from 12,325 in August but remained 23% below a year earlier, the lowest September tally since 2011, with the usual seasonal hiring surge notably absent. A separate Conference Board survey found the share of consumers calling jobs "plentiful" fell in September to its lowest since February 2021. Nonfarm payrolls are expected to show a 90,000 gain for September, with Unemployment seen holding at 4.1%.
- Layoffs falling sharply while hiring intentions stay historically weak shows employers holding onto workers without expanding headcount, a freeze-in-place pattern rather than either an improving or deteriorating labor market.
- Risk note: with hiring at its lowest September level since 2011 and consumer views on Job availability at a multi-year low, any uptick in layoffs from current lows could translate quickly into weaker payrolls given how little rehiring cushion currently exists.
7. PRE-MARKET MOVERS: Rocket Lab Jumps on Its Largest-Ever Electron Contract as Nu Holdings Denies a Monzo Deal and Vicor Surges 14% on Raised Guidance
Rocket Lab (NASDAQ:RKLB) shares rose about 5% pre-market after signing a multiyear deal for 20 new Electron launches with Japan's Synspective, the company's largest-ever commercial launch contract, lifting its total Electron bookings to 47 missions and its overall Backlog past 100 missions. Nu Holdings (NYSE:NU) gained nearly 6% after denying media speculation that it is pursuing an acquisition of UK digital bank Monzo. Vicor (NASDAQ:VICR) surged nearly 14% after raising its third-quarter revenue growth guidance for the second time this month, to above 30% from a prior outlook above 20%, citing accelerating Royalty income from its first non-exclusive Vertical Power Delivery licensing agreement. Monte Rosa Therapeutics (NASDAQ:GLUE) rose about 3% to 4% after positive Phase 1 data for MRT-8102, its NEK7-directed molecular glue degrader, showing dose-consistent target degradation and near-normal inflammatory biomarker levels with no serious adverse events. Dollar Tree (NASDAQ:DLTR) rose 1.3% after a Loop Capital upgrade to buy, citing a favorable macro backdrop for the holiday season.
- Rocket Lab and Vicor both jumping on contract and licensing news rather than on quarterly results shows forward bookings and royalty guidance carrying as much weight with investors right now as reported earnings.
- Risk note: Vicor's stock already trades at roughly 93 times trailing earnings after its 2nd guidance raise this month, so the shares are pricing in sustained royalty growth that depends on continued licensing uptake rather than the single agreement reported so far.


 Oct 29, 2026





 Please wait processing your request...