
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Health Care (XLV) and Utilities (XLU) remain the market's primary leaders, continuing to occupy the Leading quadrant with strong relative strength and positive momentum.
- Consumer Discretionary (XLY) remains the standout sector in Improving, steadily advancing toward the Leading quadrant and signalling strengthening investor confidence.
- Industrials (XLI) has entered the Weakening quadrant, indicating that momentum has deteriorated despite maintaining positive relative strength.
- Consumer Staples (XLP) remains in Weakening, joining Financials (XLF), Materials (XLB), and Real Estate (XLRE) as sectors experiencing declining momentum.
- Technology (XLK), Energy (XLE), and Real Estate (XLRE) remain among the weakest relative performers, reflecting ongoing institutional preference for defensive leadership and selective cyclical exposure.
The latest Relative Rotation Graph (RRG) for July 7, 2026, suggests that market leadership remains concentrated in defensive sectors, particularly Health Care and Utilities. While broader market participation remains healthy, leadership has become more selective as investors favour sectors offering stable earnings visibility and resilience. At the same time, Consumer Discretionary continues to strengthen, emerging as one of the most promising candidates to join the Leading quadrant in the coming weeks.
US Sector Relative Momentum Summary
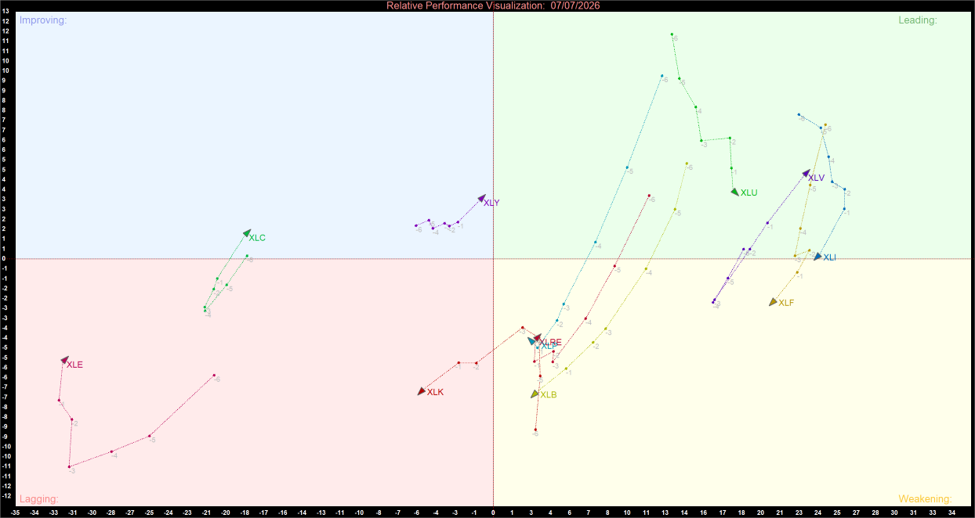
US Sector Relative Momentum Chart (at the closing price of 07/07/2026). Powered by: amibroker.com
Key Market Theme
The Leading Quadrant (The Market Leaders)
- Health Care (XLV) remains one of the strongest sectors on the RRG, continuing to advance within the Leading quadrant. The sector's trajectory reflects both improving momentum and strong relative strength, reinforcing its position as a preferred destination for investors seeking defensive growth opportunities. Stable earnings visibility and resilient business fundamentals continue to attract institutional capital, allowing Health Care to maintain leadership despite changing market conditions.
- Utilities (XLU) also remain firmly positioned in the Leading quadrant. Although momentum has moderated from previous highs, the sector continues to exhibit superior relative strength compared with the broader market. The persistence of Utilities within Leading highlights investors' ongoing preference for predictable cash flows and defensive characteristics, particularly during periods of increased uncertainty surrounding economic growth and market valuations.
The Improving Quadrant (Emerging Leaders)
- Consumer Discretionary (XLY) remains the only sector firmly established within the Improving quadrant and continues to display one of the most constructive rotations on the chart. The sector's north-eastern trajectory indicates strengthening momentum and steadily improving relative performance. Should this trend persist, Consumer Discretionary appears well positioned to transition into the Leading quadrant, potentially signalling a broader improvement in investor confidence toward cyclical growth sectors.
- Communication Services (XLC) has successfully moved into the Improving quadrant after spending an extended period recovering from relative weakness. The sector's improving momentum suggests institutional demand is gradually returning, while continued strength could pave the way for a future move toward market leadership.
The Weakening Quadrant (Losing Momentum)
- A notable development during the latest rotation period is the movement of Industrials (XLI) into the Weakening quadrant. While the sector continues to maintain positive relative strength, the loss of momentum indicates that leadership is beginning to fade. This transition suggests investors are becoming more selective toward economically sensitive sectors, even though the broader outlook for Industrials remains constructive.
- Financials (XLF) remain in Weakening and continue to exhibit declining momentum. Although the sector still maintains respectable relative strength, a sustained recovery in momentum will be required before Financials can challenge for leadership once again.
- Materials (XLB) remain within Weakening but have shown signs of stabilisation in recent periods. The sector appears to be attempting to establish a base, and further improvements in momentum could eventually support a rotation back toward Leading.
- Consumer Staples (XLP) also remain in Weakening. Despite retaining positive relative strength, momentum continues to deteriorate. This suggests that while investors still value the sector's defensive characteristics, capital is increasingly being directed toward stronger opportunities elsewhere within the market.
The Lagging Quadrant (Underperformers)
- Information Technology (XLK) remains firmly positioned within the Lagging quadrant. Although Technology has experienced periods of strong absolute price performance, the RRG indicates that the sector continues to underperform the broader market on a relative basis. While there are early signs of stabilisation, additional evidence of improving momentum is required before a meaningful recovery can be confirmed.
- Energy (XLE) remains deeply entrenched in the Lagging quadrant and continues to be one of the weakest sectors on the chart. Despite posting the strongest daily sector gain in the latest trading session, the sector's longer-term relative performance remains poor. This divergence highlights the difference between short-term price movements and broader relative-strength trends.
- Real Estate (XLRE) has also slipped into Lagging, reflecting continued relative weakness. Although the sector has shown occasional signs of recovery, relative strength and momentum remain insufficient to support a sustainable improvement in leadership status.
Strategic Summary
The latest RRG profile suggests that defensive leadership remains firmly intact, with Health Care and Utilities continuing to outperform on both a relative strength and momentum basis. Meanwhile, Consumer Discretionary and Communication Services are emerging as the most promising improving sectors, indicating that investor confidence is gradually returning to selected growth-oriented areas of the market.
The transition of Industrials into the Weakening quadrant represents the most significant change in sector leadership this week, while Consumer Staples continues to lose momentum despite maintaining positive relative strength. Technology, Energy, and Real Estate remain the weakest relative performers and require further improvement before their outlooks can become more constructive.
Overall, the sector rotation landscape continues to favour defensive leadership while selectively rewarding sectors demonstrating improving momentum. If current trends persist, Consumer Discretionary may become the next sector to enter the Leading quadrant, potentially broadening market leadership beyond its current defensive bias.

 Nov 04, 2026
 Please wait processing your request...