
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Industrials (XLI), Utilities (XLU), and Health Care (XLV) remain firmly in the Leading quadrant, continuing to demonstrate superior relative strength versus the broader market.
- Consumer Discretionary (XLY) remains the sole sector in the Improving quadrant, with momentum strengthening and a potential transition into Leading becoming increasingly likely.
- Technology (XLK) remains in the Lagging quadrant despite being the strongest-performing sector on the day, suggesting that relative leadership has yet to be fully restored.
- Financials (XLF), Materials (XLB), Consumer Staples (XLP), and Real Estate (XLRE) remain in Weakening, although several sectors continue to show signs of stabilisation.
- Energy (XLE) remains the weakest sector on the Relative Rotation Graph, reflecting persistent relative underperformance and weak institutional demand.
The latest sector rotation data for July 6, 2026, suggests that market leadership remains concentrated in Industrials, Utilities, and Health Care, while Technology continues its recovery from a period of relative weakness. Although Technology led daily sector performance, the Relative Rotation Graph (RRG) indicates that investors continue to favour a broader range of sectors rather than relying solely on growth-oriented technology stocks. The current rotation profile points to a market environment where leadership is becoming increasingly diversified.
US Sector Relative Momentum Summary
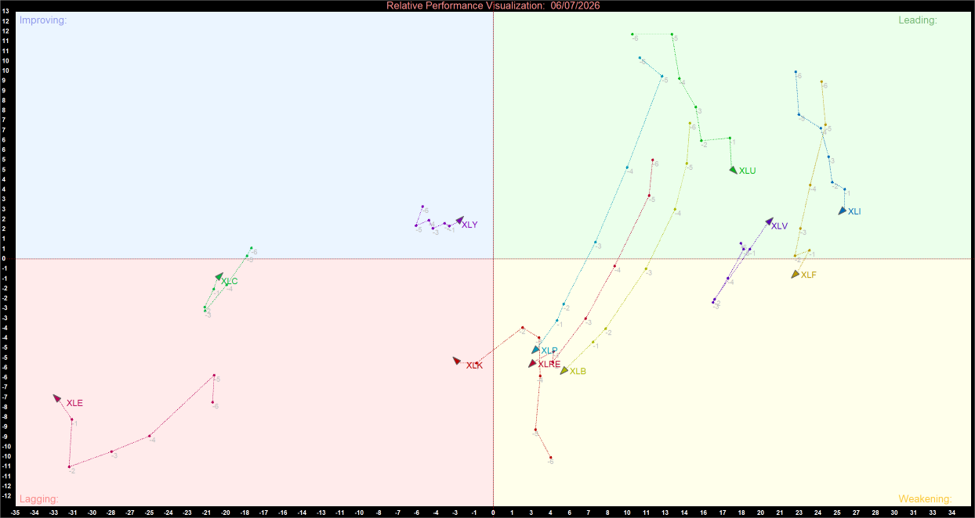
US Sector Relative Momentum Chart (at the closing price of 06/07/2026). Powered by: amibroker.com
Key Market Theme
The Leading Quadrant (The Market Leaders)
- Industrials (XLI) remain firmly positioned within the Leading quadrant. Although momentum has moderated from recent highs, the sector continues to exhibit strong relative strength and remains one of the market's most consistent leaders. Continued institutional interest reflects confidence in infrastructure spending, capital investment, and economic resilience.
- Utilities (XLU) continue to occupy a strong position within Leading. While momentum has eased slightly during recent periods, relative strength remains robust. The sector's ability to maintain leadership suggests investors continue to value earnings stability and defensive characteristics despite the broader market's risk-on tone.
- Health Care (XLV) has strengthened further within the Leading quadrant. The sector's trajectory indicates improving momentum and growing relative strength, reinforcing its status as one of the market's preferred defensive growth opportunities. Institutional demand remains strong as investors seek stable earnings visibility.
The Improving Quadrant (Emerging Leaders)
- Consumer Discretionary (XLY) remains the only sector in the Improving quadrant. The sector continues to move north-east, indicating strengthening momentum and steadily improving relative performance.
- The current trajectory suggests Consumer Discretionary is one of the strongest candidates to enter the Leading quadrant in coming weeks. Continued strength in consumer spending and economic activity could further support the sector's rotation toward leadership.
The Weakening Quadrant (Losing Momentum)
- Financials (XLF) remain in Weakening but continue to hold relatively strong levels of relative strength. The sector sits near the border of the Leading quadrant, suggesting only modest momentum deterioration. A renewed improvement in momentum could quickly return Financials to leadership.
- Materials (XLB) continue to improve within Weakening. The sector has been gradually recovering from earlier weakness and appears to be building a base for a potential transition toward Leading if momentum continues to strengthen.
- Consumer Staples (XLP) remain in Weakening but have shown notable improvement in recent observations. Although still considered a defensive sector, the improving trajectory suggests investors are becoming more constructive toward stable earnings businesses.
- Real Estate (XLRE) remains in Weakening as it continues to recover from a period of significant underperformance. Improving momentum suggests the sector may attract additional interest if interest-rate expectations become more favourable.
The Lagging Quadrant (Underperformers)
- Information Technology (XLK) remains in the Lagging quadrant despite posting the strongest daily gain of all sectors, rising 1.65%. This divergence highlights the difference between short-term price performance and longer-term relative trends.
- Encouragingly, Technology's tail has begun moving north-east, suggesting relative momentum is improving. If this recovery continues, the sector could eventually transition into the Improving quadrant. However, additional evidence of sustained relative strength is still required before leadership is fully restored.
- Communication Services (XLC) remain in Lagging but continue to recover steadily. The sector's improving trajectory indicates that institutional selling pressure is easing, and a move toward Improving may occur if momentum remains positive.
- Energy (XLE) remains the weakest sector on the chart. Although the sector has stabilised somewhat, both relative strength and momentum remain deeply negative. Energy continues to lag the broader market and remains the least favoured sector from a relative performance perspective.
Strategic Summary
The latest sector rotation profile suggests that market leadership remains concentrated in Industrials, Utilities, and Health Care, while Consumer Discretionary continues to emerge as a potential future leader. The most notable development is the gradual recovery underway in Technology and Communication Services, although both sectors remain within the Lagging quadrant and require further improvement before regaining leadership status.
Meanwhile, Financials, Materials, Consumer Staples, and Real Estate remain in Weakening but are showing signs of stabilisation rather than outright deterioration. This suggests that market leadership is broadening rather than narrowing, a development that is generally constructive for the overall market.
Overall, the RRG continues to paint a positive picture for US equities. While defensive sectors remain influential, the improving trajectories of Consumer Discretionary and Technology indicate that investor confidence is gradually returning to growth-oriented areas of the market. If current trends persist, leadership may become increasingly diversified across both cyclical and defensive sectors in the weeks ahead.

 Nov 18, 2026


 Please wait processing your request...