
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Information Technology (XLK) remains the only sector positioned in the Leading quadrant, maintaining the strongest relative momentum position.
- Utilities (XLU), Materials (XLB), Consumer Discretionary (XLY), Industrials (XLI) and Consumer Staples (XLP) occupy the Improving quadrant.
- Health Care (XLV) has entered Lagging, indicating negative relative strength and momentum.
- Financials (XLF), Real Estate (XLRE), Energy (XLE) and Communication Services (XLC) remain in Lagging alongside Health Care.
- No sectors are currently positioned in the Weakening quadrant.
- The concentration of five sectors in Lagging highlights persistent relative weakness across a substantial portion of the US sector universe.
- The current configuration indicates selective momentum improvement rather than a broad-based transition toward stronger sector leadership.
The US sector momentum structure on 8 October 2026 remains characterised by concentrated Technology Leadership and an uneven recovery among the remaining sectors. Information Technology (XLK) continues to occupy the Leading quadrant, while Utilities, Materials, Consumer Discretionary, Industrials and Consumer Staples are positioned in Improving. Health Care has moved into Lagging, joining Financials, Real Estate, Energy and Communication Services. The latest configuration suggests that several sectors are attempting to recover, although the broader momentum structure has yet to demonstrate widespread relative strength.
Momentum Breakdown by Quadrant
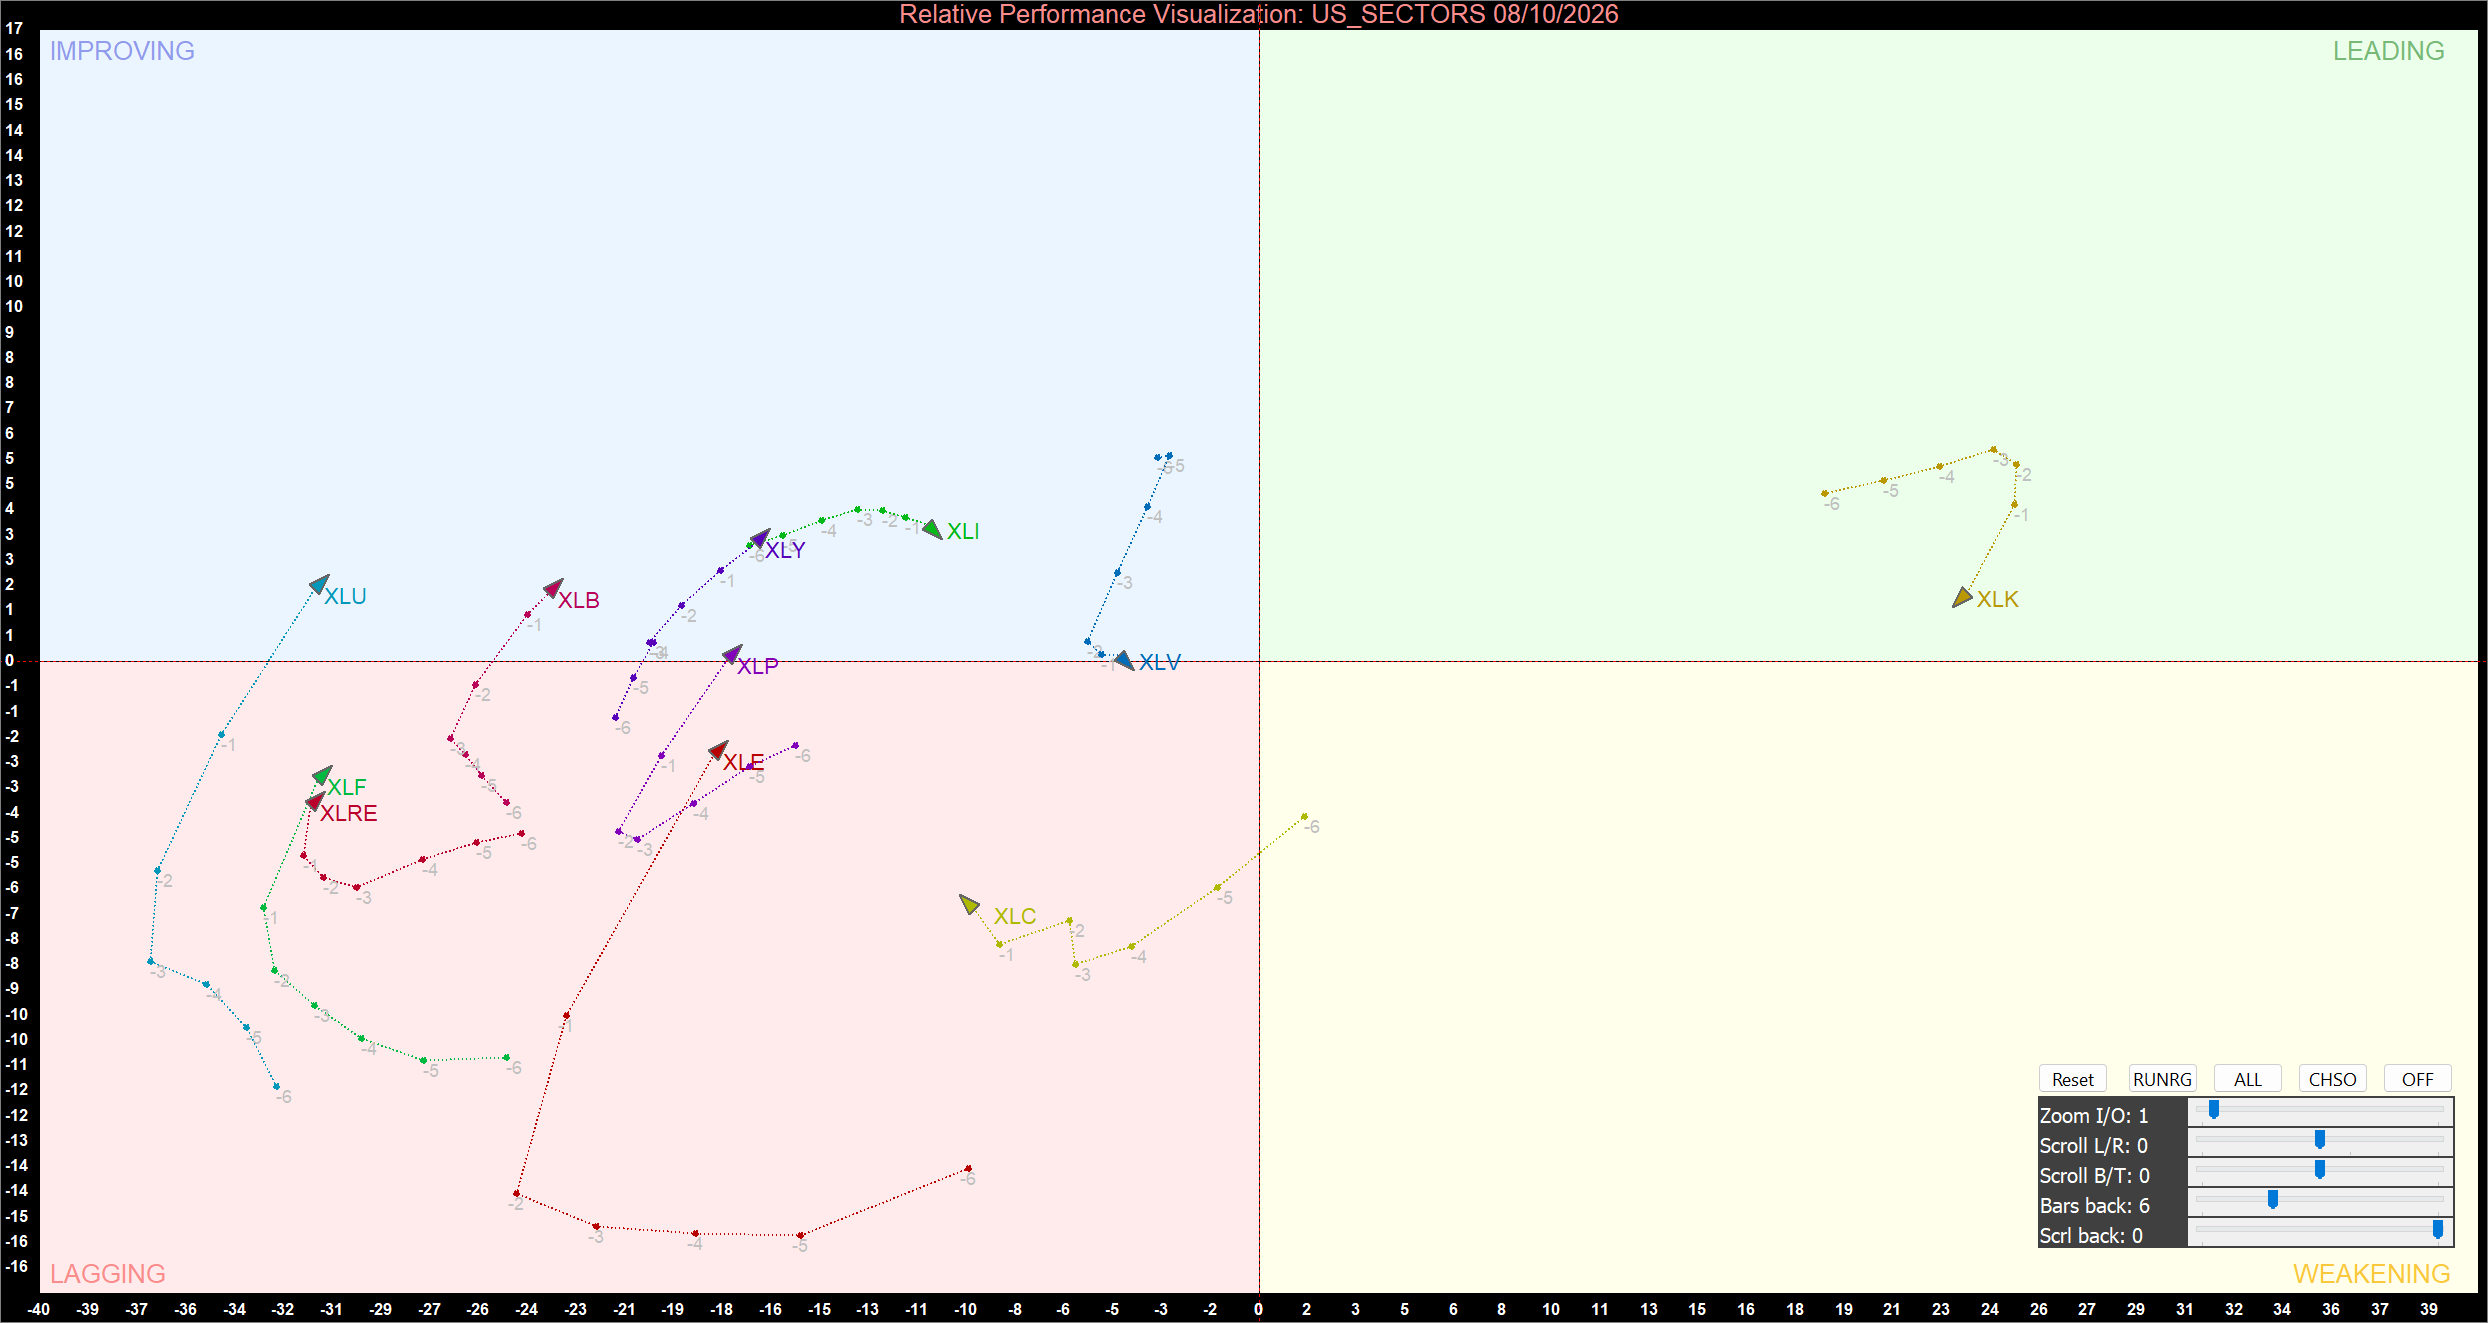
US Sector Relative Momentum Chart at the closing price of 08/10/2026. Powered by: amibroker.com.
Technology Remains the Leading Sector
Information Technology (XLK) remains the only sector positioned in the Leading quadrant. Its location in the upper-right portion of the relative momentum chart indicates comparatively strong relative performance and positive momentum. The trajectory shows that Technology continues to occupy a position clearly separated from most other sectors, reinforcing its status as the principal area of relative strength.
However, the recent trajectory also deserves attention. Although XLK remains above both central axes, its latest movement has turned sharply downward from its previous position. This suggests that momentum may be moderating despite the sector retaining its Leading classification. A sustained recovery in the trajectory would reinforce its leadership, whereas continued movement toward the centre could signal a gradual deterioration in relative momentum.
The distinction between the sector's current position and its recent direction is important. Leading identifies an established relative strength position, but it does not guarantee that momentum will continue improving. XLK therefore remains the sector to monitor for evidence of renewed acceleration or further loss of momentum.
Five Sectors Move Within Improving
Utilities (XLU), Materials (XLB), Consumer Discretionary (XLY), Industrials (XLI) and Consumer Staples (XLP) are positioned in the Improving quadrant. Their locations above the horizontal axis but to the left of the vertical axis indicate positive momentum characteristics without the relative strength required to enter Leading.
Utilities has advanced from a deeply negative position toward the upper-left quadrant. Its trajectory represents a substantial recovery in momentum, although the sector still needs to move farther toward the vertical centre line to establish stronger relative performance. Materials also remains in Improving after recovering from weaker territory, with its latest position indicating positive momentum but incomplete relative-strength recovery.
Consumer Discretionary has moved upward toward the boundary between Improving and Leading, although its position remains on the left side of the chart. Continued movement toward the upper-right would provide stronger evidence of improving relative performance. Industrials, meanwhile, remains in Improving but has turned downward from its recent trajectory. This Reversal suggests that the recovery is not yet firmly established and that further deterioration could return the sector toward weaker momentum territory.
Consumer Staples is positioned close to the horizontal boundary. Its location suggests that momentum has recovered toward neutral territory, but the sector has not established a decisive upward trend. Continued movement above the horizontal axis would support its Improving classification, while a renewed decline could indicate a return to Lagging.
Health Care Joins Four Other Sectors in Lagging
Health Care (XLV) has entered the Lagging quadrant, joining Financials (XLF), Real Estate (XLRE), Energy (XLE) and Communication Services (XLC). This transition indicates that Health Care has moved below the horizontal axis while remaining to the left of the vertical centre line, reflecting weakening relative positioning and negative momentum.
XLV's position near the horizontal boundary makes its subsequent trajectory particularly important. A sustained move upward would suggest that the deterioration is stabilising, while continued movement downward would reinforce its Lagging classification. Its transition also demonstrates that previously stronger positioning can deteriorate when relative momentum fails to hold above the centre line.
Financials and Real Estate remain in negative territory, with both sectors positioned in the lower-left quadrant. Their trajectories indicate that relative strength remains weak despite some recovery from previous lows. Energy also remains in Lagging, although its latest position reflects an upward recovery from a substantially weaker area. Communication Services continues to occupy negative territory, with its trajectory showing that a sustained improvement in relative strength has not yet been established.
The presence of five sectors in Lagging remains a significant feature of the chart. These sectors require a sustained upward movement in their trajectories before a transition into Improving can be confirmed.
Momentum Rotation Remains Uneven
The current quadrant structure reinforces the distinction between daily price performance and relative momentum. A sector can record a strong one-day gain while remaining in Lagging because the chart reflects broader relative strength and momentum rather than simply the latest percentage return. Similarly, a sector can decline during a session while retaining a Leading or Improving classification if its broader relative momentum remains comparatively strong.
Technology continues to dominate the upper-right quadrant, while five sectors are attempting to improve from the upper-left area. At the same time, five sectors remain in Lagging, indicating that the recovery has not extended across the entire sector universe. The absence of sectors in Weakening does not, by itself, confirm a broad recovery, as the current configuration still contains a substantial group with negative relative strength and momentum.
Bottom Line
The US sector momentum structure on 8 October 2026 remains concentrated around Technology leadership. XLK is the only sector in Leading, while XLU, XLB, XLY, XLI and XLP form the Improving group. XLV has entered Lagging alongside XLF, XLRE, XLE and XLC, leaving no sectors in Weakening.
From a momentum perspective, Technology retains the strongest relative position, although its recent downward trajectory warrants attention. Utilities, Materials, Consumer Discretionary, Industrials and Consumer Staples are the key sectors to monitor for continued improvement, particularly if their trajectories move farther toward the Leading quadrant. Conversely, the five sectors in Lagging require sustained recovery in relative momentum before their classifications become more constructive. The overall configuration continues to favour selective sector leadership rather than a broad-based momentum advance.


 Oct 28, 2026



 Please wait processing your request...