
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
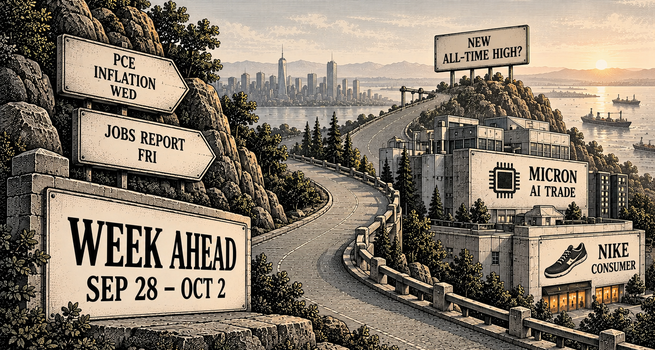
Major Equity indexes hovered near record levels last week, with the S&P 500 less than 1% below its mid-August peak, supported by technology and AI-linked stocks even as the index beneath the surface has shown signs of strain. Eight of eleven S&P 500 sectors are in negative territory for September, and an equal-weight version of the index, often seen as a better barometer of the average stock, was down about 4% for the month. The 30-year Treasury Yield has reached its highest level in over two decades and the 10-year has pushed well above the closely watched 5% threshold, a selloff that investors warn could turn disorderly if it persists. Against this backdrop, the September jobs report on Friday and Wednesday's personal consumption expenditures price index are the week's two most consequential releases, both bearing directly on whether the Federal Reserve, which resumed rate hikes this month for the first time in three years, raises again in October. Fed funds futures already suggest a greater than 60% chance of another quarter-point move. Micron Technology and Nike report Earnings mid-week, testing whether the AI trade and the consumer, respectively, can hold their ground.
Major Ex-Dividend Dates This Week
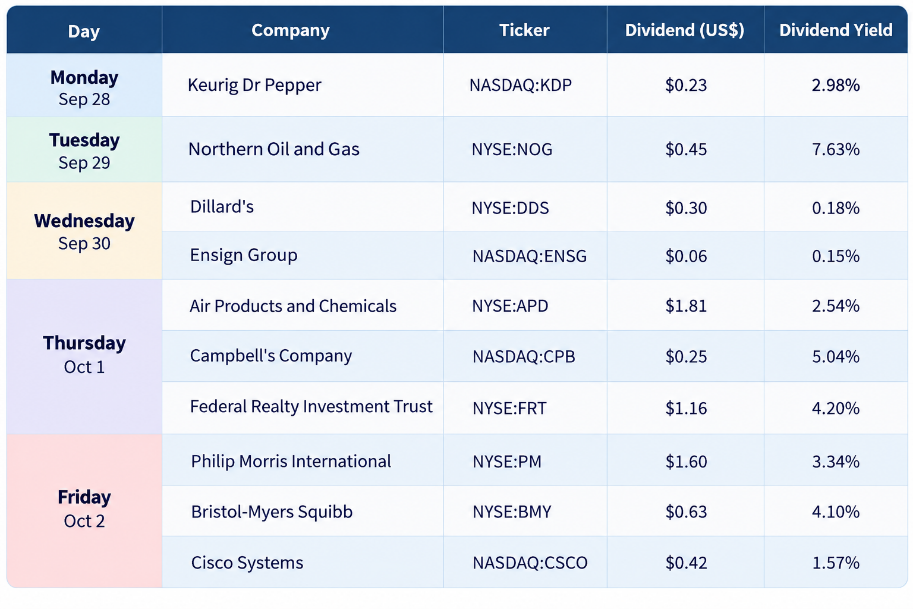
Monday, September 28
Earnings
Vail Resorts (NYSE:MTN) reports in the afternoon, offering an early look at ski season booking trends and discretionary travel spending heading into the winter months.
Federal Reserve
New York Fed President John Williams begins a two-day regional visit to Western New York. No formal policy remarks are scheduled, though any commentary will be parsed closely given how thin the calendar of Fed communication remains under Chair Warsh's preference for limited forward guidance.
Tuesday, September 29
Earnings
CarMax (NYSE:KMX) reports before the open, providing a used-vehicle and consumer Credit read that will be interpreted against the backdrop of rising borrowing costs. AAR Corp (NYSE:AIR) also reports in the afternoon, offering an aerospace maintenance and logistics signal.
Economic Data
The S&P Case-Shiller Home Price Index for July, prior at 0.6%, opens Tuesday's data calendar at 9:00 am ET. The Conference Board Consumer Confidence Index for September, prior at 89.4 and forecast at 89.2, follows at 10:00 am ET, offering a read on household sentiment as yields climb. JOLTS Job openings for August, prior at 7.27 million, are forecast to ease to 7.2 million, the first labour market data point ahead of Friday's payrolls report.
Federal Reserve
Chicago Fed President Austan Goolsbee speaks at an Illinois Manufacturers' Association event at 1:00 pm ET, followed by New York Fed President John Williams at the University at Buffalo at 2:00 pm ET.
Wednesday, September 30
Earnings
Micron Technology (NASDAQ:MU) reports in the afternoon as the week's most closely watched earnings event. The memory chipmaker's Market Value has soared above $1 trillion this year, and its results will be read as a direct signal of whether the AI infrastructure trade, one of the biggest drivers of the semiconductor sector's gains this month, still has room to run. Jabil Circuit (NASDAQ:JBL) also reports before the open, extending the electronics Manufacturing and AI hardware Supply chain read. Conagra Brands (NYSE:CAG), Cal-Maine Foods (NASDAQ:CALM), and Progress Software (NASDAQ:PRGS) round out Wednesday's calendar with consumer staples and enterprise software signals respectively.
Economic Data
Wednesday carries the heaviest data load of the week. ADP private employment for September, prior at 38,000, arrives at 8:15 am ET as the first direct preview of Friday's payrolls, with consensus pointing to a net increase of 70,000 private-sector jobs. The third estimate of Q2 GDP, prior at 1.6%, lands simultaneously. Personal Income for August, prior at 0.4%, and personal spending, prior at 0.2% and forecast to accelerate sharply to 0.8%, arrive at 8:30 am ET alongside the PCE price index. Core PCE is forecast to rise 0.3% month-on-month and 3.2% year-on-year, both accelerating from July's 0.2% and 3.3% readings respectively, a print that, in the words of one strategist, will probably confirm Inflation is still running above target, though any softening from the prior month could offer the market a measure of relief. The advance goods trade balance, prior at -$118.8 billion, and wholesale inventories, prior at 1.3%, round out the morning. The Chicago Business Barometer PMI for September, prior at 47.1 and forecast at 52, closes the day at 9:45 am ET.
Federal Reserve
Chicago Fed President Austan Goolsbee speaks again at 4:00 pm ET on why consumers and economists see different economies, a topic likely to resonate given the gap between resilient headline data and the visible strain among individual stocks this month.
Thursday, October 1
Earnings
Nike (NYSE:NKE) reports in the afternoon, offering the week's clearest read on discretionary consumer spending and global footwear and apparel Demand at a moment when borrowing costs are rising and sentiment beneath the market's surface has softened. Constellation Brands (NYSE:STZ), McCormick (NYSE:MKC), Acuity Brands (NYSE:AYI), and Lamb Weston Holdings (NYSE:LW) also report, spanning beverages, spices, lighting, and frozen foods, a broad cross-section of the consumer economy.
Economic Data
Weekly jobless claims for the week ending September 26, prior at 197,000 and forecast at 200,000, provide the labour market read one day before payrolls. The US Manufacturing PMI for September, prior at 64.6, and the ISM Report on Business Manufacturing PMI, prior at 64.6 and forecast at 64.8, both point to continued strength in the factory sector. Construction spending for August, prior at -0.6%, is forecast to turn modestly positive at 0.1%.
Federal Reserve
Chicago Fed President Austan Goolsbee speaks a third time this week, underscoring how much weight markets are placing on any available Fed commentary given the limited forward guidance from Chair Warsh.
Friday, October 2
Economic Data
The September employment report is the week's defining release. Consensus points to 100,000 jobs added, a deceleration from August's Blowout 162,000, with the Unemployment rate expected to rise to 4.2% from 4.1%. Average hourly earnings are forecast at 0.3% month-on-month and 3.1% year-on-year. The market would likely welcome a print that is good but not great: a number meaningfully above consensus risks being read as further cementing the case for an October hike, while a soft print could ease near-term rate concerns but raise questions about the durability of consumer spending. Factory orders for August, prior at 0.9%, are forecast to ease to 0.2%. Dallas Fed President Lorie Logan speaks at a workshop on the macroeconomic implications of migration, a topic adjacent to but distinct from the immediate rate debate.
Geopolitical Backdrop
The potential for either diplomatic agreements or escalatory strikes between the US, Iran, and GCC states remains a live variable, with high energy prices and resilient economic activity together lifting Global Bond yields to multi-decade highs. The persistence of elevated oil prices has complicated the Fed's task by keeping headline inflation pressure alive even as the Central Bank raises rates, a combination that has proven difficult for equities to absorb in recent weeks. Any credible sign of de-escalation would ease part of the inflationary pressure feeding into Wednesday's PCE data and could provide some relief to the bond market, while a fresh escalation would likely compound the yield pressure that has already left the S&P 500's equal-weight index down roughly 4% this month.
The Week in Context
Two reports carry outsized weight for how the Fed's thinking evolves heading into its next meeting. Wednesday's PCE data will confirm whether the disinflation trend investors are hoping for is intact or whether price pressures are broadening again, while Friday's jobs report will show whether the labour market, which the Fed itself has described as being at full employment, is cooling in an orderly fashion or losing momentum too quickly. Micron's results will test whether the AI trade that has powered technology shares higher this month can continue to do so, and Nike's will offer a read on whether the consumer, arguably the market's last line of defence, remains resilient as borrowing costs climb. With Treasury yields at levels not seen in decades, the combination of this week's data and earnings will do much to determine whether the rally's foundations, still intact on the surface, can withstand what has been building beneath it.

 Oct 30, 2026





 Please wait processing your request...