
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed mostly higher on Wednesday, with the S&P 500 gaining 0.3% and the Nasdaq rising 0.7%, supported by tame Inflation data and strong AI-related earnings. CoreWeave and Super Micro Computer surged around 19%, while Nvidia, Oracle and Micron also advanced on renewed optimism around AI infrastructure. However, the Dow ended nearly flat, and Microsoft, Meta and Amazon declined as Middle East energy-supply uncertainty sustained inflation concerns.
Market Movers
Among the top-performing stocks of the session Boxlight Corporation. surged 168.60%, while TEN Holdings, Inc. rallied 49.86%. On the losing side, National CineMedia, Inc. fell 41.42%, while WF International Limited. declined 39.75%, making them the weakest performers during the trading day.
Commodities Update
WTI crude fell below USD 82 per barrel and Brent slipped below USD 88 on Thursday, ending multi-session rallies as concerns over weakening Demand and a sharp 17.4-million-barrel increase in US crude inventories outweighed persistent Supply disruptions around the Strait of Hormuz. The IEA lowered its global demand outlook and projected a 1.8-million-barrel-per-day supply shortfall this quarter, while stalled US-Iran diplomacy and continued attacks on shipping sustained geopolitical risks. Despite the pullback, both benchmarks remained nearly 5% higher for the week.
Gold slipped below USD 4,400 per ounce and silver fell below USD 65 on Thursday after touching multi-week highs, as investors turned cautious ahead of US producer inflation data. Softer July consumer inflation reduced the probability of a September Federal Reserve rate hike to around 40%, providing some underlying support, while elevated oil prices, stalled US-Iran negotiations and continued uncertainty over reopening the Strait of Hormuz weighed on precious metals.
Macro Updates
US Producer Inflation Expected to Rebound in July
US producer prices are forecast to increase 0.2% month over month in July 2026 after declining 0.3% in June, while core prices are expected to rise 0.3%. Annually, headline and core producer inflation are projected to ease to 4.9% and 4.2%, respectively.
Dollar Holds Near 100 Ahead of US Inflation Data
The dollar index steadied around 100 as investors awaited July’s producer inflation report, while softer consumer inflation reduced expectations of a September Federal Reserve rate hike. Uncertainty surrounding the Strait of Hormuz and possible intervention to support the yen near the 160-per-dollar level also influenced currency markets.
Bonds Commentary
The 10-year US Treasury Yield eased to around 4.68% as investors awaited producer inflation data, while softer July consumer inflation lowered expectations of a September Federal Reserve rate hike. However, persistent inflation and widening fiscal deficits kept long-term borrowing costs elevated, with the latest 10-year note auction recording its highest yield since the global financial crisis.
Futures Update
US Equity futures were largely unchanged ahead of producer inflation data, with the S&P 500 hovering near a record and the Nasdaq 100 and Dow trading flat. AI and semiconductor stocks maintained their momentum, lifting Micron, Nvidia and Amazon, while a softer-than-expected inflation reading could reinforce expectations that the Federal Reserve will hold rates steady next month.
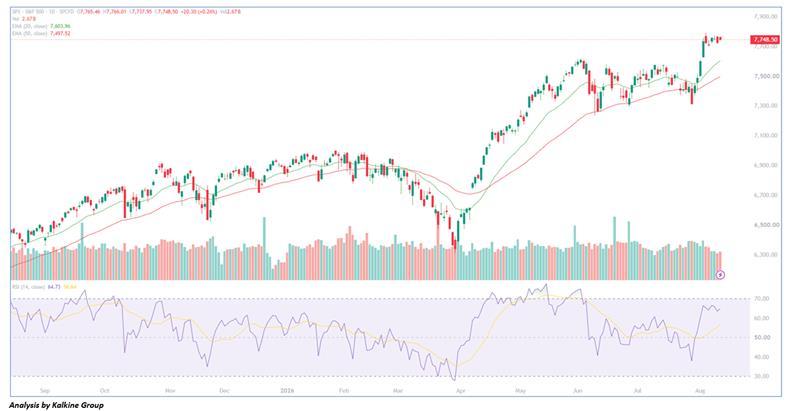
After moving higher early in the session, stocks remained mostly in positive territory on Wednesday, although the pace of buying was relatively subdued. The Nasdaq and S&P 500 both ended the day higher, helping to recover some of the losses recorded at the start of the week. The S&P 500 retains a bullish intraday bias, trading comfortably above its 20-day EMA at 7,603.96 and 50-day EMA at 7,497.52, reinforcing the prevailing uptrend. The index is currently consolidating near 7,750 following its recent breakout to record highs, while the RSI at 64.73 reflects healthy positive momentum without entering overbought territory. A sustained break above 7,766–7,780 could pave the way for further gains toward 7,800–7,850, while support remains around 7,700–7,680, followed by the 20-day EMA near 7,604. Overall, the technical setup remains constructive, with buying on dips likely as long as the index holds above the 7,700 level.

 Nov 18, 2026
 Please wait processing your request...