
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Monday as technology gains outweighed concerns over elevated oil prices and bond yields. The S&P 500 rose 0.7%, the Nasdaq 100 gained 0.9% to a record 31,076, and the Dow added 91 points, supported by strong earnings, consumer spending and AI investment. Alphabet, Meta and Microsoft advanced, while chipmakers were mixed, with Nvidia and Broadcom each gaining 2.1%. Tesla rose 2.2%, while SpaceX climbed 7.6% on reports of potential cooperation between TSMC and Elon Musk’s Terafab initiative.
Market Movers
Among the top-performing stocks of the session NFT Limited. surged 683.00%, while WISeSat.Space Holdings Corp. rallied 260.54%. On the losing side, Stablecoin Development Corporation. fell 47.33%, while Roze AI Inc. declined 35.13%, making them the weakest performers during the trading day.
Commodities Update
Crude oil declined for a third consecutive session on Tuesday, with WTI approaching USD 87 a barrel, its lowest since early September, and Brent nearing USD 98, as recovering Middle Eastern exports eased Supply concerns. Uninterrupted flows through Saudi Arabia’s East-West Pipeline, exports exceeding pre-war levels on several days, and a G7 agreement to release 100 million barrels from emergency reserves added downward pressure. Saudi Arabia also sharply lowered crude prices for Asian buyers, while OPEC+ maintained its November production targets.
Gold fell toward USD 4,100 an ounce on Tuesday, reaching two-month lows, while silver remained below USD 61 near similar lows, as a stronger dollar and Treasury yields at 24-year highs pressured precious metals. European political and fiscal concerns weakened the euro, supporting the dollar, while fiscal risks and persistent Inflation fuelled the Global Bond selloff. Despite rising US services-sector cost pressures, weaker jobs data lifted expectations of an October Fed pause to around 78%, while improving Middle Eastern oil supplies eased energy-related inflation concerns.
Macro Updates
Dollar Eases as Lower Oil Prices Temper Rate-Hike Expectations
The dollar index slipped to 101.8 on Tuesday as recovering Middle Eastern crude exports pushed oil prices to a one-month low, easing inflation concerns and expectations for immediate Fed tightening. The Fed is expected to hold rates unchanged this month, although markets anticipate a 25-basis-point hike in December. The dollar weakened most against the euro, which had fallen on Monday amid French Debt concerns and political deadlock, alongside the prospect of a snap election in Spain.
US Logistics Activity Strengthens as Capacity Tightens
The US Logistics Managers’ Index rose to 70.2 in September 2026 from 66.6 in August, marking its second-highest reading in four years. Faster inventory growth and rising inventory costs intensified storage pressures, with Warehousing capacity contracting at its sharpest pace since March 2022. Warehousing utilisation increased and prices continued to rise strongly, although at a slightly slower pace. Transportation capacity also tightened, while utilisation growth moderated and transportation prices surged further to 92.7 from 90.
Bonds Commentary
The US 10-year Treasury Yield eased to 5.27% on Tuesday from Monday’s 24-year high of 5.33%, as lower fuel prices briefly reduced inflation pressure. Yields have climbed more than 110 basis points this year amid expectations of further Fed tightening, widening federal deficits and increased corporate debt issuance. US services-sector price pressures at a four-year high reinforced rate-hike expectations, while CBO projections showed public debt rising from 101% of GDP this year to over 175% by 2056, highlighting longer-term borrowing pressures.
Futures Update
US Equity futures rose on Tuesday as a pause in rising bond yields supported heavyweight technology stocks. S&P 500 and Nasdaq 100 futures gained around 0.5% to record highs, while Dow futures added 0.4%. AI-related optimism strengthened amid OpenAI’s reported USD 30 billion financing talks with UAE funds and Alphabet’s prospective nuclear-energy agreement with Constellation Energy, lifting their shares nearly 1% and 7%, respectively. AMD rose 2% on an upbeat chip-demand outlook, while Palo Alto Networks, Fortinet and CrowdStrike gained around 2% each.
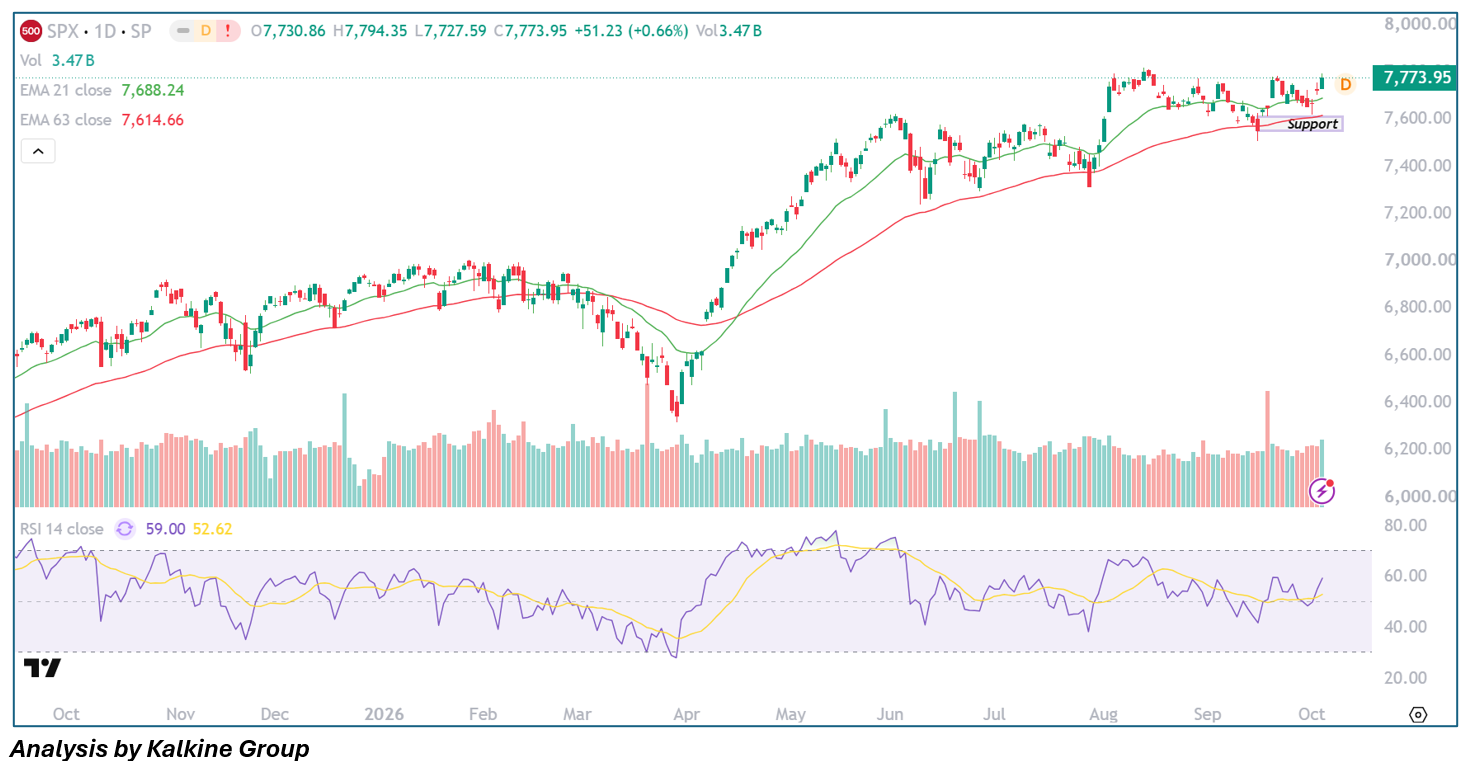
Stocks put in a strong showing for most of Monday's session before easing off into the close. The tech-heavy Nasdaq surged to a new record closing high, and the major averages finished below their intraday peaks but still in the green. On the daily chart, the index opened near 7,731, touched a high of 7,794, and settled at 7,773.95 (+0.66%), forming a green candle that shows buyers kept the upper hand. Resistance sits at 7,794 and then the 7,800-7,820 zone, which marks the top of the range since August, while support lies at the 21 EMA near 7,688 and the stronger 63 EMA/support box around 7,600-7,620. RSI at 59 is rising without being overbought, and price remains above both EMAs, so the bias is bullish, though Volume is only moderate. Intraday, holding above 7,750 and breaking 7,794 would open the way to 7,820 and beyond, while a drop below 7,730 would put 7,688 in play. This is technical analysis, not financial advice

 Nov 15, 2026
 Please wait processing your request...