
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mostly higher on Monday as a rebound in heavyweight AI shares lifted the S&P 500 by 0.4% and Nasdaq 100 by 1.2%, while the Dow ended near flat. Amazon surged 5%, Tesla gained 3.4%, and Micron and Intel rose around 3%, reversing some of last week’s technology weakness. Banking shares declined following Earnings releases, with Morgan Stanley, Bank of America and Wells Fargo falling between 1% and 2.5%.
Market Movers
Among the top-performing stocks of the session SCWorx Corp. surged 94.20%, while Disc Medicine, Inc. rallied 38.86%. On the losing side, Iambic Therapeutics, Inc. fell 31.37%, while Cango Inc. declined 29.74%, making them the weakest performers during the trading day.
Commodities Update
Oil prices rose on Tuesday, with crude exceeding USD 100 per barrel to reach a four-week high and Brent surpassing USD 111 to hit a five-month peak, as renewed Houthi attacks on Saudi facilities and reported vessel strikes heightened Middle East Supply concerns. Kpler reported at least 18 vessels attacked over the past two weeks, reinforcing the geopolitical risk premium. Expectations of lower US crude and refined-product inventories also supported prices, although analysts noted that the premium could ease if oil shipments remain uninterrupted.
Gold fell toward USD 4,100 per ounce on Tuesday, marking its third consecutive decline, while silver slipped to around USD 56.5 as elevated oil prices fuelled Inflation concerns and expectations of tighter monetary policy. A stronger US dollar and rising bond yields added pressure amid ongoing geopolitical tensions. The Federal Reserve is expected to hold rates steady next week, although markets priced in roughly a 94% probability of a December hike, while further tightening remained possible in Europe and Japan.
Macro Updates
Dollar Eases as Markets Assess Fed Policy Outlook
The US dollar index slipped below 102 on Tuesday as investors awaited the Fed’s October 27–28 meeting and upcoming PCE inflation data. Markets priced in an 83% chance of unchanged rates next week and a 94% probability of a December hike, while Fed Chair Kevin Warsh offered no clear policy signal. The euro recovered modestly amid efforts to contain unrest in Europe, while the yen weakened despite hawkish remarks from Bank of Japan Governor Kazuo Ueda.
Bonds Commentary
The US 10-year Treasury Yield held near 5.13% on Tuesday as investors awaited the Fed’s October 27–28 meeting and upcoming PCE inflation data. Markets priced in an 83% probability of unchanged rates next week and a 94% chance of a December hike. Fed Chair Kevin Warsh offered no clear policy signal, while elevated oil prices sustained inflation concerns and upward pressure on Global Bond yields.
Futures Update
US stock futures were mostly lower on Tuesday as concerns over data centre financing weighed on technology shares. Nasdaq 100 futures fell 0.6%, while S&P 500 futures edged down and Dow futures were flat. Elice plunged 32% following its IPO, CoreWeave dropped 5% premarket, and Micron, Marvell and Arm declined nearly 3%. SpaceX slipped 1% ahead of earnings, while Walmart, ExxonMobil and Eli Lilly gained over 1%.
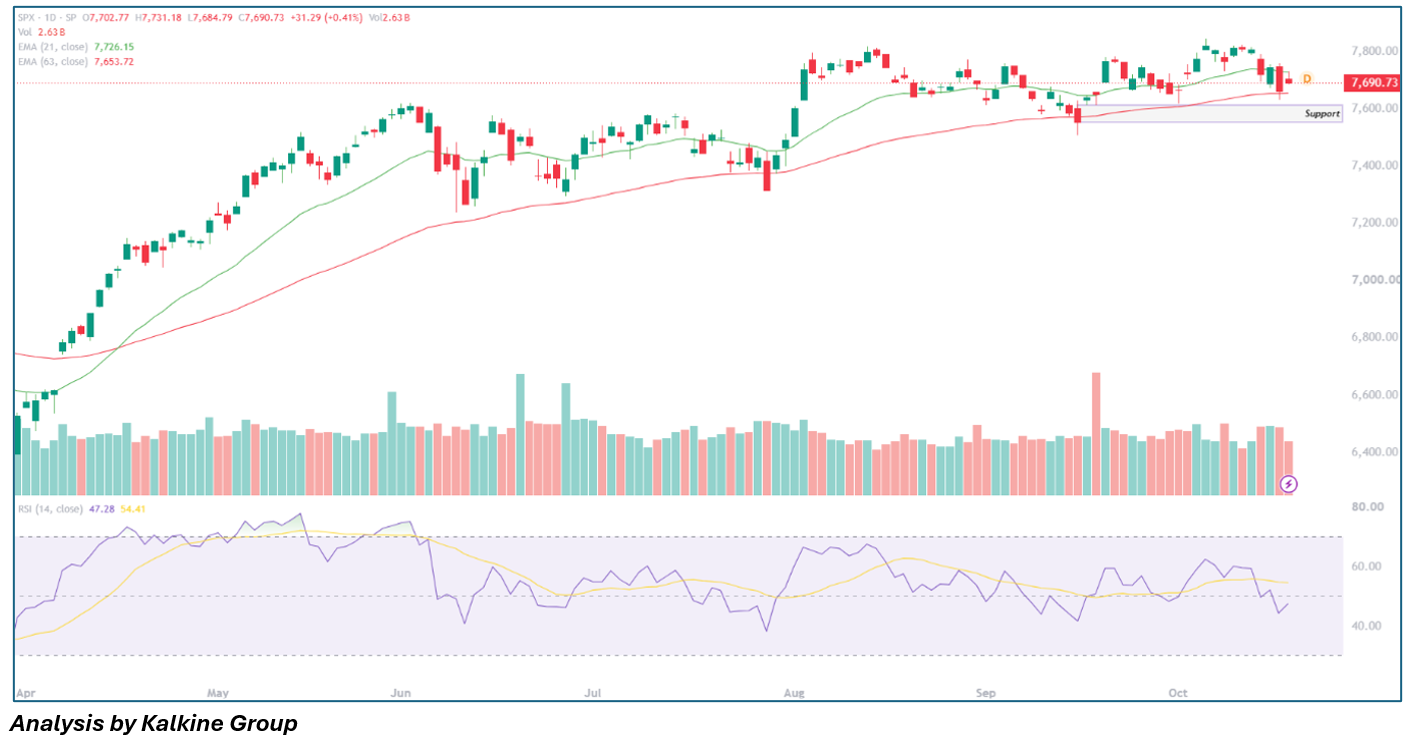
Stocks rebounded on Monday after Friday’s sell-off, with technology shares leading the advance and lifting the tech-heavy Nasdaq notably higher. The S&P 500 (SPX) is at 7,690.73 (+0.41%), recovering modestly from a pullback off its early-October high near 7,830. It trades between the 21-EMA (7,726) above and the 63-EMA (7,654) below. The uptrend that began in April remains intact, but lower highs, an RSI of 47.28 sitting under its signal line (54.41), and thinning Volume on the bounce suggest momentum is cautious and leaning neutral-to-weak. Resistance sits at the 21-EMA, followed by the 7,800+ area, while support lies at the 63-EMA and the 7,560-7,610 zone. A hold above 7,654 favors further upside, whereas a close below it could lead to a test of that support zone. This analysis is based on a Daily Chart rather than true intraday data and is not financial advice.

 Oct 29, 2026
 Please wait processing your request...