
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks mostly rose on Tuesday as technology shares rebounded ahead of major earnings, with the S&P 500 gaining 0.6%, the Nasdaq rising 1.3% and the Dow finishing flat. Broadcom climbed 4% on $63 billion in financing linked to Anthropic’s use of its technology, while Oracle gained 3.6% after expanding its OpenAI partnership. Meta fell 1.6% despite strong Demand for its stock offering, and Boeing plunged 10.7% following a larger-than-expected quarterly loss. Investors also awaited the Federal Reserve’s expected decision to hold rates steady.
Market Movers
Among the top-performing stocks of the session Nuwellis, Inc. surged 74.69%, while Braiin Limited. rallied 56.13%. On the losing side, Artiva Biotherapeutics, Inc. fell 30.68%, while Clearwater Paper Corporation. declined 28.77%, making them the weakest performers during the trading day.
Commodities Update
Crude oil rose above $101 a barrel and Brent surpassed $115 on Wednesday, recovering from two sessions of losses amid concerns over renewed US–Iran military escalation. Reports of possible US strikes, additional military deployments, political uncertainty in Israel and Houthi attacks on Saudi energy infrastructure heightened Supply concerns. However, hopes for a diplomatic breakthrough following reports of a new Qatar-mediated draft agreement with Iran limited gains.
Gold fell below $4,050 an ounce and silver dropped below $54 on Wednesday, ending two sessions of gains as investors awaited the Federal Reserve’s policy decision and signals of a possible December rate hike. The Reserve Bank of New Zealand unexpectedly held rates steady, while uncertainty surrounding Israel’s election and potential US strikes on Iran kept geopolitical risks elevated. Both metals remained under pressure as conflict-driven Inflation concerns reinforced expectations for higher interest rates, reducing their appeal.
Macro Updates
US Mortgage Applications Rebound as Borrowing Costs Ease
US mortgage applications rose 3.4% in the week ended October 23, snapping seven consecutive weekly declines as the average 30-year fixed mortgage rate fell for a second week to 7.37%. Home purchase applications increased 3.8%, while refinancing applications gained 2.7%. However, elevated home prices and mortgage rates remaining more than one percentage point above year-earlier levels continued to constrain affordability, while homeowners with cheaper existing loans had limited incentives to refinance.
Fed Expected to Hold Rates as Inflation Pressures Persist
The Federal Reserve is widely expected to hold rates at 3.75%–4.00% in October following September’s 25-basis-point hike, with investors watching Chair Kevin Warsh’s comments for signals of another increase in December. September consumer inflation accelerated to 3.7%, while producer prices rose 6.3% annually, both exceeding expectations. Elevated oil prices continue to fuel inflation concerns, while the labor market remains characterized by subdued hiring and layoffs.
Dollar Holds Firm Ahead of Fed Decision
The US dollar index held near 102.4 on Wednesday after three consecutive sessions of gains as investors awaited the Federal Reserve’s policy decision and signals of a possible December rate hike. Attention also turned to Alphabet and Microsoft Earnings for insights into AI demand. The dollar gained over 1% against the New Zealand dollar after the RBNZ unexpectedly held rates steady, while policy decisions in Canada, the Euro Area and Japan remained in focus.
US Crude Inventories Fall Unexpectedly as Fuel Stocks Rise
US crude inventories declined by 2.031 million barrels in the week ended October 23, against expectations for an 800,000-barrel increase, while Cushing stocks fell by 453,000 barrels. Gasoline and distillate inventories rose by 2.39 million and 380,000 barrels, respectively. Separately, US oil production decreased to 13.269 million barrels per day in the week ended October 16, from 13.679 million a week earlier.
Bonds Commentary
The US 10-year Treasury Yield edged above 5% on Wednesday as investors awaited the Federal Reserve’s policy decision, signals of a potential December rate hike, and upcoming GDP and PCE inflation data. Improving sentiment toward artificial intelligence weakened demand for safe-haven bonds, while major technology earnings were expected to provide further insight into AI demand and its contribution to economic growth.
Futures Update
US stock futures held steady on Wednesday as investors awaited the Federal Reserve’s policy decision, signals of a possible December rate hike, and earnings from Alphabet and Microsoft. On Tuesday, the S&P 500 rose 0.6% and the Nasdaq gained 1.18%, led by technology stocks. Sentiment benefited from $63 billion in financing tied to Anthropic’s use of Broadcom technology, strong demand for Meta’s $25 billion share offering, and Oracle’s expanded Partnership with OpenAI.
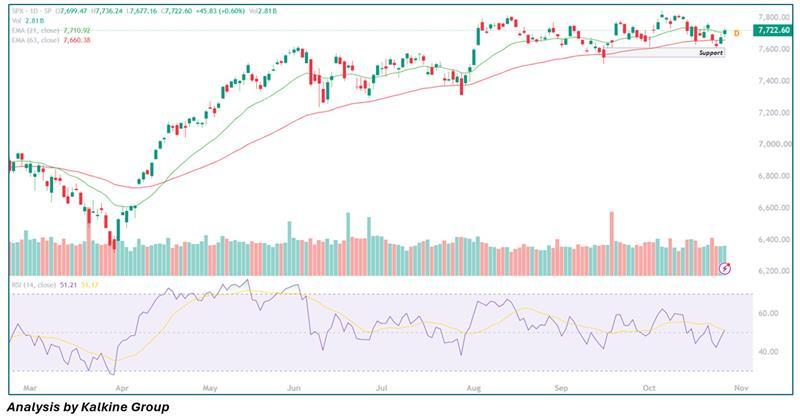
U.S. stocks kept climbing on Tuesday, building on Monday’s positive tone, with technology shares leading the way. The Nasdaq posted a sharp gain, bouncing further from the two-month closing low it set late last week as renewed enthusiasm around artificial intelligence drew buyers back in on the dip. The S&P 500 (SPX) rose 0.60% (+45.83 points) to close at 7,722.60. It held above its session low of 7,677.16 and kept the key 7,580–7,600 support zone intact. The rally pushed the index back above its 63-day EMA (7,660.38) and the descending 21-day EMA (7,710.92), which had been acting as resistance. Momentum is improving as well. The 14-day RSI turned up to 51.21, recapturing the 50 midline and nearly matching its 51.17 signal line, a sign that selling pressure is fading. As long as the index stays above the 21-day EMA (7,710.92) and the session low (7,677.16), the next near-term level to watch is the intraday high of 7,736.24. Beyond that, the extended upside targets sit in the 7,780–7,800 resistance zone.

 Oct 29, 2026
 Please wait processing your request...