
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Wednesday, with the S&P 500 gaining 0.6%, Nasdaq rising 1.1% and Dow adding 360 points as upbeat SpaceX results and strong Super Micro Computer guidance revived optimism over AI demand. SpaceX surged 7.8% and Super Micro jumped 9.5%, supporting broader gains in space, hardware and semiconductor stocks. Tesla rose 3.4% amid Merger speculation, while Netflix fell 5.3% on a weak profit forecast. AT&T and Elevance Health also declined despite positive Earnings developments.
Market Movers
Among the top-performing stocks of the session Springview Holdings Ltd. surged 45.68%, while SVRN, Inc. rallied 41.49%. On the losing side, SCWorx Corp. fell 33.88%, while AEVEX Corp. declined 32.50%, making them the weakest performers during the trading day.
Commodities Update
Crude oil rose near USD 100 per barrel on Thursday, a five-week high, while Brent approached USD 112 as concerns over renewed US strikes against Iran and escalating Middle East tensions heightened Supply risks. Reports of planned US-Israeli military operations, the evacuation of non-emergency US personnel from Saudi Arabia, and attacks on Saudi energy facilities supported prices. Although crude exports through the Strait of Hormuz recovered toward pre-conflict levels, restricted refined-product shipments continued to fuel concerns over global energy supplies.
Gold fell below USD 4,100 per ounce and silver declined toward USD 56 on Thursday, reversing recent gains as escalating Middle East tensions lifted oil prices and intensified Inflation concerns. Attacks on Saudi energy infrastructure and reports of potential renewed US-Israeli strikes on Iran heightened expectations of persistent energy-driven inflation. While the Federal Reserve is expected to hold rates steady next week, prospects of a December rate hike weighed on non-yielding precious metals. The European Central Bank and Bank of Japan are also expected to keep rates unchanged.
Macro Updates
Dollar Steadies as Fed Outlook and Inflation Risks Take Focus
The US dollar index held near 101.7 on Thursday as investors anticipated unchanged interest rates from the Federal Reserve, European Central Bank and Bank of Japan next week. However, rising oil prices amid escalating Middle East tensions sustained inflation concerns and expectations of a potential Fed rate hike in December, while weaker US housing data signalled slowing economic activity.
US Crude and Gasoline Inventories Record Larger-Than-Expected Draws
US crude inventories fell by 3.061 million barrels in the week ended October 16, exceeding the expected 0.8 million-barrel draw, while gasoline stocks declined by 2.952 million barrels against a projected 0.4 million-barrel decrease. However, distillate inventories unexpectedly rose by 1.675 million barrels, and Cushing stocks increased by 0.987 million barrels. Refinery crude runs edged up by 34,000 barrels per day, while net crude imports rose by 837,000 barrels per day.
Bonds Commentary
The US 10-year Treasury Yield fell to around 5.08% on Thursday as a global technology selloff boosted Demand for government bonds, while weaker housing data reinforced concerns over slowing economic growth. Investors expect the Federal Reserve to hold rates steady next week, although rising oil prices amid Middle East tensions sustained inflation concerns and expectations of a possible December rate hike.
Futures Update
US stock futures declined on Thursday, with S&P 500 futures down 0.9%, Nasdaq 100 futures falling 1.6% and Dow futures losing nearly 110 points, as disappointing earnings and continued selling in semiconductor shares weighed on sentiment. Rising oil prices and geopolitical tensions added pressure. Lam Research fell over 7% on a weak outlook, while Tesla, IBM and Nvidia dropped 3.2%, 4.2% and 2%, respectively. Meta and Honeywell also declined despite positive results or guidance, while Lockheed Martin gained 2.6% after beating earnings and Revenue expectations.
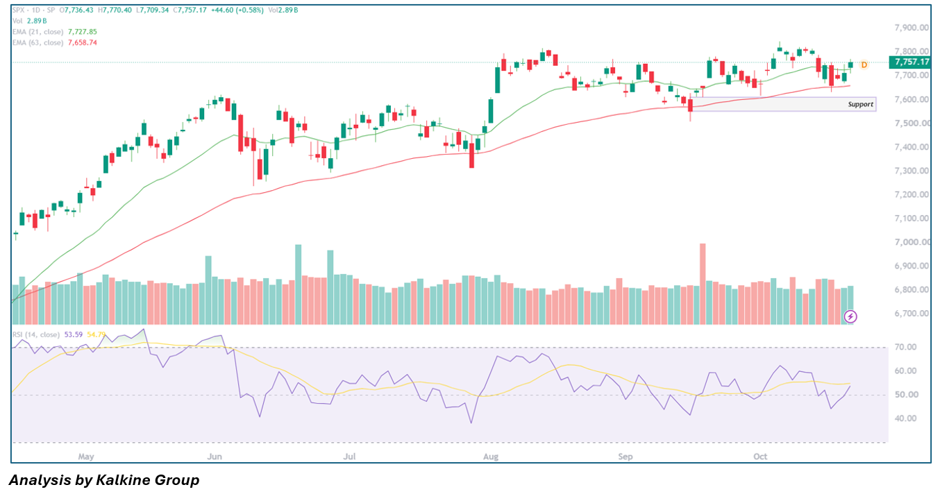
Stocks fluctuated early on Wednesday but drifted higher through the session, with all the major averages finishing up and the tech-heavy Nasdaq posting a notable gain, despite some late volatility. SPX ended at 7,757.17 (+0.58%) after rebounding from a 7,709 low, and the intraday bearish view is to fade this rally into resistance at 7,770 and 7,800-7,815, since the bounce is struggling below the early-October lower highs, has come on below-average volume, and RSI (53.59) sits under its signal line (54.79) and below 60, pointing to soft momentum inside the 7,630-7,840 range that has held since August. A loss of the 21 EMA at 7,728 would be the first trigger, with targets at 7,709, then 7,660-7,630 (63 EMA and recent swing low), and finally the 7,560-7,610 support zone, while a sustained move above 7,770 (especially 7,815) or RSI back over 60 would invalidate the setup.

 Oct 28, 2026
 Please wait processing your request...