
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mostly higher on Tuesday, with the S&P 500 gaining 0.3% and the Dow rising 530 points, while the Nasdaq slipped 0.1%. Lower Treasury yields and energy prices supported expectations of a Fed pause next week, lifting financial and healthcare shares. 3M surged 5.8% after beating Earnings estimates and raising its outlook, while General Motors fell 6.8% after narrowing its profit forecast. SpaceX and Netflix eased ahead of their earnings releases.
Market Movers
Among the top-performing stocks of the session WISeSat.Space Holdings Corp. surged 100.59%, while Alpha Technology Group Limited. rallied 52.64%. On the losing side, Picard Medical, Inc. fell 32.17%, while Freightcar America, Inc. declined 31.37%, making them the weakest performers during the trading day.
Commodities Update
Crude oil climbed to around USD 100 per barrel on Wednesday, its highest since September 17, while Brent approached USD 111, a five-month high, as reported vessel attacks near Oman and a supertanker mine strike heightened Supply concerns in the Strait of Hormuz. However, shipments through the waterway remained relatively strong, with flows reportedly nearing prewar levels and broader Middle Eastern exports rising since summer. Investors awaited official US inventory data after the API reported a 4.9 million-barrel decline in weekly crude stocks.
Gold fell toward USD 4,100 per ounce on Wednesday, extending losses for a fourth consecutive session, while silver eased toward USD 57.5 as rising oil prices fuelled Inflation concerns and expectations of higher interest rates. Persistent geopolitical tensions, tanker attacks in the Strait of Hormuz and fading hopes of an imminent US-Iran peace deal heightened supply concerns. The Federal Reserve, Bank of Japan and European Central Bank are expected to hold rates steady next week, although markets anticipate a possible Fed hike in December, reducing the appeal of non-interest-bearing precious metals.
Macro Updates
US Mortgage Demand Weakens Despite Lower Borrowing Rates
US mortgage applications fell 5.3% in the week ended October 16, 2026, marking a seventh consecutive weekly decline and reaching their lowest level since January 2025, according to the Mortgage Bankers Association. Home purchase applications dropped 7.3%, while refinancing activity declined 2%. Although the average 30-year fixed mortgage rate eased 9 basis points to 7.41%, borrowing costs remained near a three-year high, weighing on housing demand amid energy-driven inflation concerns and expectations of prolonged elevated interest rates.
Dollar Stabilises as Oil Prices Reinforce Inflation Concerns
The US dollar index steadied near 101.7 on Wednesday after touching three-week lows, supported by safe-haven demand as rising oil prices fuelled inflation concerns. Hopes of an imminent US-Iran peace agreement faded, while markets expected the Federal Reserve to hold rates next week before a possible December hike. The yen remained rangebound ahead of an anticipated Bank of Japan pause, while the euro stabilised as unrest across France and other European countries subsided.
US Crude Inventories Post Larger-Than-Expected Draw
US crude inventories fell by 4.93 million barrels in the week ended October 16, exceeding expectations for a 1.3 million-barrel draw and following an 11.12 million-barrel decline the previous week. Gasoline and distillate stocks decreased by 2 million and 2.6 million barrels, respectively, while Cushing inventories rose by 900,000 barrels. Separately, US oil production declined to 13.679 million barrels per day in the week ended October 9, from 13.979 million barrels per day a week earlier.
Bonds Commentary
The US 10-year Treasury Yield held near 5.12% on Wednesday as rising oil prices reinforced inflation concerns and expectations of a possible December Fed rate hike, despite an anticipated pause next week. Fading hopes of an imminent US-Iran peace deal supported oil prices, while persistent energy inflation, mounting government Debt and weakening fiscal conditions continued to pressure bond markets.
Futures Update
US stock futures rose on Wednesday, with S&P 500 and Nasdaq 100 futures gaining 0.2% and 0.7%, respectively, while Dow futures added around 30 points as investors assessed corporate earnings. SpaceX surged over 8% following strong Revenue growth and Merger speculation involving Tesla, which gained 1.4% ahead of its results. Super Micro Computer jumped nearly 12% on upbeat earnings, while Netflix, AT&T and Philip Morris fell 6.5%, 4.1% and 2.5%, respectively. Meta slipped 0.6% ahead of its earnings release.
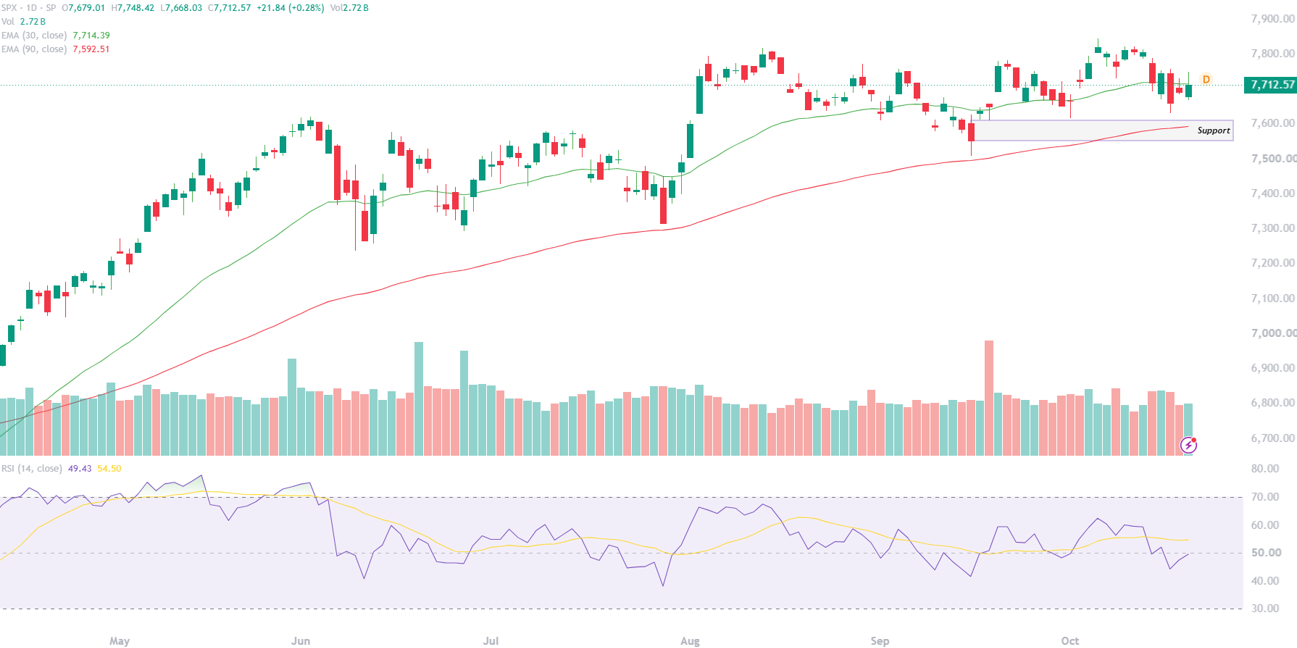
Stocks recovered from an early dip and mostly climbed in the morning, but they surrendered some of those gains by the close on Tuesday. The tech-heavy Nasdaq slipped just below the unchanged line, while the Dow held a solid gain and posted its best close in over a month. The SPX finished at 7,712.57 (+0.28%), right on its 30 EMA (7,714), which makes that level the pivot for the next session. A hold above it favors a mild bounce toward 7,748 and then 7,790-7,800, whereas a rejection followed by a break below 7,668 would open the way to 7,630 and the 7,550-7,605 support zone, home to the 90 EMA at 7,592. With RSI at 49.4 still under its average of 54.5 and Volume unremarkable, momentum remains unconfirmed, so the most likely outcome is choppy trade between roughly 7,670 and 7,750 until one side breaks. This is a chart read rather than a trade recommendation, and I’m not a financial advisor.

 Oct 28, 2026
 Please wait processing your request...