
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks declined sharply on Thursday as concerns over AI Investment returns and elevated borrowing outweighed enthusiasm for Anthropic’s debut. The S&P 500 fell 2%, the Nasdaq dropped 2.2%, and the Dow lost 1,101 points. Anthropic ended 17.1% above its IPO price, retreating from its opening surge. Nvidia fell 3.3%, AMD slid 7.7% amid China-related concerns, and Amazon and Meta also weakened. JPMorgan, Visa, and Mastercard declined following disclosures of customer data exposure in a vendor cyberattack.
Market Movers
Among the top-performing stocks of the session Mega Matrix Inc. surged 67.61%, while Vivid Seats Inc. rallied 63.28%. On the losing side, StoneX Group Inc. fell 26.71%, while SAIHEAT Limited. declined 25.24%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded near USD 82 per barrel, its lowest in almost three months, while Brent fell below USD 92 on Friday, with both heading for a third consecutive weekly decline as Supply concerns outweighed geopolitical risks. Record oil flows through the Strait of Hormuz, recovering Middle Eastern supplies, and a US–China–Russia agreement to boost refined petroleum output weighed on prices. The IEA projected a quarterly surplus of approximately 2 million barrels per day, while Goldman Sachs warned of potential oversupply next year. Meanwhile, President Trump said he was in no rush to decide on Iran despite reports of possible renewed US strikes.
Gold and silver fell toward USD 3,500 and USD 42 per ounce, respectively, on Friday, their lowest levels since September 2025, heading for weekly declines of nearly 9% and over 13%. A stronger US dollar, expectations of further Federal Reserve tightening—including a possible 50-basis-point December hike—and Liquidation to cover Equity losses pressured precious metals. Meanwhile, copper dropped to around USD 5.50 per pound, its lowest in over seven months, amid concerns over AI infrastructure spending, potential restrictions on Data Center development, and weaker Chinese industrial activity, although tight Shanghai inventories limited further losses.
Macro Updates
Dollar Holds Firm on Safe-Haven Demand and Hawkish Fed Outlook
The dollar index steadied near 103.8 on Friday, close to its April 2025 highs and heading for a fourth consecutive weekly gain, up 0.5%. Safe-haven demand amid the global equity selloff, expectations of higher interest rates, and overseas inflows into Anthropic’s IPO supported the greenback, although it weakened against the yen.
Bonds Commentary
The US 10-year Treasury Yield fell for a fifth consecutive session to 4.98% on Friday, down nearly 15 basis points for the week, while the two-year yield declined 12 basis points to 4.71%. Safe-haven demand amid the equity selloff and easing Inflation concerns from lower oil prices supported bonds. However, expectations of prolonged monetary tightening limited yield declines, with markets pricing in 25-basis-point hikes in December and January, followed by another increase by end-2027.
Futures Update
US stock futures fell on Friday as the AI selloff deepened, with S&P 500 and Nasdaq 100 contracts declining nearly 1% and 2%, respectively, while Dow futures were flat. Anthropic dropped over 10% premarket after its debut rally, major chipmakers fell up to 5%, and AMD faced a two-session decline of 14% amid concerns over Chinese export restrictions. Elevated borrowing costs and planned Medicare Advantage audits added pressure on technology stocks and health insurers, respectively. The S&P 500 and Nasdaq 100 were heading for weekly losses exceeding 6%. 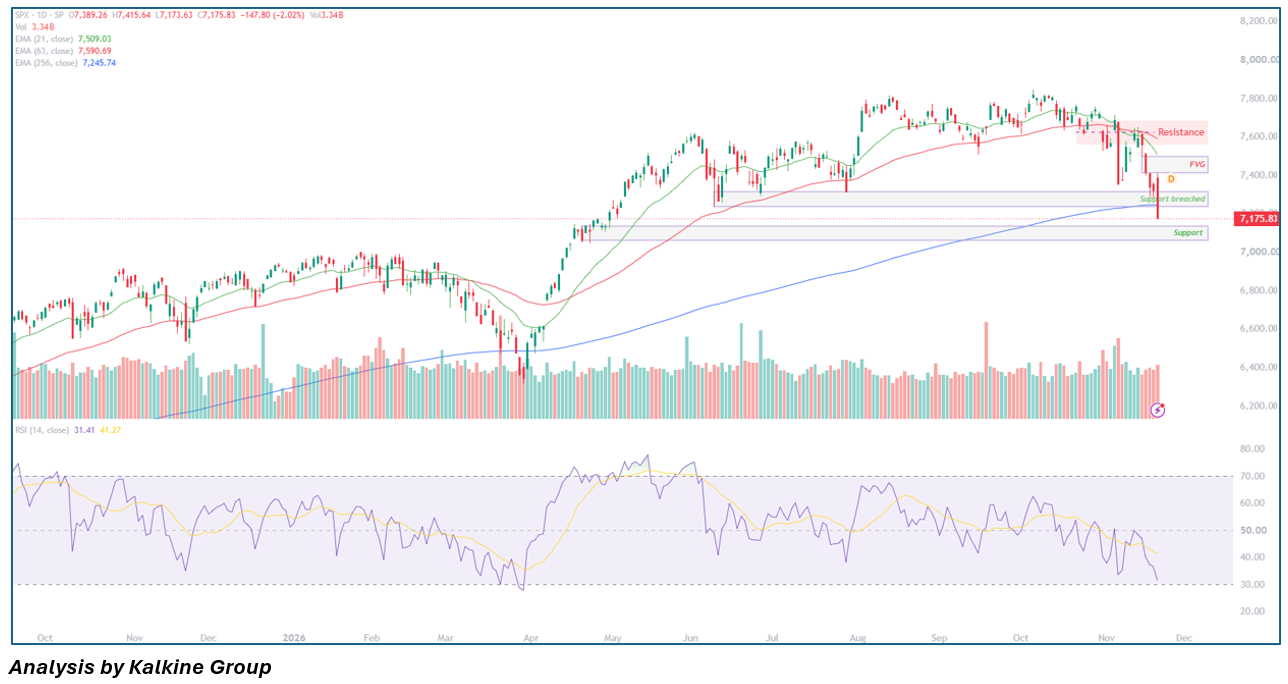
SPX exhibits a sharp intraday bearish breakdown setup, tumbling -2.02% (-147.80 pts) to trade at 7,175.83 after opening at 7,389.26, briefly testing an early session peak of 7,415.64 into the overhead Fair Value Gap (FVG), and sliding directly to its session low of 7,173.63 on elevated Volume of 3.34B shares. Price action has decisively breached both the prior horizontal demand shelf (7,240.00–7,315.00) and the 256-day Moving Average (7,245.74), confirming heavy intraday seller control well beneath the declining 21-day EMA (7,509.03) and 63-day EMA (7,590.69). Downward momentum continues to accelerate as the 14-day RSI drops to 31.41 (below its 41.27 signal line), pressing directly against the 30.00 oversold threshold. With spot now resting immediately above the secondary horizontal support band (7,060.00–7,130.00), intraday rebounds remain capped beneath the 7,240.00–7,315.00 breakdown zone, while a breach below 7,060.00 exposes deeper downside toward 6,900.00.

 Nov 18, 2026
 Please wait processing your request...